



PW Consulting: TCB Bonder Market Hits $203.25M in 2025, Poised for 18.31% CAGR Growth Through 2032

The TCB Bonder Market at an Inflection Point: Why 2026 Demands Precision Intelligence
The thermal compression bonder market is no longer operating in a phase of incremental growth. Between 2020 and 2025, the sector expanded from 85.7 million USD to 203.25 million USD, reflecting an acceleration that mirrors the semiconductor industry's structural pivot toward advanced packaging, heterogeneous integration, and high-density interconnects. Our latest TCB Bonder Market report maps this trajectory across a forecast horizon extending to 2032, projecting sustained expansion at a CAGR of 18.31 percent. For executives navigating capital allocation, technology roadmaps, and supply chain resilience in 2026, this is not a market that rewards superficial observation. It demands a granular, forward-looking intelligence framework.
The Growth Architecture: What the Numbers Signal for 2026 Planning
The revenue curve tells a clear story of compounding momentum. From 124.78 million USD in 2022, the market climbed to 144.75 million USD in 2023, then 171.85 million USD in 2024, before reaching 203.25 million USD in 2025. The forecast places 2026 at 237.34 million USD, with successive years projecting 285.27 million USD in 2027, 338.79 million USD in 2028, and 419.37 million USD by 2029. By 2032, the market is positioned to approach 679.93 million USD. These figures are not merely historical bookkeeping; they define the strategic bandwidth companies must allocate to bonding equipment, process validation, and capacity planning.
For 2026 specifically, the transition from 203.25 million USD to 237.34 million USD represents a critical inflection. This is the year when procurement cycles, technology qualification timelines, and capacity expansion decisions converge. Organizations that rely on fragmented supplier data or outdated equipment catalogs will face compounding friction as lead times tighten and process specifications become more exacting. Our report is structured to remove that uncertainty by delivering a comprehensive view of the market's size, trajectory, and the operational variables that will determine execution success.
What the Report Delivers: Operational Intelligence Beyond Macro Trends
A market research document earns its place on an executive's desk when it converts aggregate data into actionable decision architecture. This TCB Bonder Market report is built around that principle. Rather than stopping at headline figures, the analysis decomposes the landscape into dimensions that directly shape sourcing, deployment, and competitive positioning.
TCB Bonder Market
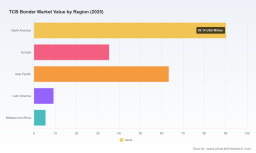
The report examines the market through three structural lenses. First, it analyzes the equipment classification landscape, differentiating between automated and manual bonding platforms and mapping how each category aligns with production volume, precision requirements, and capital intensity. Second, it evaluates application-driven demand drivers, focusing on the segments that are pulling bonding capacity into new configurations, including integrated device manufacturing systems and outsourced semiconductor assembly and testing operations. Third, it traces regional demand distribution, identifying where capacity expansion, technology adoption, and procurement concentration are converging, and where latent growth pockets remain under-monitored.
Beyond segmentation, the report provides a detailed competitive landscape assessment. Market concentration is a defining feature of this sector, with the top three players accounting for 52.5 percent of total market revenue and the top five reaching 68.0 percent. That concentration has direct implications for pricing leverage, technology access, and partnership strategy. The analysis profiles the incumbents that are shaping equipment standards, process norms, and qualification expectations, giving buyers and investors a clear view of where differentiation is being created and where competitive pressure is intensifying.
The report also incorporates regulatory and operational context that frequently determines whether a bonding investment succeeds or stalls. Medical device applications, for example, represent a meaningful revenue share within the thermal compression bonder market, and they carry qualification requirements that extend well beyond standard production tolerances. Class II and Class III medical device manufacturing environments demand full material lot traceability, process documentation, and yield assurance protocols that drive premium pricing for medical-grade bonding systems. These requirements are not peripheral details; they are decision-critical variables that shape total cost of ownership, supplier selection, and deployment timelines. The report integrates these operational realities so that 2026 planning accounts for both technical performance and compliance architecture.
Competitive Landscape: Where Capability Is Being Concentrated
The TCB bonder market is shaped by a handful of firms that have invested heavily in precision control, throughput optimization, and application-specific process architectures. Understanding their distinct positioning is essential for companies evaluating equipment partnerships, capacity expansion, or technology migration in 2026.
Kulicke & Soffa Industries, headquartered in Willow Grove, Pennsylvania, has built its TCB bonder offering around the APAMA PLUS series and advanced thermo-compression bonding platforms. These systems are engineered for ultra-fine pitch interconnects, with precise heat-and-pressure control optimized for high-density semiconductor assembly. For organizations pursuing advanced packaging roadmaps where interconnect density and thermal management are primary constraints, K&S represents a benchmark for process precision and platform scalability.
ASMPT Amicra, based in Singapore, has focused its TCB bonder portfolio on high-volume production efficiency. Its NOVA Pro die attach systems support die placement accuracies down to ±1.5 μm at 3σ, with cycle times reaching as low as 3 seconds per bond. This combination of sub-micron placement precision and rapid throughput positions the company strongly in environments where volume, repeatability, and equipment utilization are decisive competitive factors.
BE Semiconductor Industries N.V., operating from Duiven in the Netherlands, has established a strong presence through thermocompression bonding systems deployed at volume for advanced flip chip and die bonding applications. Its equipment footprint extends into some of the most technologically demanding integration architectures, including CoWoS and HBM-related packaging flows. For firms tracking the equipment supply chain behind advanced logic and memory packaging, BESI's capabilities are directly relevant to process continuity and yield performance.
Toray Engineering, headquartered in Japan, has developed flip chip bonders that support TCB, DAF, and hybrid bonding across wafer and large panel sizes up to 600 mm by 600 mm. This dimensional flexibility is increasingly significant as packaging formats expand beyond traditional die-scale processing and as panel-level integration gains traction. Toray's platform breadth makes it a notable reference point for organizations evaluating multi-mode bonding strategies and larger-format handling capabilities.
CTBN Market
Palomar Technologies, based in Carlsbad, California, anchors part of its TCB bonder strategy in the 3880-II Die Bonder series, which applies thermocompression bonding processes for ultra-precise applications in medical devices and photonics. This positioning reflects a broader market reality: precision bonding is no longer confined to mainstream semiconductor assembly. It is expanding into niche but high-value domains where process stability, repeatability, and documentation rigor carry substantial commercial weight.
These profiles are not isolated product summaries. Together, they reveal how capability is being distributed across precision, throughput, format flexibility, and application specialization. The report examines these dynamics in greater depth, mapping how each player's strengths intersect with buyer requirements and where competitive differentiation is likely to sharpen through 2032.
Market Dynamics and the 2026 Decision Environment
The TCB bonder market does not evolve in isolation. It is shaped by the intersection of packaging complexity, capacity constraints, qualification demands, and the operational discipline required to scale precision manufacturing. In 2026, several forces converge to make equipment strategy a board-level concern rather than a departmental procurement exercise.
First, advanced packaging demand continues to pull bonding requirements toward finer pitch, tighter thermal control, and more demanding alignment tolerances. As interconnect architectures become denser and package formats more heterogeneous, bonding equipment must deliver repeatable process windows that hold across high-mix and high-volume conditions alike. This raises the stakes for equipment selection, because process migration later in a product lifecycle is far more costly than upfront qualification discipline.
Second, concentration in the competitive landscape means that procurement leverage, technology access, and supply continuity are intertwined. With the top five firms controlling more than two-thirds of market revenue, buyers must navigate a landscape where supplier relationships, process compatibility, and long-term support capacity can matter as much as unit pricing. The report's competitive analysis is designed to clarify where dependency risk exists and where alternative pathways remain viable.
Third, application-specific requirements are reshaping total cost calculations. Medical device bonding applications illustrate this clearly. They represent a distinct revenue share within the thermal compression bonder market and impose documentation, traceability, and qualification obligations that elevate system cost but also create defensible pricing structures for suppliers that can meet the standard. For 2026 planning, this means that market participation cannot be assessed purely on volume potential; process qualification burden, compliance readiness, and yield assurance must be factored into investment decisions.
Why the Full Report Matters for 2026 Strategy
Executive decisions in this market are won or lost on the quality of the underlying intelligence. Headline market size and CAGR provide direction, but they do not answer the operational questions that determine execution: which equipment category aligns with a given production profile, where regional demand is intensifying, how concentration affects sourcing strategy, and what qualification pathways are required for application-specific deployment. The full TCB Bonder Market report is built to answer those questions with structure and specificity.
The document is designed as a decision-support asset rather than a static market summary. It connects the macro trajectory to the operational layers that determine whether a 2026 investment scales efficiently or encounters friction later. For capital planning, it provides the framework needed to evaluate equipment type, application alignment, and regional demand distribution without relying on fragmented data. For competitive strategy, it offers a structured view of the incumbents that are defining process norms, throughput benchmarks, and precision standards. For risk management, it incorporates the compliance and qualification realities that can influence supplier selection and deployment timing.
The report also preserves forward visibility. By extending the forecast horizon to 2032, it allows organizations to test 2026 commitments against longer-term market evolution, rather than optimizing for a single annual cycle. That continuity is critical in a market growing at a CAGR of 18.31 percent, where early positioning can compound into structural advantage or entrenched disadvantage.
Moving from Market Awareness to Strategic Advantage
The TCB bonder market is entering a phase where scale, precision, and application complexity reinforce one another. The revenue expansion from 85.7 million USD in 2020 to a projected 679.93 million USD by 2032 reflects more than demand growth; it reflects a structural reorientation of semiconductor packaging toward bonding-intensive architectures and high-value precision manufacturing. In that environment, 2026 is not a routine planning year. It is a decisive window for aligning equipment strategy, supplier relationships, and process qualification with the market's trajectory.
The full TCB Bonder Market report provides the depth required to navigate that window with confidence. It translates the headline growth narrative into segmented analysis, competitive profiling, compliance-aware application context, and forward-looking market structure. For organizations that need to move beyond aggregate trends and into execution-ready intelligence, the complete study is the necessary next step.
Access the full report to capture the complete segmentation detail, the regional and application-level market architecture, the competitive concentration analysis, and the operational variables that will shape 2026 investment decisions. The macro direction is clear; the strategic advantage lies in the specifics.
For detailed analysis of this topic, please visit the official page: TCB Bonder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


