



PW Consulting: Mercury Adsorbents Market Hits $1.55B in 2025, 6.2% CAGR to 2032

Navigating the Mercury Removal Adsorbents Market: Strategic Imperatives for 2026 and Beyond
The global industrial landscape is undergoing a profound transformation driven by increasingly stringent environmental regulations and a heightened focus on operational safety. Within this shifting paradigm, the mercury removal adsorbents market stands as a critical enabler for energy infrastructure, chemical processing, and emissions control. As we move into 2026, stakeholders across the value chain face a complex matrix of growth opportunities, technological shifts, and cost pressures that demand precise strategic navigation. This article serves as an executive preview of our latest comprehensive market study, designed to equip decision-makers with the actionable intelligence required to capitalize on emerging trends while mitigating inherent risks.
Our analysis indicates that the global market for mercury removal adsorbents is poised for steady expansion. Valued at approximately 1,553.81 million USD in the base year of 2025, the sector is projected to reach 2,370.91 million USD by the end of the forecast period in 2032. This trajectory reflects a compound annual growth rate of 6.2 percent, signaling a robust demand environment fueled by regulatory compliance and infrastructure modernization. However, raw numerical growth tells only part of the story. The true strategic value lies in understanding the underlying dynamics that will dictate competitive positioning, supply chain resilience, and product portfolio optimization over the coming years.
Worldwide Zeolite Adsorbents Market
Market Scale and Growth Trajectory
The historical data from 2020 through 2025 reveals a consistent upward trend, with revenue climbing from 1,160.65 million USD to the current 1,553.81 million USD benchmark. This five-year growth phase was characterized by gradual adoption rates and incremental regulatory tightening. Looking forward, the forecast period from 2026 to 2032 suggests an acceleration in market valuation, with significant jumps anticipated as global industries align with stricter emissions standards. The projection of 1,594.41 million USD for 2026 alone underscores the immediate commercial relevance of this sector for investors and operational leaders alike.
While the aggregate figures provide a macro view, the strategic nuance lies in the segmentation of demand. The market is diversified across several key types, applications, and regions, each presenting distinct growth profiles. Activated carbon continues to represent a substantial portion of the product mix, reflecting its established role in flue gas and process stream treatment. However, specialized solutions such as sulfur-impregnated carbon and other advanced material types are gaining traction due to their superior sequestration capabilities in challenging operating conditions. Understanding the relative performance and adoption rates of these product categories is essential for companies aiming to align their R&D investments with market demand.
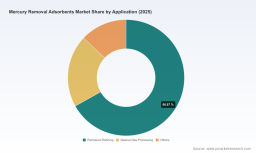
Application-wise, the petroleum refining sector remains a dominant driver of consumption, leveraging adsorbents to protect catalysts and meet environmental discharge limits. Natural gas processing follows as another critical demand center, where mercury removal is vital for preventing equipment corrosion and ensuring product purity for LNG and pipeline transport. Other applications, spanning industrial exhaust and water treatment, contribute to the broader ecosystem but often require tailored solutions that differ significantly from bulk industrial uses. The geographic distribution of demand further complicates the landscape, with mature markets in North America and Europe facing different regulatory and cost structures compared to the rapidly industrializing regions in Asia Pacific and Latin America.
Competitive Landscape and Key Players
The market structure is moderately fragmented, with a consolidated top tier of established multinational corporations holding significant market share. Our analysis highlights a CR3 of 24.6 percent and a CR5 of 26.2 percent, indicating that while a few major players dominate, there remains substantial room for specialized niche providers and regional specialists. The competitive arena is defined by continuous innovation in adsorbent chemistry, regeneration capabilities, and integration with downstream processing systems.
Calgon Carbon Corporation, headquartered in Pittsburgh, maintains a strong presence through its HGR, Fluepac, and HGR-P product lines. These sulfur-impregnated granular and powdered activated carbon solutions are specifically engineered for mercury removal from natural gas, flue gas, and various process streams. Their focus on granular and powdered formats allows for flexible deployment in both fixed-bed and injection systems, catering to diverse operational requirements.
UOP, a Honeywell company based in Des Plaines, offers a differentiated portfolio with its UOP GB series of non-regenerative metal sulfide adsorbents and HgSIV regenerable molecular sieve adsorbents. These products are designed for total mercury sequestration from natural gas, LPG, and light hydrocarbon streams, providing operators with options between single-use and regenerable technologies depending on throughput and economic considerations.
Johnson Matthey, operating from London, contributes the PURASPEC range of mixed metal sulfide absorbents. This product family is recognized for effective and complete mercury removal in both gas and liquid phase duties, making it particularly relevant for complex processing streams where phase versatility is required. The emphasis on mixed metal formulations highlights the industry's shift toward high-capacity chemistries that can handle variable feed compositions.
Cabot Corporation, based in Boston, focuses on the DARCO Hg family of powdered activated carbon products. These are primarily targeted at flue gas mercury removal, addressing emissions control requirements in power generation and industrial boilers. The powdered format is optimized for injection systems that require rapid kinetics and fine particle distribution to maximize capture efficiency.
Pall Corporation, located in Port Washington, provides integrated systems and solutions for mercury removal from natural gas. Their approach combines adsorption technology with engineered systems, offering both non-regenerative and regenerative adsorbents. This system-integration perspective allows customers to optimize lifecycle costs and operational simplicity, particularly in remote or offshore gas processing environments.
Nucon International Inc., operating out of Columbus, offers the MERSORB series of impregnated activated carbons. These products are designed for mercury removal across a broad spectrum of media, including air, natural gas, process exhaust gases, water, and petroleum liquids. The versatility of the MERSORB line positions it as a multi-application solution for facilities managing multiple emission and effluent streams simultaneously.
Axens, headquartered in Rueil-Malmaison, France, brings the AxTrap 200 series to the market. This includes non-regenerative and ready-to-use adsorbents such as AxTrap 273 and AxTrap 277, specifically formulated for mercury removal from hydrocarbons. A notable feature is the safe air-loading capability, which addresses operational safety concerns during adsorbent change-out and startup procedures in hydrocarbon processing facilities.
BASF SE, based in Ludwigshafen, Germany, offers the Durasorb HG mixed metal oxide adsorbent. This product is engineered for high-capacity mercury removal from natural gas under wet conditions, addressing a specific operational challenge where moisture can degrade the performance of conventional adsorbents. The focus on wet-condition performance reflects the industry's need for robust solutions in humid or subsea processing environments.
SLB, formerly Schlumberger, headquartered in Houston, provides the SELECT Hg mixed metal sulfide-based adsorbents. These are designed for effective mercury removal from a wide range of hydrocarbon streams, including natural gas, crude oil, condensates, and LNG. The breadth of stream compatibility positions SLB's offering as a comprehensive solution for upstream and midstream operators managing diverse production fluids.
Market Dynamics and Strategic Challenges
Despite the favorable growth outlook, the market is not without significant headwinds that require strategic attention. One of the most pressing challenges is the cost structure associated with advanced mercury removal technologies. Industry data indicates that costs for advanced mercury removal solutions remain 20 to 30 percent higher than conventional activated carbon. This premium reflects the specialized impregnation chemistries, manufacturing complexity, and performance guarantees required for high-efficiency removal. For operators, this cost differential translates into a careful balancing act between compliance assurance and operational expenditure, particularly in margin-sensitive segments of the petroleum and gas industries.
Furthermore, the high cost of mercury removal adsorbents is expected to hamper market growth over the forecast period to some extent. While demand is inelastic in highly regulated applications, price sensitivity remains a factor in less stringent environments or in regions where compliance enforcement is still evolving. Companies entering this space must carefully evaluate total cost of ownership, including not just the purchase price of the adsorbent but also regeneration cycles, disposal logistics, and system downtime.
A critical and often underestimated dynamic is the disposal cost of spent adsorbents. Spent media disposal costs can reach between 500 and 2,000 USD per ton, depending on regional regulations, waste classification, and transportation logistics. This disposal burden can significantly impact the lifecycle economics of adsorbent-based removal systems. Operators in regions with stringent hazardous waste regulations face particularly acute cost pressures, which may drive demand for regenerable adsorbents or alternative treatment technologies that reduce waste volume. The financial magnitude of disposal costs also creates an incentive for innovation in adsorbent lifetime extension and saturation monitoring, as maximizing the usable capacity of each adsorbent batch directly reduces disposal frequency and associated fees.
Sustainability considerations are increasingly shaping product development and procurement strategies. There is a noticeable movement toward selenium- and sulfur-based solutions for sustainability in mercury removal adsorbents. These chemistries are being explored not only for their removal efficiency but also for their potential to reduce environmental footprint during production and disposal. As regulatory frameworks evolve to incorporate broader sustainability criteria, adsorbents that align with green chemistry principles may gain a competitive advantage in procurement evaluations, particularly among multinational operators with explicit ESG commitments.
Mercury Removal Adsorbents Market
Report Scope and Strategic Utility for 2026 Decision-Making
Our comprehensive market research report is designed to move beyond high-level trends and deliver the granular intelligence required for operational and strategic planning. The study covers the historical period from 2020 to 2025 and provides a detailed forecast extending through 2032, allowing stakeholders to model long-term investment returns and capacity planning scenarios. All revenue figures are presented in USD million, ensuring consistency for international benchmarking and cross-regional comparison.
The report delves deeply into market segmentation, offering detailed breakdowns by type, application, and region. This segmentation analysis is critical for companies seeking to identify high-growth pockets within the broader market or to assess the competitive intensity in specific product categories. For instance, understanding the relative adoption rates of sulfur-impregnated carbon versus other advanced types can inform product development roadmaps and marketing positioning. Similarly, application-level insights help operators and suppliers align their technical offerings with the most economically viable demand centers, whether in petroleum refining, natural gas processing, or niche industrial applications.
Regional analysis is another cornerstone of the study. While aggregate regional values provide a snapshot of demand distribution, the report goes further to analyze the underlying drivers, regulatory timelines, and infrastructural factors that shape regional growth trajectories. This includes an examination of how mature markets are transitioning toward more advanced, regenerable solutions, while emerging markets are scaling up their baseline adsorption capacity to meet new compliance mandates. Such regional granularity is essential for supply chain optimization, localization strategies, and market entry planning.
The competitive landscape section of the report provides detailed profiles of the key players shaping the market. Each profile examines the company's specific product offerings, technological focus, and strategic positioning within the mercury removal adsorbents ecosystem. This analysis enables stakeholders to benchmark their own portfolios against industry leaders, identify potential partnership or acquisition targets, and anticipate competitive responses to market shifts. The inclusion of recent developments and strategic moves by these companies further illuminates the dynamic nature of the competitive arena.
In addition to quantitative data and company profiles, the report synthesizes critical market dynamics that influence strategic decision-making. The analysis of cost pressures, disposal economics, and sustainability trends provides a framework for evaluating the robustness of different business models and operational strategies. Decision-makers can use these insights to stress-test their pricing strategies, evaluate the viability of regenerable versus non-regenerative product lines, and assess the potential impact of evolving waste regulations on their customer base.
For 2026 and the years ahead, the ability to navigate the intersection of regulatory compliance, cost efficiency, and technological innovation will define market success. Companies that can offer high-capacity, cost-effective, and environmentally sustainable adsorbent solutions will be best positioned to capture growth. Likewise, operators that proactively manage adsorbent lifecycle costs, including disposal and regeneration, will gain a competitive edge in operational efficiency. This report serves as a strategic compass, providing the data, analysis, and contextual understanding necessary to make informed decisions in a market that is both lucrative and complex.
The detailed segmentation data, regional breakdowns, and competitive intelligence contained within the full study are essential for translating macro trends into actionable tactics. Readers interested in accessing the complete dataset, including specific regional revenue figures, application split percentages, and in-depth company benchmarking, are encouraged to explore the full report through our official channels. The comprehensive intelligence housed in the study is designed to support strategic planning, investment analysis, and operational optimization for years to come.
For detailed analysis of this topic, please visit the official page: Mercury Removal Adsorbents Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


