



PW Consulting: LSA Market Hits $606M in 2025, Forecast to Reach $845M by 2032 at 4.85% CAGR

The Light Sport Aircraft Market: Strategic Horizons for 2026 and Beyond
The Light Sport Aircraft (LSA) sector is currently navigating a transformative period defined by regulatory evolution, shifting consumer preferences, and a steady expansion of market boundaries. For stakeholders operating within general aviation, aviation manufacturing, or flight training ecosystems, understanding the trajectory of this market is no longer optional—it is a strategic imperative. Our latest market research publication, the Light Sport Aircraft (LSA) Market report, offers a comprehensive examination of the industry’s past performance and future potential, designed specifically to inform high-stakes decision-making in 2026 and onwards.
This article serves as a strategic preview of the research, outlining the broader economic narrative, the regulatory forces reshaping the competitive landscape, and the practical intelligence contained within the full study. By exploring the structural dynamics of the LSA market, we aim to highlight why precise, data-backed intelligence is critical for capital allocation, product development, and market entry strategies in the coming years.
Market Trajectory: Steady Growth Amid Evolving Demand
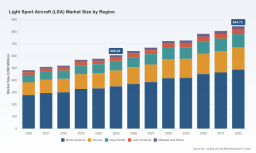
The LSA market has demonstrated consistent resilience over the past half-decade. Between 2020 and 2025, the market navigated the complexities of a post-pandemic aviation landscape while maintaining a clear upward revenue trajectory. Historical data indicates that the market size in 2020 stood at approximately 482.35 million, gradually climbing through the subsequent years to reach an estimated 606.25 million by 2025. This growth pattern reflects a steady, compounding expansion rather than volatile spikes, suggesting a maturing market base with sustained demand drivers.
Our forecast analysis projects this positive momentum to continue through the end of the decade and into the early 2030s. We anticipate the market to reach roughly 640.4 million in 2026 and continue its ascent, with projected figures exceeding 844.73 million by 2032. This growth is underpinned by a compound annual growth rate (CAGR) of 4.85 percent. Such a trajectory signals a healthy, long-term expansion phase. However, for strategic planners, the aggregate numbers only tell part of the story. The true value lies in understanding the underlying velocity, the regional drivers, and the application segments that are contributing most significantly to this aggregate growth. The full report dissects these components with granular precision, offering a level of detail essential for targeted strategic planning.
The MOSAIC Rule and the Regulatory Paradigm Shift
No discussion of the LSA market in 2026 can proceed without addressing the profound regulatory changes introduced by the Federal Aviation Administration (FAA). In July 2025, the FAA finalized the MOSAIC rule, a landmark decision that fundamentally alters the definition and eligibility criteria for Light Sport Aircraft. Historically, LSA classifications were heavily constrained by fixed weight and performance metrics. The MOSAIC rule shifts this framework to performance-based criteria, such as stall speed, effectively expanding the scope of eligible aircraft. This includes allowances for higher maximum weights and configurations accommodating up to four seats, provided they meet specific performance thresholds.
The effective dates of this rule create a phased implementation environment. Pilot privileges associated with the new criteria began on October 22, 2025, while the full certification requirements for new make and model combinations will come into force on July 24, 2026. This staggered timeline is of critical importance to manufacturers and operators. It creates a window of adaptation for existing manufacturers while setting a new compliance bar for future entrants. The market impact of MOSAIC is multifaceted: it could stimulate demand by offering aircraft with greater utility and capacity, potentially attracting new demographics of pilots and recreational users. Conversely, it imposes new certification burdens and compliance costs on Special Light Sport Aircraft (SLSA) manufacturers, who must now demonstrate adherence to accepted industry consensus standards for design, production, and airworthiness under 14 CFR §22.100.
Light Sport Aircraft (LSA) Market
Our research provides a detailed analysis of how this regulatory shift is anticipated to redistribute market share, influence type certification strategies, and alter the risk profiles of various aircraft categories. We examine the operational implications of these changes, including the requirement for new make/model combinations to notify the FAA AIR-842 before special airworthiness certificates can be issued. The interplay between expanded market opportunity and heightened regulatory compliance is a central theme of our analysis, offering decision-makers a clear view of the landscape they will operate in.
Competitive Landscape: A Diverse and Fragmented Ecosystem
The LSA market is characterized by a broad and geographically diverse competitive landscape. The industry features a multitude of manufacturers ranging from established aerospace entities to specialized niche producers. This fragmentation contributes to a dynamic environment where innovation and differentiation are key competitive advantages. Our report includes a comprehensive roster of key companies that are actively shaping the market, detailing their operational bases, manufacturing specializations, and compliance profiles.
Prominent participants include entities such as Aero Adventure, based in Deland, Florida, which offers the Aventura II model under FAA 14 CFR 21.190 compliance. AERO AT Sp. z o.o., located in Mielec, Poland, produces the AT-4 LSA series, often utilizing Rotax engine options. Similarly, AeroJones Aviation USA LLC in Zephyrhills, Florida, specializes in the AJ Sport model with Rotax 912 iS engine compliance. The landscape also encompasses manufacturers like Aeropilot SRO in Čáslav, Czech Republic, offering the Legend 600 Amphib series with multiple engine configurations, and Aeroprakt Manufacturing Sp. z o.o. in Zakliczyn, Poland, known for the A-22LS and A32 Vixxen models.
Other significant players include Aeropro CZ in Hluk, Czech Republic, producing Aerotrek and Eurofox models; Aerospool SRO in Prievidza, Slovakia, with the Dynamic WT9; and Aerosport Ltd in Hohentengen, Germany, manufacturing Ikarus C42 series models. The list extends to Air Creation in Aubenas, France, with Tanarg models; Air Elite Aviation in Three Rivers, Michigan, offering the Storm Rally LSA; and Airborne Windsports PTY LTD in Redhead, Australia, producing weight-shift-control EDGE series models.
Manufacturers such as Aircraft Mfg & Development Co in Eastman, Georgia, offer CH series models licensed from Zenair. AirMax Construcoes Aeronauticas in São Paulo, Brazil, produces the SeaMax M-22, while Airtime Aircraft Inc. in Fort Walton Beach, Florida, offers the Cygnet model. The market also includes the American Legend Aircraft Company in Sulphur Springs, Texas, known for AL series models with Continental and Lycoming engines, and Apollo Aircraft Inc in Zephyrhills, Florida, with the Apollo LSA Fox and Delta Jet series.
Further diversity is seen with Arion Aircraft LLC in Shelbyville, Tennessee, offering the Lightning LS-1 with Jabiru engines; Atec VOS in Libice nad Cidlinou, Czech Republic, with the Atec 321 Faeta; and Aveko SRO in Brno, Czech Republic, producing the VL-3C-1. Other notable entities include Bilsam Aviation in Poznań, Poland, with the Sky Cruiser; Breezer Aircraft GmbH in Bredstedt, Germany; and BRM Aero in Kunovice, Czech Republic, offering Bristell series models. Bushcaddy International Inc. in Summerstown, Ontario, produces the BushCaddy Explorer. The list continues with Cessna Aircraft Co in Wichita, Kansas, historically associated with the 162 Skycatcher; CGS Aviation in Mulberry, Florida, with the Hawk Arrow II; Colyaer SL in Spain, offering the Freedom S100; and Composite Aeronautic Group SL in Zaragoza, Spain, with the Toxo SLSA.
Costruzioni Aeronautiche Tecnam S.p.A. in Capua, Italy, offers a wide range of models including the Astore and P92/Echo series, P2002 Sierra, P2004 Bravo, and P2008. Criquet Aviation in DeLand, Florida, produces the Storch FI-156. CubCrafters Inc. in Yakima, Washington, offers the Sport Cub and Carbon Cub models with various engine options. Czech Aircraft Works in Kunovice, Czech Republic, produces models like the CH 601 XL RTF and SportCruiser. Czech Sport Aircraft and Czech Sportplanes SRO also operate in Kunovice, offering SportCruiser and Dynamic WT9 models. Finally, Delta Trikes Aviation SARL in Montélimar, France, offers Voyageur II and other weight-shift-control models.
This diverse roster reflects the global nature of LSA manufacturing and the variety of product offerings available. Our research goes beyond mere enumeration. We analyze the competitive positioning of these firms, their strategic responses to regulatory changes, and their potential for market share expansion or consolidation. The report examines how companies are adapting their product lines, engine selections, and compliance strategies to maintain relevance and competitiveness in a market that is becoming increasingly performance-oriented.
Segmentation Dynamics and Value Creation Opportunities
While the aggregate market size and growth rate provide a macro-level view, strategic success often depends on a nuanced understanding of market segmentation. The LSA market is segmented across multiple dimensions, including geographic regions, aircraft types, and application areas. Each segment exhibits distinct growth characteristics, demand drivers, and competitive intensities.
For instance, certain regions demonstrate significantly higher concentration and revenue generation, reflecting established general aviation infrastructures, regulatory maturity, and higher disposable income levels. Other regions show emerging potential, driven by increasing aviation awareness, infrastructure development, and regulatory harmonization efforts. The full report provides a rigorous breakdown of these regional dynamics, identifying where opportunities for market penetration or partnership may be most viable.
Similarly, segmentation by aircraft type reveals preferences for different configurations, ranging from two-seat to four-seat models. The distribution of revenue across these types is not uniform and is subject to change as the MOSAIC rule potentially shifts demand toward higher-capacity aircraft. Understanding the current revenue contributions and growth trajectories of each type category allows manufacturers and investors to assess product portfolio alignment and future development priorities.
Application-based segmentation further illuminates how LSAs are being utilized. Personal recreation remains a dominant application, driven by the appeal of accessible flying and leisure travel. Flight training represents another critical segment, where LSAs are valued for their lower operating costs and suitability for initial pilot instruction. Commercial transport applications, while smaller in relative terms, offer specialized opportunities for niche operations such as aerial survey, patrol, or cargo delivery in remote areas. The interplay between these applications and the evolving regulatory environment creates distinct value propositions for different stakeholders. Our research delineates these application-specific trends, helping clients identify the most promising use cases and tailor their strategies accordingly.
Operational Safety and Regulatory Compliance as Strategic Assets
In the current LSA market environment, operational safety and regulatory compliance are not merely administrative requirements; they are strategic assets that influence customer confidence, insurance costs, and market reputation. The FAA's continued focus on safety monitoring is evident in reports such as the 2024 SLSA Continued Operational Safety (COS) Report, which documents trends in fatal and non-fatal accidents and incidents across SLSA classes. This report includes analysis by manufacturer fleet size and occurrence categories, providing valuable feedback loops for manufacturers and operators.
Furthermore, SLSA manufacturers are required to maintain a Partnership for Safety Plan (PSP) with the FAA to demonstrate continued compliance. This ongoing engagement with regulatory bodies ensures that safety remains a central pillar of the LSA ecosystem. The April 2026 SLSA Make/Model Directory highlights these requirements and specifies that only assigned Aviation Safety Inspectors (ASI) may issue special airworthiness certificates for new make/model combinations not appearing in the directory. These procedural details underscore the importance of maintaining rigorous compliance standards and building robust relationships with regulatory authorities.
Our market research integrates these safety and compliance dynamics into the broader market analysis. We evaluate how safety records and compliance reputations impact competitive positioning and market access. For potential entrants or existing manufacturers seeking to expand their fleet, understanding the nuances of the COS reporting framework, PSP requirements, and the certification process for new models is essential. The report provides actionable insights into navigating this regulatory landscape, mitigating risk, and leveraging safety performance as a differentiator.
Strategic Imperatives for 2026 Decision-Makers
As the market moves forward, several strategic imperatives emerge for stakeholders operating in the LSA sector. First, agility in response to regulatory change is paramount. The MOSAIC rule presents both opportunities and challenges, and companies must be prepared to adapt their product development cycles, certification strategies, and marketing messages to align with the new performance-based criteria. Early movers who can effectively navigate the transition to the July 2026 certification deadline may gain a competitive advantage.
Second, the fragmented nature of the competitive landscape suggests that differentiation through innovation, quality, and service will remain key success factors. With a wide array of manufacturers offering diverse models and engine configurations, customers have numerous choices. Companies must clearly articulate their value proposition, whether through advanced avionics integration, superior performance characteristics, lower total cost of ownership, or specialized support networks. The full report includes a competitor benchmarking analysis that helps identify white spaces and areas where differentiation can be most effective.
Third, understanding the demand drivers across different segments is critical for resource allocation. Investing in product lines or market expansion initiatives that align with high-growth segments or underserved applications can yield higher returns. The detailed segmentation analysis in our report enables clients to prioritize initiatives based on empirical data rather than assumptions.
Low Speed Vehicle Market
Finally, the importance of safety and compliance cannot be overstated. In an industry where trust is built on reliability and adherence to standards, a strong safety culture and transparent compliance practices are indispensable. The report highlights how leading companies are integrating safety into their operational DNA and how this contributes to long-term sustainability and brand equity.
Unlocking the Full Intelligence: Access the Complete Report
This article has provided a high-level overview of the key themes, market dynamics, and strategic considerations shaping the Light Sport Aircraft market in 2026. We have explored the steady growth trajectory, the transformative impact of the MOSAIC rule, the diverse competitive landscape, and the critical role of segmentation and compliance. However, this preview only scratches the surface of the actionable intelligence contained within our comprehensive market research study.
The full Light Sport Aircraft (LSA) Market report offers a depth of analysis that is essential for making informed, high-stakes decisions. It provides precise market size estimates for specific regions, detailed revenue breakdowns by aircraft type and application, and nuanced forecasts that account for the interplay of regulatory, economic, and technological factors. The report also includes in-depth profiles of key companies, an assessment of competitive strategies, and a thorough examination of the regulatory environment, including the latest FAA directives and their implications.
For executives, investors, and strategic planners, access to this level of detail is invaluable. It enables the formulation of data-driven strategies, the identification of high-potential opportunities, and the mitigation of risks associated with market volatility and regulatory complexity. We invite you to explore the complete findings of our research. Visit our website to download the full report and gain the comprehensive market intelligence needed to navigate the future of the LSA sector with confidence.
For detailed analysis of this topic, please visit the official page: Light Sport Aircraft (LSA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


