



PW Consulting: Reverse Transcriptase Market Hits $1,530M in 2025, Projects 6.69% CAGR to $2.4B by 2032

Strategic Intelligence for the Reverse Transcriptase Market: Navigating Growth and Consolidation Through 2032
The global reverse transcriptase market stands at a critical inflection point. As molecular biology techniques become increasingly central to pharmaceutical development, clinical diagnostics, and academic research, the enzymes that enable RNA-to-DNA conversion are no longer commodities but strategic assets. For executives, procurement leaders, and R&D directors operating in 2026, understanding the trajectory of this market is not merely an academic exercise; it is a prerequisite for informed capital allocation, partnership formation, and competitive positioning. PW Consulting's latest comprehensive study of the reverse transcriptase sector delivers precisely the analytical rigor required to navigate this evolving landscape.
Reverse Transcriptase Market
Macro Trajectory and Investment Context
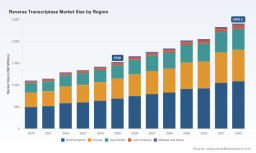
Historical revenue patterns indicate a sector that has consistently expanded, with global market size rising from approximately 1.1 billion USD in 2020 to an estimated 1.53 billion USD by 2025. This sustained momentum reflects broader shifts in life sciences funding, accelerated adoption of next-generation diagnostic platforms, and the persistent demand for high-fidelity enzymatic solutions across both developed and emerging markets. The forecast horizon through 2032 projects continued appreciation, with the market expected to surpass the 2.4 billion USD threshold by the end of the period. The compound annual growth rate of 6.69 percent underscores a mid-single-digit expansion profile that balances steady demand with selective premiumization in specialized applications.
For strategic planners, these figures translate into more than aggregate growth. They signal a market where volume expansion is increasingly coupled with value migration toward differentiated product lines, integrated workflow solutions, and regions experiencing rapid infrastructure modernization. The base year of 2025 and the forward-looking window through 2032 provide decision-makers with a sufficiently granular temporal framework to model capital deployment, capacity planning, and technology roadmap alignment.
Structural Segmentation and Demand Drivers
Type-Based Demand Dynamics
Reverse transcriptase demand is structured around distinct enzyme categories that serve different therapeutic, diagnostic, and research endpoints. A substantial portion of revenue continues to originate from HIV reverse transcriptase applications, driven by enduring needs in antiretroviral development, resistance profiling, and global public health initiatives. Hepatitis C virus reverse transcriptase and Hepatitis B reverse transcriptase segments contribute meaningful additional volume, reflecting sustained investment in viral characterization, vaccine research, and diagnostic assay standardization. A smaller but strategically important share is allocated to other reverse transcriptase variants that serve specialized laboratory workflows and emerging biotechnology pipelines.
The relative weighting of these categories is not static. Shifts in funding priorities, regulatory approvals, and the emergence of novel therapeutic modalities continuously reshape which enzyme applications command the greatest commercial attention. Understanding the interplay between these segments requires more than headline figures; it demands an appreciation of how procurement cycles, clinical trial pipelines, and academic grant structures influence long-term demand elasticity.
Application Channels and Workflow Integration
The application landscape reveals how reverse transcriptase enzymes are embedded into downstream workflows. Molecular diagnostics remains a dominant channel, underpinned by the expansion of point-of-care testing, centralized laboratory automation, and the growing reliance on nucleic acid amplification techniques. Viral load analysis constitutes a significant secondary pathway, essential for monitoring treatment efficacy and disease progression in chronic viral conditions. Gene expression analysis and DNA sequencing applications, while representing smaller revenue shares, are critical to high-value research programs, transcriptomics, and advanced genomic characterization. RNA analysis, though currently a niche application, carries strategic significance as laboratories increasingly focus on transcriptome profiling and non-coding RNA discovery.
The strategic implication for 2026 and beyond is clear: procurement decisions are no longer driven solely by unit pricing. Laboratories and diagnostic providers evaluate enzyme performance in the context of workflow compatibility, batch-to-batch consistency, scalability, and total cost of ownership across integrated platforms. Suppliers that align their reverse transcriptase offerings with these broader workflow priorities are positioned to capture premium positioning and longer-term contract commitments.
Competitive Landscape and Strategic Positioning
The reverse transcriptase market exhibits a moderately concentrated structure, with a small group of established life sciences and diagnostics companies commanding the majority of revenue. The top three players collectively represent a significant share of overall market activity, while the top five extend that concentration further, reflecting the high barriers associated with quality certification, global distribution networks, regulatory compliance, and sustained R&D investment. In such an environment, competitive differentiation depends less on broad categorization and more on the precision of product offerings, the strength of technical support, and the ability to integrate enzymatic solutions into larger instrument and assay ecosystems.
Several core companies anchor this competitive landscape. New England Biolabs, headquartered in Ipswich, Massachusetts, maintains a strong reputation for specialized enzyme portfolios and is recognized for its focus on tailored reverse transcriptase offerings that serve both research and applied molecular biology workflows. Thermo Fisher Scientific, based in Waltham, Massachusetts, leverages its expansive instrumentation and consumables ecosystem to position reverse transcriptase products within integrated diagnostic and laboratory automation platforms, appealing to large-scale clinical and industrial laboratories. QIAGEN, located in Hilden, Germany, brings deep expertise in sample preparation and molecular testing, aligning its reverse transcriptase capabilities with standardized diagnostic workflows and global laboratory operations. Merck KGaA, with its headquarters in Darmstadt, Germany, operates across life science research and industrial segments, deploying reverse transcriptase solutions within broader reagent and bioprocessing portfolios. Promega Corporation, in Madison, Wisconsin, is known for its emphasis on reliable enzymatic reagents and focused product development, catering to both academic and commercial research environments. Takarabio, based in Otsu, Japan, delivers specialized reverse transcriptase products that serve Asian and global research markets, with particular attention to performance characteristics relevant to high-precision applications.
The competitive calculus among these firms is increasingly shaped by their ability to offer not just an enzyme, but a validated solution. Product performance, supply chain resilience, regional regulatory alignment, and the depth of customer technical engagement all influence purchasing decisions at the organizational level. In a market where concentration is significant but innovation remains continuous, companies that can demonstrate measurable workflow advantages and maintain consistent quality standards are better positioned to defend and expand their share.
Market Dynamics and Industry Context
Several macro-level dynamics inform the reverse transcriptase market's trajectory. The broader life sciences sector continues to benefit from sustained investment in molecular diagnostics, infectious disease research, and precision medicine initiatives. Public health priorities, particularly those related to chronic viral conditions, have reinforced the importance of reliable enzymatic tools in both clinical and surveillance contexts. Simultaneously, the research community's expanding focus on transcriptomics, viral evolution, and therapeutic discovery sustains demand for high-quality reverse transcriptase enzymes across academic, governmental, and commercial laboratories.
Supply chain considerations also play an increasingly prominent role. As laboratories seek to reduce operational risk and ensure uninterrupted access to critical reagents, vendor reliability, regional sourcing options, and logistical stability have become important evaluation criteria. This trend favors suppliers that can combine technical performance with dependable fulfillment and localized support structures. In addition, the growing standardization of diagnostic workflows and the push toward regulatory conformity in certain application areas create both opportunities and compliance considerations for manufacturers and distributors alike.
For enterprises operating in 2026, these dynamics necessitate a strategic posture that balances cost efficiency with resilience. Short-term procurement optimization must be weighed against the long-term implications of supplier dependence, workflow integration, and the pace of technological change. The most effective strategies will be those that incorporate market intelligence at the level of product trends, regional demand shifts, and competitive capability mapping rather than relying solely on historical purchasing patterns.
Inside the Report: Analytical Depth and Decision-Ready Frameworks
PW Consulting's reverse transcriptase market study is structured to deliver actionable intelligence rather than static observation. The report provides a detailed mapping of revenue trends across the forecast period, contextualized within historical performance to highlight growth inflection points and structural shifts. Segmentation analysis examines how demand is distributed across enzyme types and application channels, enabling readers to identify where commercial emphasis is strengthening and which workflows are driving sustained procurement activity.
The competitive assessment component profiles the strategic posture of leading suppliers, with attention to their market positioning, product focus, and the operational advantages that support their standing. By analyzing the concentration structure and the capabilities of incumbent players, the report provides a framework for evaluating partnership opportunities, competitive threats, and potential whitespace for differentiated offerings.
Real-Time PCR Machines Market
Geographic analysis within the report examines regional market dynamics without reducing the picture to superficial aggregates. It explores the factors that influence demand intensity, including laboratory infrastructure development, diagnostic program expansion, and the maturity of local life sciences ecosystems. This regional lens helps organizations understand where growth is likely to be volume-driven versus value-driven, and where market entry or expansion may require tailored technical or commercial approaches.
Operational and strategic readers will also benefit from the report's synthesis of demand-side considerations, including the influence of workflow integration, quality expectations, and supply chain reliability on purchasing behavior. The study connects these operational realities to broader market trends, offering a coherent basis for scenario planning, capacity forecasting, and investment prioritization. Throughout, the analysis is designed to support executive discussion, cross-functional alignment, and evidence-based decision-making rather than to function as a disconnected data repository.
Why This Study Matters for 2026 Decision-Making
As organizations plan their initiatives for 2026 and look beyond to the remainder of the decade, the reverse transcriptase market presents both opportunity and complexity. A mid-single-digit growth trajectory suggests that the sector will continue to expand, but the distribution of that growth across enzyme categories, application workflows, and regions is uneven and subject to shifting priorities. Market concentration among established players raises the importance of understanding competitive moves, while evolving laboratory expectations around reliability, integration, and total cost of ownership reshape the criteria by which suppliers are judged.
PW Consulting's study is built to address these realities with precision. It translates macro-level market data into strategic context, connects segmentation patterns to operational decision-making, and frames the competitive landscape in terms of capability, positioning, and long-term relevance. For executives evaluating product portfolio direction, procurement strategy, partnership options, or regional expansion, the report supplies a foundation of structured insight that can be applied directly to planning processes.
The full depth of the analysis, including detailed segmentation interpretations, competitive positioning assessments, and forward-looking scenario considerations, is available in the complete report. Readers seeking to translate market intelligence into actionable strategy will find that the study goes beyond headline figures to provide the analytical clarity required for confident decision-making throughout the 2026 to 2032 horizon.
For detailed analysis of this topic, please visit the official page: Reverse Transcriptase Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


