



PW Consulting: FeSi Powder Market Hits $1,554.12M in 2025, Projects 5.2% CAGR to $2,193.59M

Strategic Horizons: Navigating the Ferrosilicon Powder Market in 2026 and Beyond
The global ferrosilicon powder market stands at a critical inflection point. As industries ranging from steelmaking to mineral processing demand higher precision and regulatory compliance, understanding the trajectory of this specialized materials sector is no longer optional—it is a strategic imperative. PW Consulting's latest comprehensive market research offers a definitive guide for stakeholders preparing to navigate the complexities of the 2026-2032 forecast period.
Iron Powder Market
This analysis serves as a strategic primer, outlining the macroeconomic currents, competitive tensions, and regulatory shifts that will define the landscape. For decision-makers seeking granular data to inform capacity planning, supply chain optimization, or market entry strategies, this research provides the foundational intelligence required to act with confidence.
Market Trajectory and Growth Dynamics
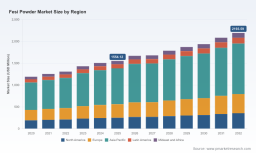
The historical performance of the ferrosilicon powder market demonstrates a consistent upward trajectory, reflecting the material's entrenched role in modern industrial applications. Between 2020 and 2025, the market expanded from approximately 1,190.55 million USD to 1,554.12 million USD, showcasing resilience even during periods of global economic volatility. This growth stabilization sets a robust baseline for the forecast period.
Looking ahead to 2032, the market is projected to reach a valuation of 2,193.59 million USD. This expansion is underpinned by a Compound Annual Growth Rate (CAGR) of 5.2% over the forecast period. Such growth indicates a healthy demand environment, though it also suggests that early movers who secure supply chain advantages will capture disproportionate value. The acceleration is not uniform; it is being reshaped by geographical production shifts and evolving technical requirements in downstream sectors.
For corporate strategists, the key takeaway lies beyond the headline numbers. The growth trajectory signals sustained demand but also highlights the necessity of efficiency. As volumes increase, margins depend heavily on navigating input cost fluctuations and regulatory hurdles, which were notably intense in late 2025.
Segmentation and Application Nuances
While the aggregate market size provides a macro view, the real strategic opportunities lie in understanding the differential growth rates across product types and application verticals. The market is broadly categorized by production technology and end-use industry, each facing distinct demand drivers and technical barriers.
In terms of product type, the market is dominated by atomized ferrosilicon powder, which continues to hold the largest revenue share due to its widespread application in dense media separation and high-precision metallurgical processes. Milled ferrosilicon powder and other specialized types constitute significant but smaller segments, often catering to niche requirements where particle size distribution and purity are critical differentiators. The choice between atomized and milled forms often depends on the specific density and flow characteristics required by the downstream application, making technical specification intelligence vital for procurement teams.
Application-wise, the metallurgy sector remains the primary consumption engine. This includes deoxidation and inoculation processes in steelmaking, where consistent powder quality directly impacts final product integrity. The machinery industry and other specialized sectors follow, utilizing ferrosilicon powder for alloy production and specific industrial manufacturing processes. The interdependence between steel production cycles and ferrosilicon powder demand means that stakeholders must monitor broader industrial metal cycles closely.
PW Consulting's report delves deep into these segmentation splits, offering detailed revenue analysis and volume estimates that are essential for identifying high-growth niches. However, understanding the specific value contributions of each region or application segment requires access to the full dataset, as these figures fluctuate based on real-time supply chain adjustments and regional policy interventions.
Competitive Landscape and Strategic Positioning
The ferrosilicon powder market is characterized by a moderately concentrated competitive structure. With the top three players holding approximately 32.5% of the market share and the top five controlling around 38.7%, the landscape offers room for both established giants and agile regional specialists to compete. This concentration level suggests that while scale provides advantages in distribution and cost management, specialized technical capability and regional proximity remain significant differentiators.
Several key companies define the current competitive boundaries. DMS Powders, based in South Africa, stands out as a leading producer specifically focused on milled and atomized ferrosilicon powders for dense media separation applications in mining. Their product grades, ranging from coarse to fine cyclone specifications, highlight the technical granularity required in the mining sector. Meanwhile, European industrial giants like Elkem ASA and Finnfjord AS maintain strong footholds in metallurgical applications, producing ferrosilicon powders for deoxidation and inoculants. Elkem's recent operational decisions reflect the broader industry caution; in October 2025, the company partially curtailed production at its Rana plant in Norway and its Iceland facility, citing market conditions and the impact of EU safeguard measures.
Ferroglobe PLC and OM Holdings Ltd represent significant cross-regional capabilities. Ferroglobe, headquartered in the United Kingdom, supplies powders for steelmaking deoxidation and foundry uses, leveraging integrated production networks. OM Holdings, based in Singapore, serves as a key supplier for steel and alloy production, bridging Asian demand with global supply. On the high-purity flank, Stanford Advanced Materials in the United States supplies high-purity Ferro Silicon Powder with purity levels reaching 99% for specialized deoxidation needs, targeting segments where impurity control is paramount.
In Asia, particularly China, manufacturers like Anyang Lishi Industrial Co., Ltd. and Zhenan Metallurgy Co., Ltd. play crucial roles. Anyang Lishi is a notable manufacturer and exporter of both atomized and milled ferrosilicon powders for metallurgical and electrode applications. Zhenan Metallurgy focuses on low-aluminum ferrosilicon powder, catering to specific steelmaking requirements where aluminum content must be strictly controlled. The strategic positioning of these Asian players is critical, given the region's volume dominance in global supply.
Understanding the specific capacity, export capabilities, and proprietary grade portfolios of these competitors is essential for any market entry or expansion strategy. Our full report provides detailed competitor profiling, including SWOT analyses and strategic moves that are not publicly aggregated in general market summaries.
Regulatory Shifts and Industry Dynamics
The operating environment for ferrosilicon powder is undergoing significant transformation due to regulatory interventions and raw material dynamics. These factors introduce both risks and opportunities that must be modeled into any forward-looking strategy.
One of the most impactful recent developments occurred in November 2025, when the European Commission imposed safeguard measures on ferro-silicon imports, including powder forms. The EU established three-year tariff-rate quotas and implemented out-of-quota variable duties based on a price threshold of 2,408 USD per ton. This move is designed to protect local producers but introduces immediate complexity for importers and downstream users in Europe. The ramifications were felt quickly; Elkem ASA's production curtailment in late 2025 was partially attributed to the uncertainty generated by these safeguard measures.
Simultaneously, regulatory scrutiny is increasing in the supply source regions. Starting January 2026, China introduced new export license rules for ferrosilicon. These regulations require detailed specifications for exports, including particle size for FeSi products. Furthermore, batch-specific checks are now mandated for aluminum, calcium, phosphorus, and particle size for grades with 75% Si or higher. For global buyers, this means supply chain verification processes must be tightened, and lead times may be affected by administrative compliance. Anyang Lishi Industrial Co., Ltd. highlighted these changes in December 2025, signaling a shift toward stricter trade governance.
Infrastructure developments also signal shifting supply centers. In November 2025, Kazakhstan launched a new ferroalloys plant in Pavlodar. This facility, representing a 177 million USD investment, is designed to produce high-grade FeSi75 at an annual capacity of 240,000 tons for export. This expansion adds new volume to the global market and potentially alters trade flows, particularly for buyers seeking alternatives to traditional supply hubs.
On the technical application side, the fundamental utility of the material continues to drive demand stability. For instance, in dense media separation (DMS) applications within mining, powdered ferrosilicon is mixed with water to form a slurry used for density adjustment and mineral separation. This specific application requirement ensures that demand from the mining sector remains correlated with mineral processing activity, which varies by commodity cycles.
Strategic Implications for 2026 Decision Making
For corporate leaders, the convergence of these factors creates a complex operational environment. The 5.2% CAGR suggests that the market is growing faster than general industrial inflation, implying real demand expansion. However, the regulatory barriers in key markets like Europe and the stricter export controls from China mean that supply security is becoming as important as price competitiveness.
Companies must now evaluate their sourcing strategies with a multi-regional lens. Relying on a single supply corridor introduces vulnerability to tariff shocks and export licensing delays. The entry of new capacity in Central Asia offers diversification potential, but requires thorough due diligence on quality consistency and logistics reliability. Furthermore, the distinction between atomized and milled powders is not merely technical; it affects compatibility with existing processing equipment and compliance with specific metallurgical standards.
Procurement teams need to factor in the cost implications of the EU safeguard measures. For European manufacturers, the tariff structure may influence decisions on whether to source domestically or import from outside quota allocations. For exporters, understanding the price threshold mechanisms is critical to maintaining margin integrity. Meanwhile, the focus on purity and particle size specifications, driven by both regulatory checks and end-user performance requirements, elevates the importance of supplier technical audits.
PW Consulting's full market research report goes beyond these high-level dynamics to provide the specific quantitative forecasting and segmentation data necessary to model these scenarios. We analyze historical consumption patterns from 2020 to 2025, benchmark them against the forecast period through 2032, and isolate the growth contributions of each segment. This level of detail allows stakeholders to stress-test their strategies against various regulatory and demand outcomes.
Conclusion: The Value of Granular Intelligence
The ferrosilicon powder market offers compelling growth opportunities, but realizing them requires more than a top-line growth rate. It demands a nuanced understanding of who is producing what, where trade barriers are being erected, and how technical specifications are evolving to meet downstream needs. The competitive landscape is stable yet reactive, with major players adjusting production and trade strategies in response to the new regulatory normal.
Fesi Powder Market
As 2026 unfolds, the ability to access precise market intelligence will differentiate between organizations that merely react to market shifts and those that proactively shape their position within them. PW Consulting's in-depth analysis provides the roadmap for this navigation, offering the data density and strategic context required for high-stakes decision making.
To access the complete dataset, including detailed regional revenue breakdowns, specific application volume estimates, and comprehensive competitor strategic profiles, please refer to the full PW Consulting Fesi Powder Market Research Report. The insights contained within are designed to empower your next strategic move with precision and confidence.
For detailed analysis of this topic, please visit the official page: Fesi Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


