



PW Consulting: 2-in-1 Laptops Revenue to Hit $5,357M by 2032, 7% CAGR

Strategic Intelligence for the 2-in-1 Laptop Market: Navigating Growth, Disruption, and Competitive Realignment in 2026
The 2-in-1 laptop category has evolved from a niche premium segment into a foundational hardware architecture for modern computing. As form factors continue to blur the boundaries between productivity, creativity, and mobile workflows, enterprise buyers, channel partners, and OEM strategists require more than surface-level trend summaries. They need structured, forward-looking intelligence that connects macroeconomic trajectories, component-level disruptions, and competitive maneuvering into actionable decision frameworks. PW Consulting's latest market research on the 2-in-1 Laptops Market is built precisely for that purpose: to convert complex industry signals into clear strategic direction for 2026 and beyond.
The Strategic Imperative of a Data-Backed Market View
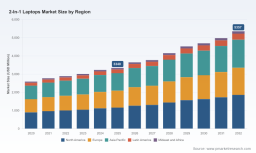
Over the past half-decade, the category has demonstrated consistent expansion, moving from a baseline of approximately 2,590 million USD in 2020 to an estimated 3,340 million USD in 2025. That progression reflects more than incremental demand; it signals a structural shift in how organizations and individual users evaluate device versatility, input flexibility, and display interactivity. The forecast window extending through 2032 projects a compound annual growth rate of 7.0 percent, with market valuation anticipated to reach roughly 5,357 million USD by the end of the period. These figures are not abstract statistics. They represent the scale of capital allocation, product roadmap prioritization, and regional capacity planning that stakeholders must address in the current planning cycle.
For executives evaluating portfolio investments, inventory commitments, or channel strategies, the key question is no longer whether the 2-in-1 category will continue to expand, but how growth will be distributed across architectures, use cases, and supply ecosystems. A 7.0 percent CAGR in a mature hardware segment suggests sustained transition rather than speculative hype. It implies that convertible and detachable designs are becoming default considerations in specific procurement segments, while also rewarding manufacturers that can align processor roadmaps, display technologies, and service models with evolving user expectations. PW Consulting's research translates this trajectory into a structured lens for scenario planning, allowing decision-makers to test assumptions against validated historical patterns and forward projections.
Report Architecture: From Macro Trajectory to Operational Readiness
The research is organized to support both strategic oversight and tactical execution. Rather than presenting a single narrative arc, the report decomposes the market into analyzable layers that reflect how real organizations make hardware decisions. The foundation rests on historical tracking from 2020 through the 2025 base year, followed by a forecast horizon spanning 2026 to 2032. This dual structure enables readers to benchmark recent performance, identify inflection points, and calibrate medium-term expectations with confidence.
Beyond top-line sizing, the report examines the architecture split between convertible and detachable designs, mapping how each form factor addresses distinct usage profiles, thermal constraints, and input preferences. It also assesses demand patterns across consumer and commercial environments, highlighting where procurement cycles, total cost of ownership calculations, and device longevity requirements diverge. Regional coverage is integrated as a strategic layer rather than a static table, allowing readers to understand how localized purchasing behavior, distribution maturity, and policy environments shape deployment velocity.
The analytical framework further incorporates competitive positioning, supply chain sensitivity, and technology adoption timing. Readers will find structured evaluations of product line breadth, feature differentiation, and go-to-market emphasis across leading manufacturers. Equally important, the report connects these commercial signals to upstream realities such as display and touch integration, semiconductor sourcing pressures, and tariff-driven cost dynamics. The objective is to give strategists a complete operating picture: what is selling, why it is selling, where production risk is accumulating, and which capabilities are most likely to determine market share in the next planning cycle.
Competitive Landscape: Architectural Diversification and AI-Enabled Positioning
The 2-in-1 laptop arena is defined by a concentrated group of established OEMs that are competing simultaneously on hardware versatility, display quality, processor integration, and software-enabled productivity. Market concentration remains high, with the top firms collectively commanding a substantial share of category revenue. This concentration does not imply stagnation. Instead, it reflects an intense competition over micro-differentiation: hinge engineering, touch and pen responsiveness, battery endurance, screen resolution and color accuracy, and increasingly, the integration of AI-centric processing capabilities.
Dell continues to maintain a broad convertible portfolio across mainstream and performance-oriented segments, pairing touch and pen-ready configurations with current-generation Intel Core Ultra platforms. Its lineup illustrates a pragmatic approach to the category: multiple screen sizes and price tiers, consistent enterprise serviceability, and clear positioning for users who need convertible flexibility without abandoning traditional laptop ergonomics.
HP has emphasized the intersection of manageability, display quality, and AI features, particularly in business-facing convertible lines. By combining OLED touchscreen options with AI-forward branding and enterprise-grade chassis design, HP targets procurement teams that want device versatility alongside security, manageability, and visual quality for presentation-heavy or content-review workflows.
ASUS has pursued a more segmented strategy, spanning creative-oriented convertibles, lightweight gaming-capable flip systems, business flip models, and Chromebook options. The breadth of its portfolio reflects a deliberate effort to capture different purchase motivations under one roof, from color-accurate displays for professional creators to 360-degree hinge designs for education and general productivity environments.
2-In-1 Laptops Market
Acer's presence in the category highlights value-conscious engineering and, more recently, a focus on next-generation processor platforms. Its convertible offerings span budget-friendly spin designs, business travel models, and AI-branded flip systems. This range demonstrates how aggressively the category is being extended into multiple price and performance bands, making 2-in-1 configurations accessible to a wider set of buyers.
Lenovo has leaned into the convergence of design refinement, OLED touchscreen adoption, and AI PC narratives. Its convertible and detachable-oriented lines target both premium consumer segments and commercial buyers seeking balanced ergonomics and modern input experiences. The emphasis on Copilot+ features and OLED implementation shows how manufacturers are using software and display quality as leverage in a category where hardware form factors are increasingly familiar to consumers.
Samsung has positioned its Galaxy Book 360 lineup around high-end display technology and integrated ecosystem appeal. With Super AMOLED touchscreens and Intel Core Ultra platforms, these devices reinforce the idea that 2-in-1 devices can serve as premium productivity and media tools rather than merely compromise form factors. The strategy aligns with a broader push toward visually rich, AI-capable devices that perform well in both tablet and laptop modes.
Microsoft remains a defining presence through its Surface line, particularly with detachable-oriented devices powered by advanced silicon options. Its high-end detachable offerings underscore the enduring relevance of detachables in scenarios where tablet-first usage, portability, and pen-based interaction take priority. At the same time, the broader competitive conversation shows that detachable and convertible designs are not interchangeable; each serves distinct workflow assumptions and purchase criteria.
Taken together, these players reveal a market where success depends less on announcing a new form factor and more on executing consistently across display quality, battery performance, thermal management, support ecosystems, and supply reliability. PW Consulting's research evaluates these competitive signals in a way that helps stakeholders identify where differentiation is genuine and where product narratives risk blending into commodity positioning.
Industry Dynamics: Supply Chain Realignment, Component Innovation, and Tariff-Driven Economics
The category's growth trajectory is unfolding against a backdrop of meaningful operational friction. Recent sector analysis points to tariff-related pressures and export restrictions affecting advanced semiconductor components, prompting manufacturers to diversify sourcing and accelerate localization strategies. These developments are not incremental conveniences; they reshape cost structures, lead-time expectations, and regional production planning. For 2-in-1 laptops, which depend on integrated display, touch, and processing ecosystems, any disruption in component availability can cascade quickly into product timing and margin performance.
Tariff actions and retaliatory measures from trade partners have added further complexity by raising production costs for consumer goods, including 2-in-1 laptops, with estimates indicating cost increases in a broad double-digit range. Alongside that, supply chain disruptions have become a recurring risk factor rather than an occasional exception. Semiconductor and display sourcing remain especially sensitive, and the U.S. General Services Administration has noted that such disruptions have translated into longer lead times and higher costs for critical laptop components. In a category where hinge design, touch integration, and thin-chassis thermal constraints already demand precise component coordination, these pressures can influence everything from bill-of-material planning to channel inventory strategy.
Gaming Laptop Market
Despite these headwinds, component-level innovation continues to open differentiation opportunities. Himax Technologies' move into mass production of OLED Touch IC for IT applications is a notable example. By enhancing integrated display and touch performance with industry-leading characteristics, such component advances can improve the user experience that manufacturers rely on to justify premium pricing and reinforce product identity. At the device level, recent introductions such as AI-focused convertible systems powered by next-generation Snapdragon platforms illustrate how manufacturers are translating NPU capability, extended battery life, and multi-monitor support into tangible value propositions. These product developments matter because they show that the category is still evolving in ways that go beyond hinge rotation or screen size alone.
For strategic planners, the implication is clear: market expansion is real, but it is being filtered through a more complicated operating environment. Revenue opportunity must be weighed against sourcing resilience, tariff exposure, logistics risk, and the cost of localizing or dual-sourcing critical inputs. PW Consulting's report addresses these tensions directly, giving readers a structured way to evaluate where demand is durable and where execution risk may erode expected returns.
Why This Research Matters for 2026 Decision-Making
In 2026, hardware strategy is no longer about forecasting a single growth curve. It is about aligning product mix, channel behavior, procurement expectations, and supply chain options within a market that is simultaneously expanding and fragmenting in its competitive logic. The 2-in-1 laptop category exemplifies this challenge. It offers clear long-term demand support, yet it also requires careful interpretation of form-factor preferences, commercial versus consumer buying patterns, regional purchasing conditions, and component-level constraints.
This research is designed to reduce uncertainty at exactly those decision points. It provides a disciplined framework for interpreting historical performance, evaluating forward projections, and understanding how competitive and operational variables interact. Readers gain clarity on where the market is heading in aggregate, how major players are positioning themselves, and which structural pressures are most likely to influence cost, availability, and differentiation in the near term. Just as importantly, the report is built to support internal discussion: it gives product leaders, procurement teams, channel strategists, and investors a common reference point for debating scenario outcomes and prioritizing investments.
The full study goes further than the overview presented here. It contains the detailed segmentation logic, competitive profiles, regional interpretations, and operational risk analysis needed to convert high-level market direction into executable plans. To access the complete dataset, segmentation breakdowns, and strategic recommendations underpinning this analysis, visit the source report page and obtain the full intelligence package. In a market where timing, positioning, and supply resilience determine competitive outcomes, that deeper view is the difference between reactive planning and confident strategic action.
For detailed analysis of this topic, please visit the official page: 2-In-1 Laptops Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


