



PW Consulting: Coal Tar Pitch Market to Hit $3,044.1 Million by 2032, 4.85% CAGR

Navigating the Carbon Binders Landscape: Strategic Imperatives for the Coal Tar Pitch Market Through 2032
The global coal tar pitch market stands at a critical inflection point. As foundational carbon binders underpin both primary aluminum production and advanced graphite manufacturing, industry participants must reconcile steady demand growth with tightening environmental regulations and evolving feedstock dynamics. Our latest research evaluates the market across a comprehensive 2026 through 2032 forecast window, building on a rigorously validated historical baseline spanning 2020 to 2025. This analysis is designed to equip procurement leaders, strategy executives, and investment committees with the structural clarity required to allocate capital, secure supply corridors, and align product portfolios with long-term industrial trajectories.
Over the historical period, revenue patterns reflected a combination of cyclical demand recovery, capacity rationalization in mature regions, and gradual migration toward higher-performance grades. The market advanced from a baseline of 1,765.2 million USD in 2020 to 2,185.5 million USD in 2025, with the trajectory demonstrating both resilience and episodic volatility driven by downstream construction cycles and metallurgical output adjustments. Looking forward, the forecast horizon projects sustained expansion, positioning total market revenue near 3,044.1 million USD by 2032. This growth is anchored by a compound annual growth rate of 4.85 percent, signaling a mature yet persistently expanding addressable market rather than a speculative surge. For corporate planners, this trajectory underscores the importance of modeling demandelasticity against macro industrial indicators, rather than relying on static volume assumptions.
Market Framework and Structural Segmentation
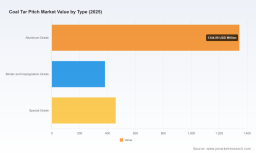
A rigorous understanding of coal tar pitch requires disaggregating the market across both product architecture and end-use demand profiles. The report maps the landscape across multiple type categories, capturing the distinct operational requirements that separate aluminum-grade binders from impregnation and specialty variants. Aluminum-grade pitch continues to represent the dominant share of revenue, reflecting its indispensable role in carbon anode formulation for primary smelting operations. Binder and impregnation grades serve a more specialized set of downstream applications, where softening points, coking values, and rheological characteristics dictate procurement specifications. Special-grade formulations address niche performance thresholds in advanced carbon materials and refractory systems, creating a higher-margin yet technically demanding segment for producers with differentiated processing capabilities.
Coal Tar Pitch For Graphite Electrodes Market
Demand concentration across applications follows a similarly hierarchical pattern. Aluminum smelting remains the foundational consumption pillar, while graphite electrode manufacturing sustains a substantial secondary channel tied to electric-arc furnace steelmaking and industrial carbon processing. Additional application channels, including roofing formulations and specialty industrial uses, provide supplementary revenue streams that help balance cyclical volatility in the core metallurgical segments. The report examines how these application pathways interact with regional processing capacity, logistics constraints, and customer specification requirements, enabling readers to identify where supply-demand balance is most likely to tighten or loosen over the forecast period.
Regional analysis in the study is structured to highlight where manufacturing footprints, trade flows, and regulatory environments shape competitive positioning. The market is not uniformly distributed; instead, it concentrates around established carbon-processing clusters and emerging refining hubs that can offer both scale and grade flexibility. The research details how regional pricing differentials, freight exposure, and local compliance requirements influence buyer-seller dynamics, helping strategists evaluate which geographies present durable advantages and which are more susceptible to regulatory friction or feedstock disruption.
Competitive Landscape and Enterprise Positioning
The coal tar pitch sector remains moderately concentrated, with established producers leveraging integrated distillation assets, long-term customer relationships, and technical service capabilities to defend market positions. Our analysis identifies the core enterprise cohort shaping competitive dynamics, including Koppers Holdings Inc., Rain Carbon Inc., Himadri Speciality Chemical Ltd., Deza, a.s., and Shree Shyam Chemicals. Each occupies a distinct strategic niche shaped by feedstock access, geographic footprint, and grade specialization.
Coal Tar Pitch Market
Koppers Holdings Inc., headquartered in Pittsburgh, Pennsylvania, operates as an integrated producer of carbon pitch derived from coal tar distillation, with primary offerings focused on binding agents for carbon anodes serving aluminum smelters and for graphite electrodes used by electric-arc furnace steel producers. Rain Carbon Inc., based in Stamford, Connecticut, has established itself as a global leader in coal tar and petroleum distillation, manufacturing coal tar pitch with varying softening points for carbon anodes, graphite electrodes, specialty graphite, and refractory materials. Himadri Speciality Chemical Ltd., operating from Kolkata, India, stands out as a vertically integrated producer with annual pitch capacity exceeding 600,000 metric tons, offering coal tar pitch grades for aluminum, graphite electrode, and carbon black sectors, including liquid and export variants. Deza, a.s., in the Czech Republic, produces coal tar pitch and related distillation products, supplying binder-grade and impregnating grades for carbon and specialty applications. Shree Shyam Chemicals, based in Bhilai, Chhattisgarh, manufactures coal tar pitch, coal tar, and related chemicals, serving industrial-grade requirements across aluminum, graphite, chemical, and pharmaceutical sectors.
Recent Developments Shaping Supply and Corridor Strategy
Beyond structural positioning, the report tracks recent operational moves that reveal where capital is flowing and how supply arrangements are evolving. In January 2025, Rain Carbon Inc. announced a new coal tar distillation and pitch processing facility in APSEZ, Anakapalli, Andhra Pradesh, India. The initial phase targets 50,000 metric tons per year and addresses graphite, battery, and aluminum markets, with further expansion planned, signaling a deliberate push to diversify processing geography and capture demand growth in South Asia. In November 2025, Epsilon Carbon Private Limited signed a non-binding MoU with Aluminium Bahrain for the long-term supply of liquid coal tar pitch, aimed at supporting aluminum smelting demand and strengthening export security for a key downstream customer. In December 2025, Himadri Speciality Chemical Ltd. executed its first-ever liquid coal tar pitch export of 3,600 tonnes to the Middle East from the New Mangalore Port terminal, establishing a new supply corridor and demonstrating the increasing importance of logistics-enabled grade differentiation.
These developments are not isolated events. Collectively, they point to a market in which supply reliability, grade customization, and corridor diversification are becoming as strategically consequential as raw production volume. The report examines how such moves reshape competitive pressure, influence customer negotiation leverage, and alter regional import-dependency profiles for buyers seeking to de-risk procurement.
Regulatory Dynamics and the Compliance Premium
Regulatory scrutiny represents one of the most consequential variables for coal tar pitch strategy, particularly where polycyclic aromatic hydrocarbon exposure intersects with pavement applications, industrial emissions standards, and chemical handling requirements. The analysis incorporates multiple regulatory signals that are reshaping demand quality and compliance economics. Minnesota prohibits the sale and use of coal tar sealant products containing coal tar, coal tar pitch volatiles, or CAS 65996-93-2/65996-89-6 on asphalt-paved surfaces, effective January 1, 2014. New York State has proposed legislation, Senate Bill 2025-S3179A, to tighten the PAH limit in the state's coal tar ban for pavement products. Under the EU REACH framework and related directives, strict PAH controls apply to coal tar pitch production and use, with compliance costs rising for legacy grades. Tightening PAH emission and wastewater norms in Canada and New York State continue to drive compliance-driven capacity considerations and low-PAH grade development.
These regulatory threads matter because they create a structural divergence between commodity-grade volumes and specification-driven demand. As jurisdictions tighten limits on certain applications and emissions profiles, producers and buyers alike must navigate higher compliance burdens, reformulation requirements, and potential substitution pressure in affected end-use channels. The report assesses how these dynamics influence grade architecture, regional demand elasticity, and the relative attractiveness of processing investments that can accommodate tighter specifications without sacrificing cost competitiveness.
Feedstock Volatility and Industrial Demand Shifts
In addition to regulation, market participants must contend with raw material uncertainty. Coal tar feedstock volatility and shifts toward electric-arc furnace steel production continue to constrain coal tar availability for pitch distillation. This constraint is significant because it links the coal tar pitch market not only to aluminum and graphite demand, but also to broader metallurgical technology transitions and upstream coke and tar supply conditions. Where tar availability tightens, grade allocation, pricing behavior, and customer qualification timelines can all become more volatile, making supply-chain visibility and flexible contracting models increasingly valuable. The study evaluates how these pressures interact with regional availability, refining capacity utilization, and downstream qualification cycles, helping stakeholders anticipate where bottlenecks may emerge and which procurement strategies are best suited to mitigate them.
What the Full Study Delivers
This executive overview highlights the strategic contours of the coal tar pitch market, but the full research provides the operational depth that decision-makers need to convert insight into action. Our report delivers a comprehensive market sizing and forecasting framework covering historical performance and forward projections through 2032. It includes detailed segmentation analysis by type and application, together with regional evaluation that situates demand growth within local regulatory and logistical realities. The study maps the competitive landscape across key producers, examining capacity structures, product orientation, and recent developments that signal changing market power. It also assesses the regulatory and raw-material environment shaping compliance costs, feedstock constraints, and demand quality.
For executives responsible for procurement, production planning, or market entry assessments, the research is structured to answer practical questions: which grade families offer the most durable growth under tightening compliance regimes, where regional demand expansion is likely to be most consistent, how supply corridor development may affect import dependency, and what operational factors distinguish resilient producers in a concentrated market. The analysis avoids superficial generalizations in favor of scenario-aware interpretation, allowing readers to integrate findings into internal forecasting models, sourcing strategies, and investment evaluations.
Why This Research Matters for 2026 Decision-Making
The 2026 planning cycle is unlikely to resolve into a single dominant trend. Instead, leaders will need to manage multiple overlapping forces: steady structural demand growth, a moderately concentrated producer base, regulatory tightening across key jurisdictions, and feedstock availability linked to broader metallurgical transitions. In that environment, strategic advantage will accrue to organizations that can distinguish durable growth from temporary cyclical noise, align grade portfolios with shifting specification requirements, and secure supply access before capacity reallocations intensify.
Our coal tar pitch market research is designed to support that process by combining macro market visibility with segment-level interpretation. It provides the evidence base needed to evaluate whether to expand supply relationships, pursue qualification in higher-specification grades, or reassess exposure to applications facing heightened regulatory scrutiny. Just as importantly, it offers a structured competitive lens for interpreting the significance of recent capacity expansions, supply agreements, and corridor developments that may reshape buyer leverage over the coming planning cycles.
The full report contains the detailed regional, type, and application breakdowns, the extended competitive profiles, and the scenario discussion that decision-makers require for rigorous 2026 and beyond planning. Readers seeking the complete dataset and analysis are encouraged to access the full study page, where the comprehensive market intelligence is available in a format designed for strategic integration and executive review.
For detailed analysis of this topic, please visit the official page: Coal Tar Pitch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


