



PW Consulting: Hemp Seeds Market Hits USD 500 Million in 2025, Projects 7.5% CAGR to 2032

Strategic Intelligence Brief: Navigating the Hemp Seeds Market Outlook 2026-2032
As the global functional food and wellness ingredients sector accelerates, hemp seeds have emerged as a cornerstone commodity bridging consumer nutrition, industrial utility, and sustainable agriculture. PW Consulting’s newly released Hemp Seeds Market research delivers a comprehensive, data-grounded assessment of this evolving landscape, designed specifically to equip executive leadership, product development teams, and supply chain strategists with the clarity required for high-stakes 2026 decision-making. Unlike broad industry summaries that rely on delayed indicators or superficial trend-spotting, this study maps the structural drivers, competitive fault lines, and regulatory inflection points that will define commercial viability over the next seven years. The following overview outlines the strategic framework, methodological rigor, and actionable intelligence contained within the full report, while preserving the granular segmentation required for precise corporate planning.
The Trajectory and Structural Signals of a Maturing Commodity Market
The hemp seeds sector has transitioned from a niche, regulation-constrained niche to a mainstream ingredient pipeline with measurable macroeconomic traction. Historical performance from 2020 through 2025 demonstrates a consistent upward arc, with annual revenue milestones reflecting sustained demand absorption across food formulation, personal care, and industrial applications. Building on this foundation, the 2026 base-year valuation establishes a clear inflection point, followed by a forecast period extending through 2032 that projects compounded annual growth at 7.5 percent. This trajectory is not merely a linear extrapolation; it reflects converging supply chain maturation, shifting consumer preference toward plant-based complete proteins, and expanding regulatory clarity that has reduced market entry friction for ingredient suppliers and branded manufacturers alike.
Strategists evaluating capital allocation, capacity expansion, or M&A targets will recognize that sustained double-digit absolute growth over a multi-year horizon signals a market moving past early adoption cycles. The compound growth rate indicates that while the category is no longer in its experimental phase, it remains far from saturation. Demand is being pulled by formulation innovation in nutritional supplements and beverage platforms, while simultaneously being pushed by agricultural processors optimizing yield, extraction efficiency, and downstream fractionation capabilities. The full study contextualizes these macro trends against historical volatility, delineating which growth phases are cyclical versus structural, and identifying the specific institutional triggers that will accelerate or constrain regional deployment.
Regulatory Architecture and the New Operational Baselines
Market velocity in hemp-derived ingredients has historically been constrained by legal ambiguity. Recent legislative and administrative actions have materially altered that landscape. The amendment enacted through Pub. L. No. 119-37 on November 12, 2025, clarified the federal definition of hemp by establishing a total THC concentration limit of not more than 0.3 percent on a dry weight basis, while explicitly excluding viable seeds from any parent plant exceeding that threshold. This provision reduces compliance uncertainty for seed-focused growers, processors, and ingredient distributors, enabling more predictable sourcing contracts and downstream certification pathways.
Parallel to statutory clarification, USDA mechanisms continue to provide structured importation pathways for hemp seeds into the United States following their removal from DEA jurisdictional authority under the 2018 Farm Bill framework. These administrative routes have streamlined cross-border supply chains, particularly for processors integrating North American grain with European and Asian finishing capacity. On the formulation side, the FDA’s 2018 GRAS evaluation, which issued no objections to hulled hemp seeds, hemp seed protein powder, and hemp seed oil as food ingredients, remains a critical benchmark. It has enabled rapid incorporation into baked goods, dairy alternatives, snack matrices, and beverage systems without requiring case-by-case premarket approval. The full report maps how these regulatory pillars interact with regional compliance variations, quality assurance protocols, and audit readiness requirements, providing operations leaders with a practical compliance roadmap rather than a theoretical legal summary.
Report Architecture: Operational Intelligence for Executive Deployment
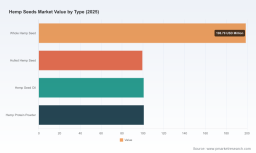
The study is structured to translate market complexity into executable strategy. Readers will find a delineation of product architecture across whole seeds, hulled formats, extracted oils, and protein powders, with each category assessed for processing intensity, margin profiles, storage and logistics constraints, and formulation compatibility. Application pathways are examined through the lens of commercial adoption velocity, highlighting where food and beverage integration drives volume, where nutritional supplement positioning commands premium pricing, where personal care formulations leverage fatty acid and antioxidant profiles, where industrial applications utilize structural and chemical properties, and where animal feed channels absorb byproducts and lower-grade fractions. Regional demand distribution, supply chain nodes, and trade flow patterns are analyzed to identify where processing capacity aligns with consumption growth, and where infrastructural bottlenecks may create pricing dislocations or delay time-to-market for new product launches.
Beyond structural mapping, the report delivers quantitative baselines, forward-looking scenario modeling, and sensitivity analysis that allow strategy teams to stress-test assumptions around yield variability, input cost fluctuations, regulatory enforcement intensity, and competitive entry timelines. The analytical framework is calibrated for 2026 planning cycles, meaning that forecasts are anchored to current capacity utilization, recent processing line expansions, and observable shifts in procurement behavior among large-scale food manufacturers and ingredient distributors. By consolidating historical performance, base-year positioning, and multi-year projections into a single decision-ready format, the study eliminates the need for internal teams to piece together fragmented data sources or rely on outdated secondary references.
Competitive Landscape: Strategic Positioning and Recent Capacity Shifts
The market exhibits moderate concentration, with the top three participants accounting for approximately 45 percent of total revenue and the top five collectively representing roughly 55 percent. This concentration profile indicates a landscape where established processors and vertically integrated ingredient suppliers hold meaningful scale advantages, yet sufficient fragmentation remains to allow specialized entrants, regional growers, and formulation-focused brands to capture differentiated value. The competitive field spans North American grain originators, European fractionation specialists, and global distributors that bridge organic certification, bulk procurement, and retail-ready packaging.
Manitoba Harvest Hemp Foods operates as the largest hemp foods manufacturer in the category, producing and selling raw shelled hemp seeds and hemp seed oil from North American-grown and processed grain, positioning itself as a scale anchor for both retail and ingredient channels. Victory Hemp Foods has recently reinforced its processing leadership by launching North America’s largest hemp heart protein and oil processing line in April 2025, utilizing patented solvent-free fractionation to deliver allergen-free V-70 protein and V-ONE oil, an expansion that directly strengthens its value proposition for plant-based food, baking, and beverage formulators. Navitas Organics and Nutiva maintain strong consumer-facing and wholesale positions by offering organic, non-GMO, gluten-free, and vegan-certified shelled hemp seeds tailored for smoothies, baking, and superfood applications. Green Source Organics and Harvest Hemp Foods supply organic and derived hemp products across food and ingredient markets, while Canah International and Hempflax BV focus on processing and distributing seeds and oils for food and industrial ingredient applications. BAFA neu GmbH emphasizes certified organic seed production for food and animal feed, and Kanda Hemp supplies certified industrial hemp seeds for commercial grain and fiber production. Bulk Hemp Warehouse serves the raw grain and fiber segment with bulk viable whole seeds, whereas Allive and North Central Company address wholesale and snack/baking demand through bulk unhulled, hulled, and organic-compliant supply options.
Hemp Market
The strategic implication for 2026 is clear: scale processors are investing in fractionation and allergen-free certification to capture premium ingredient contracts, while mid-tier and regional players are competing on organic certification, supply reliability, and application-specific formatting. The full study evaluates these players across capacity positioning, product architecture, distribution reach, and recent operational developments, providing a comparative lens that helps procurement and partnership teams identify where scale, where specialization, and where geographic proximity deliver the highest strategic return.
Strategic Imperatives for 2026 Planning Cycles
Executives entering 2026 must treat hemp seeds not as a single commodity line but as a multi-format ingredient ecosystem with distinct margin structures, regulatory touchpoints, and formulation barriers. The most effective strategies will align procurement and capacity decisions with application-specific demand rather than aggregate volume alone. Formulators seeking clean-label protein and lipid profiles will continue to favor hulled seeds, protein powders, and oils that carry GRAS status and organic or allergen-free certifications, which means supplier qualification, batch consistency, and documentation readiness will become as critical as unit pricing.
Supply chain leaders should assess whether existing grain contracts, storage configurations, and finishing capacity match the forecast distribution of whole versus hulled demand, particularly as processors expand fractionation lines and seek to minimize solvent exposure while maintaining throughput. Market entrants and investors will benefit from understanding where regional demand concentration intersects with processing density, and where logistics costs or certification lag may create temporary arbitrage opportunities. Brand managers and innovation teams should monitor how recent legislative clarifications and administrative importation pathways reduce lead-time uncertainty, enabling faster launch cadences for hemp-integrated food, beverage, personal care, and supplement portfolios. The report provides the scenario scaffolding required to evaluate these decisions quantitatively, rather than relying on directional intuition.
Conclusion: From Market Awareness to Decisive Action
The hemp seeds market in 2026 stands at the intersection of regulatory stabilization, processing innovation, and broadening application adoption. Sustained compound growth through 2032 signals that the category has moved beyond experimental positioning into a structured ingredient pipeline with measurable economic gravity. Yet the opportunity is not uniformly distributed across formats, applications, or regions, and the firms that outperform will be those that can translate macro momentum into precise procurement, capacity, and partnership decisions. PW Consulting’s full Hemp Seeds Market research report delivers the segmented baselines, competitive mapping, regulatory context, and forward-looking scenario analysis necessary to make those decisions with confidence. Complete segmentation values, regional deployment detail, application-level revenue splits, and additional processing-line and competitive developments are available in the full study, providing the depth required for board-level planning, product roadmapping, and supply chain optimization.
Hemp Seeds Market
For detailed analysis of this topic, please visit the official page: Hemp Seeds Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


