



PW Consulting: Total Artificial Heart Market Hits $76M in 2025, Projected to Reach $161M by 2032 at 11.5% CAGR

Strategic Horizons in Total Artificial Heart Market: A 2026 Decision Framework
The landscape of advanced heart failure treatment is undergoing a structural shift. As surgical techniques mature and patient demographics evolve, the demand for durable mechanical circulatory support continues to outpace traditional transplant availability. For executives, investors, and clinical strategy leaders, the Total Artificial Heart market represents both a complex regulatory challenge and a high-conviction growth opportunity. Our latest research publication dissects this ecosystem with the granularity required to map out actionable pathways through 2032.
This article serves as a strategic preview of the full report. It highlights the macro trajectory, competitive inflection points, and structural dynamics that will define capital allocation and product development decisions in 2026. The detailed segmentation matrices, regional revenue breakdowns, and application-specific forecasts remain reserved for the complete intelligence package, ensuring that our clients receive a comprehensive, uncompromised view when they access the full dataset.
Market Trajectory and Growth Architecture
The Total Artificial Heart market has demonstrated consistent expansion over the past half-decade, recovering from early pandemic-era disruptions and accelerating as clinical protocols stabilize. The macroeconomic foundation of this growth is anchored in a clear upward revenue curve. From a baseline in the mid-40 million USD range in 2020, the market advanced to approximately 76.0 million USD by 2025, reflecting an environment where clinical adoption, favorable reimbursement frameworks, and iterative device engineering have reinforced one another.
Looking toward the forecast horizon, the market is projected to reach 82.2 million USD in 2026, with a sustained compounding trajectory that pushes total revenue past 161.0 million USD by 2032. This expansion is underpinned by a forecasted CAGR of 11.5 percent, a rate that signals more than incremental volume growth. It indicates a structural broadening of clinical indications, deeper penetration in established centers of excellence, and the gradual entry of next-generation electromechanical platforms into commercial pathways.
For corporate strategists, understanding the timing and shape of this curve is essential. Growth is not distributed uniformly across the forecast window. The 2026 to 2028 period marks a consolidation and scaling phase, where early commercial adopters and regulatory approvals begin translating into recurring procedural volume. Beyond 2029, the market trajectory steepens, driven by expanded destination therapy protocols, evolving bridge-to-transplant algorithms, and the commercialization of devices designed to reduce long-term complications. Our full analysis isolates these inflection intervals, allowing leadership teams to synchronize R&D pipelines, manufacturing capacity, and market access strategies with precise temporal demand signals.
Competitive Landscape and Innovation Frontiers
The Total Artificial Heart arena is defined by a concentrated yet rapidly evolving competitive field. Market leadership has historically been anchored by a single dominant platform with the broadest regulatory clearance and the most extensive clinical track record. This incumbent profile remains the only FDA- and Health Canada-approved total artificial heart for bridge-to-transplant use in the United States and Canada, supported by a substantial implant base exceeding 2,100 procedures. Its continued relevance is reinforced by durable reimbursement coverage, including CPT codes for implantation and replacement that are recognized by major private payers, Medicare, and state Medicaid programs for bridge-to-transplant indications.
However, the competitive architecture is no longer a one-player narrative. Industry momentum is increasingly shaped by differentiated engineering philosophies and targeted regulatory strategies. BiVACOR has emerged as a notable innovator, leveraging MAGLEV technology to pursue a next-generation total artificial heart platform. Its clinical progression has been accelerated by regulatory milestones, including FDA Breakthrough Device Designation and acceptance into the FDA Total Product Life Cycle program, positioning it as a key watchpoint for executives tracking the convergence of magnetic levitation engineering and circulatory support. Parallel developments are evident in the European market, where CARMAT has advanced its Aeson platform into commercial supply following CE-mark recognition under updated Medical Devices Regulation requirements. With more than 100 implants achieved, the Aeson family contributes to a broader geographic and technical diversification of the global supply base.
The competitive field also includes emerging entrants whose clinical and preclinical data are beginning to influence procurement expectations. Recent announcements underscore the pace of real-world evidence generation and iterative design optimization. A significant clinical outcome communication highlighted a successful four-year bridge-to-transplant case using an established total artificial heart platform, with the patient ultimately receiving a donor heart after extended support duration. This outcome reinforces the growing confidence in long-duration mechanical support as a reliable bridge strategy. In parallel, an independent in vitro study published by a developing entrant demonstrated that its device generated approximately half the hemolysis observed in a legacy pneumatic platform, pointing toward a clinically meaningful reduction in blood damage. These developments matter because hemocompatibility, durability, and operational simplicity increasingly determine procurement preferences as centers compare long-term risk profiles across competing systems.
Market concentration data further illuminates competitive strategy. The top three participants account for a modest share of total revenue, and the top five collectively remain below a thirty percent threshold. This relatively fragmented structure suggests that while incumbency and regulatory clearance provide meaningful advantages, the market is open to differentiated innovation, targeted geographic expansion, and specialist center adoption. For strategists, this means competitive positioning must be built on a combination of clinical evidence, regulatory agility, reimbursement fluency, and service-and-support excellence rather than scale alone.
Structural Dynamics Shaping 2026 Decisions
Market growth in 2026 is not solely a function of device availability. It is shaped by intersecting regulatory, reimbursement, and clinical workflow dynamics that determine how quickly new technologies can move from approval to routine use. On the regulatory front, the United States continues to operate under a framework where only one total artificial heart platform currently holds FDA approval for bridge-to-transplant indication. This concentration of cleared options influences hospital procurement pathways, clinical trial design, and the strategic timing of competitor submissions. At the same time, regulatory engagement in other regions is advancing, as seen with updated CE marking under MDR requirements for a European platform, signaling that multinational commercialization strategies must be calibrated to region-specific evidentiary and documentation expectations.
Reimbursement architecture remains a decisive commercial variable. Broad coverage for implantation and replacement procedures under major payer categories has reduced a key barrier to adoption for bridge-to-transplant use. Yet, as destination therapy use expands and longer support durations become more common, payer scrutiny around cost-effectiveness, patient selection criteria, and downstream care pathways is likely to intensify. Decision-makers in 2026 must therefore evaluate not only device performance but also the total economics of care delivery, including hospitalization patterns, complication management, and post-implant service infrastructure.
Clinical adoption is also being reshaped by data streams that compare platform performance on outcomes that matter to transplant programs and advanced heart failure centers. Hemocompatibility, support duration, reliability, and adverse event profiles increasingly differentiate otherwise similar devices. As published evidence accumulates around reduced hemolysis and extended bridge-to-transplant durability, procurement committees will weigh these attributes alongside surgical familiarity and institutional experience. This environment favors suppliers that can pair robust clinical evidence with clear value communication and dependable service networks.
What the Full Report Delivers
The complete Total Artificial Heart Market researchstudy translates the macro trajectory and competitive context into an operational intelligence framework designed for 2026 planning. The analysis is structured to support market entry assessments, portfolio prioritization, partnership evaluation, and regional expansion planning. Rather than offering high-level commentary, the report builds an evidence-linked narrative that connects device technology evolution, regulatory milestones, reimbursement realities, and center-level adoption patterns to the financial and strategic implications for stakeholders.
- Comprehensive market sizing and forecast architecture spanning the historical reference period through 2032, with segmentation designed to support demand modeling and scenario planning.
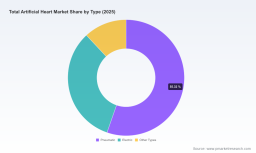
- Technology and platform evaluation that frames pneumatic, electric, and other device categories in terms of engineering design, clinical positioning, and adoption readiness without oversimplifying trade-offs.
- Competitive profiling of leading and emerging participants, including headquarters location, regulatory status, clinical track record, and innovation direction, enabling benchmarking and partnership screening.
- Deep-dive analysis of market dynamics, including regulatory pathways, payer coverage behavior, procedural coding context, and clinical workflow factors that influence procurement timing.
- Regional and application-oriented insight structures that allow teams to evaluate where procedural volume, reimbursement access, and center readiness align with commercial objectives.
- Recent development tracking, including clinical outcome announcements, in vitro performance comparisons, and regulatory designations, integrated into a forward-looking interpretation of market momentum.
Importantly, the full report preserves confidentiality on sensitive segment proportions and localized revenue splits. This ensures that clients receive a complete analytical framework while detailed share distributions and region-specific figures remain part of the controlled intelligence deliverable. The result is a decision-ready document that supports internal alignment, investor communications, and executive planning without prematurely disclosing proprietary segmentation values.
Implications for 2026 Strategy
For organizations operating in or evaluating entry into advanced heart failure device markets, 2026 is a year of positioning. The convergence of durable bridge-to-transplant outcomes, evolving destination therapy considerations, and differentiated device technologies is expanding the scope of strategic options. Yet, the market also demands disciplined interpretation of regulatory status, reimbursement coverage, and real-world performance data. Companies that can distinguish between headline momentum and actionable evidence will be better placed to allocate resources, time product launches, and build credible value narratives for clinical and payer audiences.
Total Artificial Heart Market
Artificial Heart Lung Machines Market
Several strategic priorities emerge from the current environment. First, evidence generation and clinical engagement must remain central, because procurement decisions increasingly depend on comparative performance data and long-duration support outcomes. Second, regulatory strategy should be treated as a multi-market undertaking, with attention to the distinct clearance and certification expectations that shape commercial readiness across regions. Third, service delivery, training, and hospital workflow integration are becoming competitive differentiators as procedural volume grows and centers compare total cost of care rather than device price alone. Fourth, partnership and licensing opportunities may accelerate as organizations seek to combine engineering innovation with established clinical networks and market access capabilities.
The growth rate implied by the forecast period suggests that early movers who align their capabilities with the right indications, geographies, and service models can capture disproportionate value as the market scales. At the same time, the fragmented competitive structure indicates that differentiation remains achievable for new and emerging participants who can demonstrate compelling clinical and operational advantages. The full report is designed to help leaders test these assumptions against detailed data, assess potential entry points, and construct plans that are robust across multiple demand and regulatory scenarios.
Access the Complete Intelligence
The Total Artificial Heart Market researchstudy provides an integrated view of market size, segmentation architecture, competitive dynamics, and regulatory-reimbursement context, structured for immediate application in 2026 strategic planning. This preview has outlined the broad growth trajectory, the competitive and innovation landscape, and the structural forces that will shape adoption and commercialization decisions. It has intentionally omitted the detailed segment proportions and regional revenue distributions that form the analytical backbone of the full publication.
For decision-makers who require precise market sizing, segmentation splits, and scenario-ready forecasts to support budgeting, market entry analysis, and portfolio strategy, the complete report offers the depth needed to move from directional insight to execution-ready intelligence. Accessing the full dataset will enable your team to evaluate where growth is concentrated, how platform technologies compare across clinical and commercial dimensions, and which market dynamics are most likely to influence your positioning through 2032.
For detailed analysis of this topic, please visit the official page: Total Artificial Heart Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


