



PW Consulting: Automatic Deburring Machine Market Hits $534M in 2025, Poised to Reach $691M by 2032

The Automatic Deburring Machine Market: Strategic Intelligence for 2026 and Beyond
The global manufacturing landscape is undergoing a profound transformation, driven by relentless demands for precision, efficiency, and sustainability. Within this shifting terrain, the automatic deburring machine market stands out as a critical enabler of modern production workflows. As industries grapple with tightening tolerances, escalating labor costs, and increasingly stringent environmental regulations, the role of automated surface finishing solutions has evolved from a discretionary upgrade to an operational imperative. Our latest comprehensive market research report on the Automatic Deburring Machine Market offers a meticulously curated intelligence package designed to equip executives, product planners, and investors with the structural insights needed to navigate the 2026–2032 horizon with confidence.
This analysis transcends superficial market sizing. It maps the interplay of technological maturation, regional industrial realignments, and competitive pressures that will define procurement strategies, capacity investments, and partnership frameworks in the years ahead. For decision-makers operating in metal fabrication, automotive, aerospace, or precision electronics, the report serves as a strategic compass, translating macro-level trajectories into actionable commercial intelligence. The following overview outlines the report's core architecture, highlights the operational drivers reshaping the sector, and demonstrates how the full study can be leveraged to de-risk strategic planning for the remainder of the decade.
Market Trajectory: A Structural View of Growth and Resilience
Over the past half-decade, the automatic deburring machine sector has demonstrated remarkable resilience, navigating supply chain volatility, fluctuating raw material costs, and shifting capital expenditure cycles. Historical tracking from 2020 through 2025 reveals a market that has steadily consolidated its footing, with revenue climbing toward the 534 million USD mark in the base year. This upward momentum is not merely cyclical; it reflects a structural recalibration of manufacturing priorities, where consistent edge quality, reduced scrap rates, and repeatable throughput have become non-negotiable benchmarks for competitive operations.
Worldwide Single Axis Automatic Tapping Machine Market
Looking forward, the forecast period extending through 2032 projects a measured yet steady expansion, anchored by a compound annual growth rate of approximately 3.85 percent. While this growth rate may appear moderate at first glance, it belies the nuanced dynamics beneath the surface. The trajectory is being shaped by divergent regional industrial policies, accelerating automation adoption in high-mix production environments, and the gradual replacement of legacy manual finishing workflows. By 2032, the market is positioned to approach the 690 million USD threshold, a milestone that underscores both the maturity of established applications and the emergence of new use cases in advanced manufacturing. Importantly, this growth will not be evenly distributed across customer segments, geographies, or technology platforms. The strategic value of our report lies in its ability to isolate where value is actually concentrating, which sub-segments are experiencing structural shifts, and which regional ecosystems are poised for accelerated capital deployment.
Core Report Architecture: From Macro Trends to Operational Playbooks
Our research is structured to serve multiple internal functions simultaneously. Rather than presenting a monolithic narrative, the report is organized into modular, decision-ready sections that allow strategy, procurement, R&D, and competitive intelligence teams to extract precisely what they need without wading through irrelevant data. The study begins with a comprehensive market overview that establishes baseline sizing, growth vectors, and the macroeconomic forces currently influencing capital equipment spending. From there, the analysis drills into the structural components that drive purchasing behavior and technology adoption patterns.
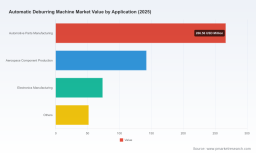
The segmentation framework examines the market across multiple axes, including machine typology, end-use application domains, and geographic distribution. Each dimension is evaluated not merely in terms of revenue allocation but through the lens of operational drivers: how different machine architectures align with specific part geometries, production volumes, and surface finish requirements; how application segments are evolving from traditional high-volume stamping and casting environments toward more complex, high-precision components; and how regional industrial policies, labor market conditions, and supply chain localization efforts are reshaping procurement preferences. The report deliberately avoids static snapshots, instead emphasizing the directional momentum of each segment and flagging inflection points where investment timing or technology selection could materially impact competitive positioning.
Complementing the structural analysis is a detailed examination of market dynamics. This section dissects the forces currently accelerating or constraining adoption, including the persistent shortage of skilled finishing labor, the rising cost of manual quality assurance, and the growing influence of environmental compliance mandates that are pushing manufacturers toward energy-efficient, lower-waste automated systems. The study also tracks the upstream supply ecosystem, analyzing how the availability and pricing of specialized abrasives, high-precision polymers, and integrated material handling components are influencing total cost of ownership calculations. By connecting these dynamic variables to real-world procurement thresholds, the report enables managers to anticipate cost pressures, evaluate alternative technology pathways, and structure supplier negotiations with a clearer understanding of underlying market mechanics.
Competitive Landscape: Navigating a Fragmented but Consolidating Field
The automatic deburring machine ecosystem is characterized by a diverse array of participants, ranging from established European engineering firms with decades of heritage in metal finishing to agile Asian manufacturers leveraging integrated automation expertise and emerging regional players targeting cost-sensitive, high-growth industrial clusters. Our competitive analysis maps this landscape with granularity, profiling the core capabilities, technological differentiators, and strategic positioning of key market participants.
Automatic Deburring Machine Market
In the Americas and Asia, companies such as Timesavers LLC have built their reputation on comprehensive automated deburring and metal finishing lines that leverage advanced abrasive technologies tailored for high-throughput metal part processing. Their operational model emphasizes integrated material flow and consistent surface outcomes across varied part configurations. Meanwhile, ARKU GmbH in Germany continues to strengthen its position with the EdgeBreaker series, which is specifically engineered for stamped, laser-cut, and plasma-cut components, combining automated handling with precise edge treatment in a single workflow. This focus on seamless integration between cutting and finishing processes has made the platform particularly attractive to manufacturers seeking to reduce intermediate handling steps and minimize secondary operations.
In East Asia, Sugino Corp. has carved a distinct niche with high-pressure water jet CNC deburring and parts washing systems, including the JCC series designed to address complex geometries that traditional mechanical methods struggle to finish uniformly. Their approach highlights the growing convergence between deburring and integrated cleaning, reflecting broader industry trends toward multi-function workstations that compress cycle times. United Surface Solutions LLC contributes a complementary perspective with centrifugal deburring equipment and water recycling systems, exemplified by the CPC250 upright barrel machine, which appeals to operations prioritizing media efficiency and environmental compliance.
The competitive field also includes regional specialists with strong positioning in sheet metal and precision fabrication. Valgro India Limited offers automatic deburring and edge rounding machines that rely on brush or belt grinding methodologies, targeting manufacturers seeking flexible, cost-effective solutions for panel and enclosure processing. Autopulit S.A. in Spain has built a reputation around CNC and robotized deburring platforms designed for sheet metal and precision component workflows, emphasizing programmable control architectures that adapt to high-mix production schedules. Fladder Danmark A/S complements this landscape with automatic deburring, sanding, and surface grinding machines featuring programmable controls that span metal, wood, and plastic applications, illustrating the cross-material versatility that some end-users increasingly demand.
Japan's Murata Machinery, Ltd. represents another strategic archetype, offering deburring machines seamlessly integrated with broader automated production systems, supporting both high-volume and low-volume manufacturing scenarios. This systems-level approach resonates with facilities pursuing vertical integration and reduced changeover times. Rounding out the core competitive set, Kramer Industries Inc. provides deburring and finishing equipment tailored to metal fabrication, automotive, and aerospace applications, reinforcing the importance of domain-specific engineering in high-stakes sectors where surface integrity directly impacts downstream performance.
Recent trade show activity and product announcements further illustrate the pace of innovation and the strategic signaling occurring across the competitive field. Throughout late 2025, multiple manufacturers showcased next-generation platforms at major industrial exhibitions. Valgro India Limited presented advanced deburring and finishing solutions, including automatic deburring machines, at FABTECH 2025 in Chicago. ARKU GmbH exhibited its EdgeBreaker 6000 universal deburring machine at Blechexpo 2025, emphasizing leveling and deburring capabilities for coil lines. Lissmac highlighted a compact SBM-XS automatic deburring machine at the same event, focusing on automation concepts for edge processing. Timesavers LLC also demonstrated its automated deburring portfolio at FABTECH Chicago. These exhibited developments are not isolated product launches; they signal broader strategic priorities around automation density, footprint optimization, and workflow integration, all of which carry direct implications for procurement strategy and vendor evaluation.
The competitive structure itself warrants close attention. Market concentration metrics indicate a moderately fragmented environment, with the top three players collectively holding a meaningful but not dominant share, and the top five approaching a slightly higher threshold of combined presence. This fragmentation suggests that regional specialists, application-focused vendors, and emerging technology providers retain substantial room to differentiate through niche engineering, localized service networks, or integration partnerships. For buyers and investors, this dynamic creates both opportunity and complexity: the diversity of offerings expands choice, but it also demands rigorous capability mapping to avoid overpaying for features that do not align with specific production requirements.
Structural Drivers Shaping 2026 Decision-Making
Several interlocking forces are redefining how manufacturers evaluate automatic deburring investments in 2026 and beyond. The most persistent is the ongoing pressure on skilled labor availability. Across metal fabrication, automotive component production, and precision machining, facilities continue to encounter difficulties in recruiting and retaining operators capable of delivering consistent manual deburring quality at scale. This labor constraint is not a temporary anomaly; it reflects deeper demographic and training pipeline challenges that are accelerating the business case for automation. By deploying automatic deburring machines, manufacturers can standardise edge quality, reduce dependence on highly variable manual processes, and redirect skilled personnel toward higher-value supervisory, programming, and quality engineering roles.
A second, closely related driver is the economic calculus around labor cost escalation. As remuneration expectations in sheet metal processing, precision component fabrication, and related sectors continue to rise, the total cost differential between manual finishing and automated solutions is narrowing in favor of the latter. Beyond direct wage inflation, manufacturers are accounting for the hidden costs of human error, inconsistent repeatability, and rework cycles that erode throughput. Automatic deburring systems address these pain points by delivering predictable output quality across shifts and production runs, which in turn supports tighter process control and more reliable downstream assembly or coating operations.
Environmental and regulatory pressures are simultaneously reshaping the technology benchmark. Manufacturers are increasingly required to demonstrate energy efficiency, reduced waste generation, and optimised consumable usage across their surface finishing workflows. This regulatory push is prompting equipment developers to redesign machine architectures for lower power draw, improved media recovery, and integrated water or abrasive recycling loops. For procurement teams, the implication is clear: energy consumption profiles, consumable lifecycle costs, and compliance documentation are becoming as important as initial capital outlay and throughput specifications. Our report integrates these considerations into the evaluation framework, helping decision-makers weigh total cost of ownership against evolving compliance expectations.
Upstream material dynamics also play a critical role. The performance and longevity of automatic deburring systems depend heavily on the availability and quality of specialized abrasives, high-precision polymers, and engineered media formulations. Supply trends in these component categories are increasingly aligned with sustained adoption in high-volume metal finishing, but pricing volatility, lead time variability, and regional sourcing constraints can affect operational continuity. The report maps these supply-side variables to provide a clearer picture of which technology pathways are most resilient under current material conditions and which may expose facilities to greater procurement risk.
How the Full Study Translates Intelligence into Advantage
While the macro trajectory and competitive themes outlined here provide a valuable orientation, the full research study delivers the depth required for concrete strategic action. The complete report supplies the granular segmentation data, regional growth differentials, application-specific adoption curves, and technology preference shifts that executives need to calibrate manufacturing investments, evaluate vendor shortlists, and identify high-probability opportunities for process optimisation. It also includes scenario-based projections that account for alternative macroeconomic conditions, raw material price trajectories, and regulatory pacing, enabling planners to test the robustness of their assumptions against multiple futures.
For competitive strategists, the study offers a structured framework for mapping rival capabilities, predicting likely product roadmap moves, and identifying whitespace where differentiated offerings can capture margin. For procurement and operations leaders, it provides the comparative benchmarks necessary to align machine selection with part complexity, volume profiles, and quality requirements, reducing the risk of over-specification or under-investment. For investors and corporate development teams, the analysis highlights consolidation pressure points, regional growth hotspots, and technology adjacencies that may influence valuation logic or partnership strategy.
The value of this intelligence is maximised when it is integrated into a structured decision process rather than treated as a static reference document. Our research is designed to feed directly into capacity planning workshops, vendor evaluation scorecards, capital allocation reviews, and regional expansion assessments. By grounding those conversations in a rigorously sourced, forward-looking analysis, organisations can move from reactive equipment purchasing to proactive capability building, aligning their deburring workflows with the broader strategic imperatives of precision, efficiency, and sustainability that will define competitive manufacturing through 2032.
To access the complete segmentation breakdowns, regional growth differentials, competitive capability matrices, dynamic scenario models, and the full vendor profiling framework, we invite you to consult the complete Automatic Deburring Machine Market research publication. The full study delivers the unredacted intelligence required to transform high-level market awareness into precise, executable strategy for 2026 and the decade ahead.
For detailed analysis of this topic, please visit the official page: Automatic Deburring Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


