



PW Consulting: Ultrafast Lasers Market Hits $2.34B in 2025, Forecast 16.62% CAGR to $6.89B by 2032

Ultrafast Lasers Market 2026: Strategic Intelligence for Enterprise Decision-Making
The Pulse of Modern Precision
Ultrafast lasers have evolved from specialized laboratory instruments into foundational technologies that enable precision manufacturing, advanced healthcare, and next-generation scientific discovery. These systems, characterized by extremely short pulse durations on the femtosecond and picosecond scales, deliver unparalleled control over material interaction without generating excessive thermal damage. As industrial processes demand finer tolerances and new applications emerge across quantum technologies and medical devices, the ultrafast laser sector is undergoing a structural transformation that requires careful strategic navigation.
For enterprise leaders, investors, and technology strategists, understanding the trajectory of this market is no longer optional. The convergence of industrial automation, semiconductor miniaturization, and emerging healthcare applications creates a complex landscape where timely intelligence determines competitive positioning. This report provides the analytical framework necessary to interpret market signals, evaluate competitive dynamics, and identify high-value opportunities across the ultrafast laser ecosystem.
Macro Trajectory: A Market in Acceleration
The ultrafast lasers market has demonstrated consistent expansion over the past half-decade, building momentum that extends well into the forecast horizon. Historical valuation patterns from 2020 through 2025 reveal a sector that has repeatedly exceeded baseline growth expectations, driven by broadening application adoption and sustained capital investment in precision technologies. This upward trajectory establishes a robust baseline for forward-looking analysis and signals that demand drivers are structural rather than cyclical.
Looking ahead to the 2026 through 2032 forecast period, the market is positioned for continued expansion at a compound annual growth rate of 16.62 percent. This growth rate reflects accelerating integration of ultrafast laser systems into production environments, alongside expanding deployment in research and medical contexts. The revenue trajectory projects a market valuation that underscores the strategic importance of this technology category for organizations operating across multiple industrial and scientific verticals. Revenue projections are measured in USD millions, providing a standardized framework for comparative financial planning and investment prioritization.
For decision-makers, this macroeconomic profile carries several implications. The sustained growth rate indicates that ultrafast lasers are transitioning from emerging technology status to mainstream industrial utility. Organizations that delay engagement risk ceding positioning to competitors who are already embedding these systems into their operational toolkits. Conversely, early movers who align their technology roadmaps with verified market data can secure advantages in vendor relationships, application development, and market segment prioritization.
The forecast horizon further reveals inflection points that warrant strategic attention. As the market scales, shifts in supply chain capacity, competitive intensity, and application-specific demand patterns will reshape the landscape in ways that historical data alone cannot predict. Comprehensive analysis is required to distinguish between temporary fluctuations and durable structural changes, ensuring that strategic decisions rest on verified intelligence rather than extrapolation.
Segment Architecture and Application Versatility
The ultrafast laser market spans multiple technology typologies, each serving distinct operational requirements and end-use contexts. Fiber-based laser architectures continue to command significant attention due to their compactness and cost-effectiveness, particularly for microprocessing and industrial material modification. Titanium-sapphire systems remain critical for advanced research and specialized scientific applications where tunability and pulse characteristics are paramount. Diode-pumped configurations offer specific advantages in certain manufacturing and imaging scenarios, while mode-locked variants serve niche but high-value applications requiring precise temporal control.
This technological diversity creates a segmented market where competitive positioning varies significantly by product category. Organizations evaluating ultrafast laser procurement or investment must understand how these technology segments map to their specific operational needs. A manufacturing environment focused on high-throughput material processing may prioritize different capabilities than a research institution requiring tunable wavelengths for experimental protocols. The report provides detailed segmentation analysis that maps technology characteristics to application requirements, enabling stakeholders to align procurement strategies with verified performance benchmarks.
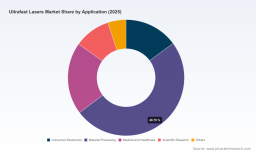
Application domains further diversify the market landscape. Material processing represents a substantial demand driver, encompassing industrial manufacturing, semiconductor precision work, and advanced micromachining applications. Medical and healthcare deployments leverage ultrafast laser capabilities for surgical procedures, diagnostic imaging, and therapeutic device development. Consumer electronics applications increasingly incorporate these technologies for precision component fabrication. Scientific research continues to serve as both a demand source and an innovation incubator, with discoveries in laboratory settings frequently translating into commercial production techniques. Additional application categories contribute to the broader ecosystem, reflecting the technology's versatility across multiple sectors.
The interplay between technology types and application domains creates a multi-dimensional market structure where winners are not uniformly distributed. A company that excels in fiber laser manufacturing may face different competitive pressures than one focused on titanium-sapphire systems for research instrumentation. Understanding these segment-specific dynamics is essential for accurate competitive assessment and strategic planning.
Competitive Arena: Players Shaping the Landscape
The ultrafast laser market features a diverse array of established corporations and specialized innovators, each pursuing distinct strategic positions. Coherent Corp, headquartered in the United States, offers a comprehensive range of ultrafast scientific laser oscillators and amplifiers serving research, OEM instrumentation, and industrial applications. TRUMPF, based in Germany, provides ultrafast lasers tailored for industrial materials processing, semiconductor applications, and precision manufacturing environments. IPG Photonics, also United States-based, manufactures compact and cost-effective ultrafast fiber lasers with pulse durations spanning from 250 femtoseconds to 5 picoseconds for microprocessing and industrial deployment.
Amplitude Systèmes, operating from France, holds a recognized position as a world leader in femtosecond lasers for industry, science, and medical applications, delivering systems for micromachining and medical device production. Ekspla, based in Lithuania, supplies industrial femtosecond laser systems for advanced imaging, ultrafast material processing, and micromachining tasks. NKT Photonics, from Denmark, delivers next-generation ultrafast lasers targeting quantum computing, aerospace, and industrial manufacturing applications. Light Conversion, also headquartered in Lithuania, provides high-performance femtosecond laser systems for industrial and scientific applications with emphasis on reliability. Menlo Systems, based in Germany, manufactures femtosecond fiber lasers and amplifiers for high-output power applications across research and industrial contexts. IMRA America, operating from the United States, specializes in femtosecond fiber lasers for material processing, biomedical, and imaging applications. Clark-MXR, United States-based, produces femtosecond lasers and micromachining systems alongside contract manufacturing services. Thorlabs, also from the United States, offers photonics solutions including ultrafast laser components and systems for both research and industrial use.
This competitive field reflects a market characterized by both specialized expertise and broad technological ambition. Recent corporate activities illustrate the dynamic nature of this landscape. In January 2026, IMRA America notified the Foreign-Trade Zone Board of proposed production activity for femtosecond fiber laser systems in Ann Arbor, Michigan, within FTZ 70, encompassing optical components and materials. This development signals continued investment in domestic manufacturing capacity for advanced laser technologies. Earlier in June 2025, IPG Photonics showcased innovative fiber laser technologies and new product launches at Laser World of Photonics in Munich, demonstrating ongoing product development and market engagement. In August 2024, NKT Photonics announced delivery of three next-generation laser subsystems to IonQ for trapped-ion quantum computing and networking equipment, highlighting the technology's expanding role in quantum infrastructure. By May 2026, IPG Photonics earned the 2026 SPIE Prism Award in the Lasers category for its novel 8-kilowatt compact single-mode laser source with high beam quality, validating continued innovation in high-power ultrafast systems.
Structural Dynamics and Operational Realities
Beyond technology and competition, the ultrafast laser market operates within a complex environment of regulatory, labor, and supply chain factors that influence production timelines, cost structures, and deployment feasibility. These structural dynamics require careful consideration in strategic planning and investment evaluation.
Regulatory frameworks introduce compliance considerations that affect market participants differently depending on their operational scope and geographic footprint. Certain optical sources and sub-components fall under export control classifications, creating compliance requirements and potential limitations for advanced optical materials used in ultrafast laser systems. Organizations operating across international markets must navigate these requirements carefully, as regulatory exposure can influence sourcing strategies, partnership structures, and market access.
Workforce dynamics present another critical consideration. The production of advanced laser systems, including ultrafast lasers, faces challenges related to skilled labor availability. Technical manufacturing and engineering roles require specialized expertise that remains in limited supply, creating potential bottlenecks for production scaling and innovation deployment. Organizations that invest in workforce development, training partnerships, and talent retention strategies position themselves to mitigate these constraints while competitors struggle with staffing gaps.
Supply chain fragility introduces additional operational complexity. Specialty components and advanced materials required for ultrafast laser manufacturing face availability constraints and performance variability, resulting in extended lead times, production delays, and quality control challenges. The ecosystem for low-volume, high-risk commodities is particularly constrained, requiring deliberate supplier relationships and collaborative supply chain management to maintain production continuity. These dynamics affect not only manufacturers but also downstream customers who depend on reliable access to production-grade laser systems.
Ultrafast Lasers Market
Material considerations further compound supply chain challenges. Limited availability and performance issues of advanced laser system components directly impact manufacturing timelines and product quality. Organizations operating in this space must develop contingency strategies, maintain buffer inventories where feasible, and establish diversified supplier networks to reduce vulnerability to single-source disruptions.
Strategic Imperatives for 2026 and Beyond
The ultrafast lasers market presents a landscape rich with opportunity but demanding rigorous analysis to navigate successfully. For enterprises evaluating technology adoption, investment allocation, or competitive positioning, the strategic questions are multifaceted. Which technology segments align with specific operational requirements? How do competitive dynamics vary across applications and geographies? What supply chain and regulatory factors should influence procurement timing and vendor selection? How should organizations balance near-term production needs against long-term innovation trajectories?
Answering these questions requires access to granular analysis that goes beyond aggregate market figures. Segment-level growth patterns, regional demand variations, application-specific adoption curves, and competitive benchmarking all contribute to a complete strategic picture. Organizations that rely on high-level summaries risk missing the nuanced signals that determine successful market engagement. The difference between a well-timed investment and a misaligned procurement decision often rests on details that only comprehensive analysis can reveal.
This report, the Ultrafast Lasers Market study from PW Consulting, is designed to provide that depth. It delivers detailed segmentation breakdowns, competitive profiling, regional demand analysis, and operational context that enables decision-makers to move from general awareness to actionable insight. The analysis covers the full 2020 through 2032 timeline, connecting historical performance with forward-looking projections to identify durable trends and potential inflection points.
For organizations seeking to understand where ultrafast laser technologies fit within their strategic roadmap, this research offers the evidence base necessary for confident decision-making. The market's growth trajectory, technological diversity, and competitive intensity all demand analysis that is sufficiently detailed to support precise planning while remaining accessible enough to inform executive-level strategy.
Accessing Complete Market Intelligence
The insights summarized here represent an entry point into a comprehensive analytical resource. Full segmentation data, complete competitive profiles, regional demand breakdowns, and detailed scenario analysis are available in the complete report. Enterprise leaders, technology strategists, and investment professionals who require verified market intelligence for critical decisions will find the full study provides the depth and specificity necessary to translate market awareness into operational advantage.
Worldwide Ultrafast Lasers for Micromachining Market
To access the complete Ultrafast Lasers Market report and obtain the detailed intelligence required for strategic planning in 2026 and beyond, please visit the PW Consulting research portal for full report access and acquisition options.
For detailed analysis of this topic, please visit the official page: Ultrafast Lasers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


