



PW Consulting: Slurry Tankers Market Hits $1,450M in 2025, Growing at 7.8% CAGR Through 2032

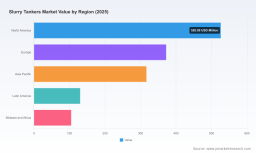
Beyond Capacity: Strategic Intelligence for the Evolving Slurry Tankers Market
The global agricultural and industrial infrastructure landscape is undergoing a structural transformation, and few equipment categories illustrate this shift as clearly as slurry tankers. As precision farming, environmental compliance, and nutrient management consolidate into core operational imperatives, decision-makers require more than historical sales figures. They need forward-looking intelligence that maps capacity planning, regulatory exposure, competitive positioning, and regional demand trajectories into a single actionable framework. Our latest market research release does exactly that.
This analysis serves as a strategic preview of the full report. It demonstrates the analytical rigor, data architecture, and commercial relevance embedded in the study, while preserving the granular breakdowns that procurement leaders, investors, and OEM strategists will need to access directly. The objective is clear: equip executives with the confidence to act, while directing detailed segment-level intelligence to the complete publication for precise planning.
Market Trajectory and the Strategic Imperative for 2026
The slurry tankers market has demonstrated consistent expansion across the 2020 to 2025 historical window, moving from a baseline revenue footprint of approximately $1,050 million in 2020 to an estimated $1,450 million by 2025. This growth reflects more than cyclical agricultural demand. It signals a structural recalibration driven by tightening nutrient runoff regulations, the modernization of farm-scale logistics, and the industrial adoption of precision slurry handling systems.
Looking ahead, the forecast period from 2026 through 2032 projects a compound annual growth rate of 7.8 percent on a USD basis. By the close of the forecast horizon, the market is positioned to reach a substantially higher revenue threshold, underscoring a durable demand environment rather than a temporary upcycle. For corporate planners, this trajectory carries immediate implications. Capital allocation decisions made in 2026 will determine whether organizations capture early-mover advantages in high-growth configurations, align procurement with regulatory timelines, or risk exposure to capacity shortages and compliance gaps.
The strategic value of this research lies in its ability to translate macro growth into executable planning parameters. Executives reviewing the full report will find historical validation paired with forward-looking scenarios that account for policy shifts, technology adoption curves, and regional supply chain dynamics. Rather than treating market size as a static number, the study frames it as a living indicator of operational readiness across agriculture, industry, and adjacent application segments.
Regulatory Architecture and Competitive Dynamics
Market expansion in this category is not occurring in a vacuum. Environmental legislation has become a primary catalyst for equipment specification, procurement timing, and technology integration. Across multiple jurisdictions, regulators are mandating precision application, reducing ammonia emissions, and requiring comprehensive nutrient management planning. These mandates are reshaping demand patterns and accelerating the transition toward vacuum-assisted systems, GPS-enabled dosing controls, and advanced spreading implements.
In the European Union, the Nitrates Directive continues to anchor application limits, with enforcement across member states driving adoption of equipment capable of meeting stricter emission thresholds. National frameworks in Germany, Denmark, and the Netherlands have layered additional requirements, particularly in nitrate-vulnerable zones, where precision application equipment and trailing shoe injector compatibility are increasingly non-negotiable for new tanker procurement. These regulatory pressures are not merely compliance costs; they are redefining product specifications, influencing chassis design, and elevating the strategic importance of modular, upgrade-ready platforms.
Outside Europe, policy environments are equally consequential. In North America, concentrated animal feeding operation regulations are reinforcing the need for structured nutrient management planning, directly supporting slurry tanker demand in intensive dairy and livestock regions. In Canada, agricultural operations legislation has introduced planning thresholds that incentivize equipment adoption for larger-scale enterprises. The cumulative effect is a regulatory landscape that rewards manufacturers and fleet operators who proactively integrate precision technology, while creating friction for legacy configurations that lack adaptability.
These dynamics also shape competitive behavior. The market exhibits a measured concentration profile, with the top three players holding a combined share of approximately 28 percent and the top five approaching 42 percent. This structure indicates a landscape where established manufacturers maintain meaningful influence, yet sufficient fragmentation remains to reward differentiated engineering, localized service networks, and targeted product launches. For procurement and strategy teams, understanding where concentration ends and regional specialization begins is critical to supplier evaluation and risk mitigation.
What the Full Report Delivers: Scope, Structure, and Operational Utility
The complete market research publication is designed to move beyond high-level commentary and provide a structured intelligence toolkit. It combines historical validation, forward-looking forecast modeling, segmentation logic, and competitive profiling into a single reference framework. The report is organized to support multiple decision contexts, from capex planning and supplier selection to market entry analysis and product roadmap alignment.
Slurry Tankers Market
At the core of the study is a detailed segmentation architecture that isolates demand patterns across equipment configurations and end-use contexts. Buyers will find scenario-ready data that clarifies how different tanker formats are positioned across operational environments, and where capacity, maneuverability, and application precision intersect with commercial priorities. Regional analysis is presented to illuminate demand distribution, adoption maturity, and policy-driven variation across major geographic markets, allowing planners to identify where regulatory acceleration, farm modernization, or industrial slurry handling practices are most influential.
Slurry Pump Market
The forecasting methodology integrates historical performance with forward indicators to project revenue evolution across the 2026 to 2032 horizon. Rather than offering a single deterministic outcome, the research frames growth as a function of policy enforcement, technology refresh cycles, and regional investment pacing. This approach is particularly valuable for organizations that must justify multi-year equipment programs or evaluate the timing of fleet upgrades against compliance deadlines.
Operational utility extends to product specification trends as well. The report examines the growing importance of vacuum-assisted designs, chassis-independent architectures, lightweight axle configurations, and integrated spreading or dosing systems. These technical themes are mapped against practical considerations such as storage capacity ranges, emptying efficiency, material durability, and compatibility with precision nutrient application workflows. For engineering and procurement teams, this provides a structured way to compare vendor offerings against operational requirements and regulatory expectations.
Competitive intelligence is another central pillar. The publication profiles leading manufacturers and evaluates how product differentiation, regional footprint, and recent launch activity shape market positioning. This includes attention to design innovations, capacity ranges, certification status, and the strategic emphasis each company places on sustainability, precision application, or modular expandability. Recent launch activity is tracked to identify where product refresh cycles are accelerating and where feature upgrades are likely to influence purchasing decisions in the near term.
Competitive Positioning: Where Differentiation Is Being Won
The competitive environment in slurry tankers is increasingly defined by engineering specificity. Manufacturers are differentiating not only through capacity, but through design architectures that address crack prevention, pressure-vessel certification, full emptying performance, lightweight axle optimization, and integrated nutrient management workflows. These attributes are becoming decisive factors in fleet procurement, particularly where operators must balance efficiency, regulatory conformity, and long-term serviceability.
Several leading players illustrate the breadth of current market strategy. Major Equipment has built its positioning around custom-designed slurry tankers, emphasizing a patented bottom design intended to reduce cracking risk and support capacities that span from mid-range to large-volume configurations, often paired with vacuum pumps and spreaders. JEANTIL has focused on chassis-independent vacuum slurry platforms with PED-certified pressure vessels and multi-purpose spreading equipment, targeting precision application across a broad capacity spectrum. Garant Kotte operates with a strong German market presence, emphasizing lightweight axle systems, full emptying capability, and alignment with liquid manure technology standards across single- to four-axle formats.
Other participants reflect regional adaptation and application-specific refinement. Rigual has placed emphasis on truck-mounted and trailer-mounted configurations, combining spreading equipment with sustainable design principles and digital transformation initiatives aimed at high-volume farm slurry collection and transport. In New Zealand, Nevada Group has specialized in dairy effluent slurry tankers with varied axle configurations, pond stirrers, and nutrient management system integration. SlurryKat has pursued innovation in both vacuum and non-vacuum configurations, with product lines designed for efficient farm-to-field transfer and bespoke umbilical systems. JOSKIN S.A. has expanded its European manufacturing footprint around high-capacity galvanized and Alpina-series platforms, offering modular vacuum options and precision spreading implements across multiple production sites.
Recent launch activity reinforces the pace of product evolution. SlurryKat introduced a new tanker series showcasing advanced vacuum technology and precise dosing capabilities, while Giligroup expanded its portfolio with a large-capacity tanker integrated with an applicator aimed at improving spreading efficiency. SAMSON Group broadened its tanker range with a model emphasizing enhanced performance and container options, and Pichon Industries added multiple platform variations to strengthen capacity and application versatility. These releases are not isolated product updates; they are indicators of where manufacturers are placing strategic bets on compliance readiness, precision delivery, and fleet flexibility.
Strategic Use Cases: Turning Intelligence into Action
For executive teams, the full report is structured to support several high-stakes decisions. Procurement leaders can use segmentation and regional data to align tanker specifications with operational context, ensuring that capacity, axle configuration, and application technology match both field requirements and regulatory timelines. OEMs and component suppliers can leverage competitive profiling and product launch tracking to identify whitespace, anticipate refresh cycles, and calibrate engineering priorities against demand signals. Investors and analysts can use the forecast framework to assess market durability, evaluate concentration dynamics, and determine where regional policy momentum is most likely to influence revenue growth.
The study also supports scenario planning around compliance-driven demand. As precision application mandates tighten and nutrient management planning becomes more entrenched, organizations that understand where regulatory acceleration is strongest can sequence fleet renewal, prioritize vacuum-assisted or injection-compatible configurations, and reduce the risk of stranded legacy assets. The research makes these connections explicit by linking policy dynamics, regional enforcement variance, and equipment specification trends into a coherent planning narrative.
Conclusion: Navigate 2026 with Precision, Not Assumption
The slurry tankers market is entering a phase where growth, regulation, and technology adoption converge. Historical expansion has laid the foundation, the forecast period points to sustained momentum, and competitive differentiation is increasingly tied to precision engineering, compliance readiness, and regional adaptation. For organizations operating in agriculture, industry, or supporting equipment ecosystems, the question is no longer whether the market is expanding, but how to position assets, procurement, and product strategy in response.
This publication preview has outlined the strategic architecture of the research and demonstrated why the full report matters for 2026 decision-making. To access the complete segmentation data, regional demand breakdowns, competitive share detail, forecast scenarios, and manufacturing profiles needed for precise planning, readers should consult the full market research release. The intelligence required to act with confidence is there; the strategic advantage comes from using it early.
For detailed analysis of this topic, please visit the official page: Slurry Tankers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


