



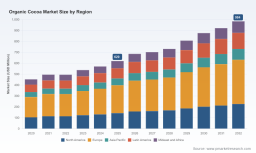
PW Consulting: Organic Cocoa Market Hits $620M in 2025, Projected $984M by 2032 at 6.98% CAGR

Strategic Intelligence for the Organic Cocoa Market: Navigating Growth, Compliance, and Competitive Dynamics in 2026
Executive Overview: Why This Study Matters for 2026 Decision-Makers
The global organic cocoa sector is entering a decisive inflection point. Over the past five years, the market has transitioned from a niche, ethically driven segment into a core component of mainstream food and beverage supply chains. Our latest market research synthesizes five years of historical performance with a seven-year forward outlook, delivering a structured intelligence framework designed specifically for executives, procurement leaders, and strategy teams operating in 2026 and beyond. This study is not a static snapshot. It is a decision-support architecture that connects macroeconomic momentum, regulatory realignments, supply chain restructuring, and competitive positioning into a single actionable narrative.
For organizations evaluating capital allocation, product portfolio expansion, sourcing partnerships, or regional market entry, the actionable insight lies in understanding how structural demand shifts intersect with compliance timelines and concentration patterns. The research abstracts raw figures into strategic signals, enabling leadership teams to model scenarios, stress-test assumptions, and prioritize initiatives that align with the trajectory of the organic cocoa ecosystem.
Macro Trajectory: Translating Five-Year Evolution into Forward Momentum
Historical performance from 2020 through 2025 reveals a market that has consistently expanded despite macroeconomic volatility, input cost fluctuations, and periodic supply disruptions. The trajectory demonstrates resilient demand absorption across multiple downstream channels, supported by consumer preference shifts toward clean-label, sustainably sourced, and certified ingredients. By the close of the base year, the market had reached a scale that firmly embeds organic cocoa within mainstream procurement strategies rather than treating it as a peripheral premium offering.
The forward projection window spanning 2026 through 2032 outlines a sustained growth path anchored by a compound annual growth rate of 6.98 percent. This rate is not merely a statistical output; it reflects the combined effect of expanding certified cultivation footprints, rising institutional procurement standards, and the gradual integration of organic derivatives into mass-market formulations. The growth curve implies that companies positioning themselves now will capture compounding advantages in supplier relationships, processing capacity alignment, and brand differentiation. Conversely, organizations that delay strategic adaptation risk encountering tighter certified supply availability, elevated compliance friction, and intensifying competition for premium-origin material.
Revenue scaling over the forecast horizon underscores the importance of capacity planning and derivative mix optimization. As total market value advances toward the high nine-hundred-million range by the end of the projection period, the relative contribution of intermediate cocoa derivatives versus finished applications will shape sourcing strategies, pricing architectures, and margin structures. Decision-makers require a clear understanding of how volume growth translates into derivative demand, processing bottlenecks, and downstream formulation opportunities. This research provides that translation layer, enabling teams to align procurement forecasts with production capabilities and commercial roadmaps.
Structural Dynamics: Regulation, Value Creation, and Supply Chain Realignment
The operating environment for organic cocoa is being reshaped by regulatory tightening, certification architecture upgrades, and producer-side operational adjustments. Beginning in early 2025, the European Union Organic Regulation framework introduced enhanced compliance expectations for imported organic cocoa, including strengthened audit requirements and Group of Operators controls. The transition phase concluded at the end of 2024, and full compliance obligations intensified throughout 2025 for suppliers targeting European markets. These measures elevate traceability standards, increase documentation rigor, and place renewed pressure on cooperative structures and segregation practices.
A critical strategic consideration is the compliance readiness gap across smaller producer organizations. Industry observations indicate that a significant share of small-scale Fairtrade organic cocoa producer organizations do not yet fully meet the new EU requirements related to membership structure and operational segregation. At the same time, regulatory adjustments have extended certain compliance deadlines for smaller enterprises, creating a temporary window for adaptation but also introducing uncertainty around supply continuity and certification status during 2026. For buyers and processors, this environment demands more rigorous supplier due diligence, clearer certification pathway mapping, and contingency planning for origin-dependent sourcing portfolios.
On the producer side, organic cocoa cultivation continues to present a structurally distinct cost and value proposition. By avoiding synthetic fertilizers and associated input dependencies, organic systems reduce certain recurring production costs while enabling price premiums that can improve farmer-level economics when market conditions support them. This dynamic reinforces the strategic relevance of long-term cooperative relationships, capacity-building programs, and certification support initiatives. Recent institutional engagement in origin markets, including partnerships focused on uniting producer groups and expanding organic and fair-trade certification coverage, illustrates how development-oriented support can accelerate supply base maturation. These interventions matter because they influence both the quantity and the reliability of certified supply flowing into international markets.
Together, these dynamics create a market environment where compliance capability, traceability infrastructure, and cooperative readiness function as strategic differentiators rather than administrative obligations. Organizations that treat these factors as core elements of their sourcing strategy will secure more resilient supply access and stronger positioning in premium procurement channels.
Strategic Segmentation Insights Without the Noise
Effective market strategy requires an understanding of how value is distributed across product forms and end-use channels, without becoming lost in fragmented data points. The research framework emphasizes three structural lenses that matter most for 2026 planning:
-
Derivative mix relevance: Organic cocoa is not a monolithic commodity. The relative scale and growth behavior of cocoa butter, cocoa liquor, and cocoa powder directly influence formulation strategies, pricing sensitivity, and processing requirements. Procurement teams must evaluate which derivative pathways align with their product architecture, margin targets, and processing capabilities. Understanding where the largest revenue concentration sits within the derivative spectrum helps organizations prioritize supplier discussions, capacity commitments, and inventory strategies.
-
Application-driven demand behavior: Demand is heavily shaped by how organic cocoa is incorporated into end products. Confectionery remains the dominant application environment, reflecting the central role of organic cocoa in chocolate and snack formulations. At the same time, bakery products and beverages represent meaningful demand channels with distinct sourcing attributes, quality specifications, and procurement cycles. Companies need to understand how application mix influences volume stability, specification requirements, and pricing dynamics rather than relying on generic market aggregates.
-
Regional demand architecture: Demand is distributed across multiple geographic markets, each with different regulatory exposure, consumer preference intensity, and import dependency patterns. Europe represents a major demand center with stringent certification expectations. North America reflects strong premium and clean-label consumption trends. Asia Pacific, Latin America, and the Middle East and Africa collectively contribute diverse demand profiles shaped by local processing capacity, export orientation, and emerging consumer segments. Regional nuance matters because sourcing accessibility, logistics complexity, and compliance pathways differ materially by market.
By abstracting segmentation into strategic implications rather than isolated statistics, the study equips decision-makers to evaluate where to concentrate commercial effort, which derivative and application combinations offer the most resilient growth paths, and how regional demand patterns should influence sourcing geography and risk allocation.
Competitive Landscape: Concentration, Capability, and Positioning
The organic cocoa market is characterized by a moderately concentrated competitive structure, with a meaningful share of market value held by a limited number of established processors, integrated traders, and specialist suppliers. Concentration patterns indicate that scale, certified supply chain control, and processing capability remain important competitive levers. At the same time, the presence of specialized organic processors, cooperative-linked exporters, and premium brand manufacturers demonstrates that differentiation through traceability, origin identity, and certification integrity continues to create viable market niches.
Several types of players define the competitive field:
-
Integrated global suppliers and processors: Large international companies with broad ingredient portfolios and established sustainable sourcing programs maintain strong positions by combining scale, multi-origin access, and traceable supply architectures. Their relevance lies in the ability to serve bulk and premium demand simultaneously while investing in certification, segregation, and supply chain transparency.
-
Specialist organic processors: Focused operators with dedicated organic processing capacity play a critical role in converting certified beans into liquor, butter, and powder for distinct application segments. Their competitive advantage often rests on controlled processing environments, origin-specific sourcing relationships, and the ability to maintain organic integrity through the production chain.
-
Origin-based cooperatives and exporters: Producer-linked organizations with multiple organic certifications contribute directly to supply resilience and traceability narratives. Their strategic importance extends beyond volume; they enable provenance storytelling, support compliance readiness at the farm level, and provide buyers with structured relationships that can reduce supplychain friction.
-
Premium chocolate and ingredient brands: Brands that combine manufacturing with direct sourcing or proprietary processing create differentiated offerings based on flavor profile, ethical sourcing claims, and application-specific ingredient quality. Their presence reinforces the premiumization trend and demonstrates how organic cocoa can support brand-level differentiation in consumer-facing markets.
-
Specialized ingredient and bakery-focused suppliers: Companies oriented toward chocolate, bakery, and foodservice applications provide organic cocoa ingredients tailored to formulation needs. Their role highlights the importance of application-specific quality parameters and supply consistency for downstream manufacturing customers.
Recent institutional developments reinforce the importance of certification support and cooperative strengthening in origin markets. Partnerships aimed at uniting producer groups, expanding organic and fair-trade certification coverage, and introducing improved agroforestry practices illustrate how supply-side capacity building can influence long-term availability and quality consistency. For commercial stakeholders, these developments are strategically relevant because they affect the reliability of certified supply, the pace at which new producer organizations reach export readiness, and the overall robustness of traceable organic chains.
In this environment, competitive advantage is increasingly determined by the ability to secure dependable certified supply, maintain processing integrity, and demonstrate verifiable traceability. Organizations that combine procurement foresight with supplier development partnerships and compliance readiness will be better positioned to navigate both demand growth and regulatory complexity.
What the Report Delivers: Operational Intelligence for Planning and Execution
This market research is structured to move beyond descriptive overviews and provide practical intelligence that can be embedded into planning processes. The report is designed for cross-functional use, supporting strategy, procurement, commercial development, and risk management teams with a shared evidence base.
Key components include:
-
Market sizing and forward trajectory analysis: A consolidated view of historical performance and forecast progression, organized to help leadership teams understand the pace of expansion, the shape of the growth curve, and the implications for capacity planning and investment timing.
-
Strategic segmentation interpretation: Analysis of how value is distributed across cocoa derivatives and end-use applications, translated into procurement, formulation, and portfolio implications rather than isolated percentage breakdowns.
-
Competitive positioning and supplier mapping: A structured overview of the principal companies shaping the market, their operational models, and the strategic roles they play across processing, trading, branding, and origin-based supply. This enables stakeholders to identify partnership candidates, benchmark capabilities, and understand where consolidation or specialization is most likely to influence pricing and availability.
Organic Cocoa Market -
Regulatory and compliance pathway context: Practical framing of the EU organic compliance environment, transition timelines, and the implications of certification architecture changes for sourcing strategies, supplier qualification, and risk mitigation.
-
Supply chain and origin dynamics: Evaluation of how cooperative readiness, certification support, and producer-side practices influence the reliability and quality of certified organic cocoa entering international markets.
-
Actionable planning frameworks: Structured guidance for translating market intelligence into sourcing decisions, product development priorities, regional engagement strategies, and scenario-based contingency planning.
Cocoa Market
The study is built to support decision-making under uncertainty. Rather than presenting market data as a static backdrop, it connects size, growth, concentration, segmentation behavior, and regulatory dynamics into a coherent operational narrative. This allows executives to answer practical questions about where demand is heading, which supply relationships deserve reinforcement, how compliance readiness should influence supplier selection, and which market segments offer the most favorable combination of growth potential and strategic control.
How to Use This Intelligence in 2026
For organizations operating in or entering the organic cocoa market, the strategic imperative is to align commercial ambition with supply realism. Growth potential is meaningful, but it is mediated by certification readiness, processing capacity, regulatory compliance, and the behavior of concentrated incumbents. The most effective 2026 strategies will be those that combine demand-side opportunity assessment with supply-side due diligence and compliance-aware procurement design.
Leadership teams can use this research to prioritize actions such as:
-
Validating whether current sourcing portfolios are resilient to evolving organic compliance expectations and origin-side certification gaps.
-
Assessing whether derivative and application focus areas match the strongest demand and margin opportunities across the forecast horizon.
-
Identifying supplier and processor partners whose operational models, traceability systems, and certification capabilities align with long-term procurement requirements.
-
Evaluating regional demand patterns and supply access considerations when planning market entry, expansion, or reformulation initiatives.
-
Integrating concentration dynamics into pricing, negotiation, and risk-management assumptions, especially where a limited number of suppliers shape availability in key segments.
The study is intended to serve as a working intelligence asset rather than a one-time read. By linking macro trajectory, segmentation logic, competitive structure, and regulatory context into a single framework, it helps organizations convert market complexity into executable strategic choices.
Conclusion: Positioning for Durable Advantage in a Maturing Organic Cocoa Market
The organic cocoa market is no longer defined solely by ethical consumption trends or premium niche positioning. It is becoming a structurally important ingredient category shaped by regulatory evolution, supply base maturation, derivative demand behavior, and competitive concentration. The growth path projected through 2032 indicates that organizations which invest now in sourcing integrity, compliance readiness, and differentiated supply relationships will be better equipped to capture value as the market scales.
This research provides the strategic context needed to make those investment decisions with greater confidence. It translates market size and growth momentum into operational relevance, frames segmentation in terms of procurement and formulation implications, and maps the competitive field in a way that supports partnership selection, risk planning, and commercial prioritization. The full report builds on this foundation with detailed analysis designed to support execution-level decision-making across the 2026 to 2032 horizon.
For executives seeking a complete view of market sizing, segmentation logic, competitive positioning, regulatory dynamics, and actionable planning frameworks, the full study offers the comprehensive intelligence required to move from directional awareness to precise strategic execution.
For detailed analysis of this topic, please visit the official page: Organic Cocoa Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


