



PW Consulting: Convenience Store Software Market Hits $190M in 2025, Projected 4.19% CAGR Through 2032

Navigating the Next Wave: Strategic Intelligence for the Convenience Store Software Market Through 2032
The convenience store sector stands at a critical inflection point. As operators balance thin margins, labor volatility, and accelerating consumer expectations, software is no longer a back-office utility but a core competitive lever. Our latest research release, the Convenience Store Software Market study, provides a structured, forward-looking intelligence framework designed specifically for executive decision-making in 2026 and beyond. This briefing outlines how the report translates macro trends, competitive movements, and operational pressures into actionable strategy.
Why 2026 Demands a Clearer Market Lens
The global convenience store software market has demonstrated steady expansion through the 2020–2025 historical window, moving from an estimated USD 150.0 million in 2020 to approximately USD 190.0 million by 2025. That trajectory reflects more than nominal growth; it signals a structural shift in how retailers procure, integrate, and scale technology. Looking ahead through the 2026–2032 forecast period, the study maps a compounded annual growth rate (CAGR) of roughly 4.19 percent, positioning the market to reach just over USD 251.2 million by 2032.
These figures are not abstract benchmarks. For multi-site retailers, franchise networks, and independent operators, they represent the size of the addressable technology ecosystem in which procurement choices will be made, vendor contracts negotiated, and operational roadmaps built. Our analysis distills what those numbers imply for capital allocation, platform standardization, and digital transformation sequencing—without overstating certainty or masking the assumptions behind the projections.
Worldwide Retail Billing Software Market
Forecast Architecture: What the Numbers Mean for Executive Planning
The forecast is constructed across a disciplined time horizon, anchoring executive planning in 2026 while extending visibility through 2032. The 2026 baseline sits at approximately USD 196.73 million, with the model projecting progressive movement through 2027–2029 before reaching the terminal 2032 estimate. Rather than presenting a single line of growth, the report contextualizes how expansion is distributed across deployment models, application categories, and geography.
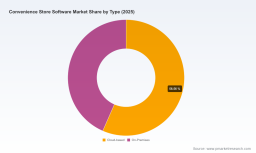
The research intentionally avoids reducing the market to isolated percentage splits, because real purchasing behavior is rarely segment-pure. Instead, the study examines how cloud-based and on-premises solutions interact within the same operator footprint, how application priorities shift from transaction processing to inventory intelligence and customer engagement, and how regional maturity levels influence adoption timing. This integrated view gives leadership teams a more realistic basis for evaluating vendor roadmaps, integration costs, and rollout sequencing.
Operational Drivers Reshaping the Market
Several contemporaneous forces are compressing timelines and raising the stakes for software investment. Labor constraints remain one of the most persistent operational challenges. Shortages and high turnover are accelerating demand for AI-enabled tools that automate scheduling, inventory tracking, and day-to-day workflows, reducing dependence on manual processes. In parallel, regulatory complexity is intensifying around data privacy, health safety, and sector-specific compliance, including regional frameworks such as GDPR. These requirements are not peripheral; they are becoming procurement criteria.
Infrastructure dynamics are also influencing platform preferences. Cloud-based systems are increasingly viewed as a way to simplify compliance with complex fuel and tobacco tax obligations, an operational burden that can strain smaller teams and fragmented back offices. The result is a market in which software selection has become a compliance, efficiency, and risk-management decision at the same time. Our report maps these drivers against adoption patterns so that leadership can anticipate where pressure will translate into spend and where it will create implementation friction.
Competitive Landscape: Capability Differentiation Over Brand Scale
The market is populated by a diverse mix of specialists and broader retail technology providers. Understanding their positioning matters because competitive advantage in this sector is increasingly defined by the depth of domain fit rather than the breadth of a general platform. The study profiles the companies shaping the ecosystem, including AccuPOS, SSCS, PDI Technologies, POS Nation, ADD Systems, DataMax, SHENZHEN KEMAI, CStorePro Inc., Petrosoft, Paytronix, GK Software, NCR Voyix, Oracle Corporation, Toshiba Global Commerce Solutions, and Tote.ai.
Each player brings a distinct orientation. Some emphasize POS and inventory management tailored specifically to convenience stores. Others concentrate on inventory accuracy, data management, or back-office precision for fuel and c-store operations. A subset focuses on wholesale inventory and fuel logistics, while others lean into loyalty, customer engagement, omnichannel retail management, or enterprise-grade POS and ERP solutions for large operators. Emerging entrants are also pushing AI-powered POS and kiosk-based foodservice technology into fuel and convenience environments.
Recent activity reinforces how rapidly this field is evolving. In February 2026, Tote.ai was selected by Spinx to deploy an AI POS system with self-service kiosks and foodservice capabilities across all locations, with go-live planned for the second half of 2026. Earlier in the cycle, GK Software demonstrated omnichannel POS and retail solutions at the NACS Show 2025, highlighting adoption among seven of the top 20 convenience store companies. Toshiba Global Commerce Solutions also showcased future-oriented convenience retail technology, including POS and AI solutions, at the same event. These developments point to a market where integration, automation, and customer-facing experience are converging, and where vendor selection increasingly determines operational agility.
Concentration Dynamics and Procurement Implications
Market structure matters as much as market size. The report includes concentration metrics that frame how competitive the landscape is from a buyer's perspective. With a CR3 near 28.5 percent and a CR5 around 35.0 percent, the sector is moderately fragmented, but not shallow. This has direct implications for negotiation strategy, vendor diversification, and switching costs. For operators evaluating platform consolidation, the concentration picture helps clarify where leverage exists, where dependency risk may accumulate, and where specialized providers can outperform broader suites on domain-specific functionality.
Rather than leaving procurement teams to infer these dynamics from product brochures, the study places concentration in the context of deployment choices and application priorities. This enables a more grounded assessment of how much room there is for differentiation, where standards are beginning to form, and which capabilities are becoming table stakes rather than optional upgrades.
What the Study Delivers Beyond High-Level Estimates
The report is designed as an operational reference, not a static snapshot. It combines market sizing with qualitative and structural analysis intended to support real decisions in budgeting, vendor evaluation, and rollout planning. Key elements include:
- A historical and forecast baseline that situates current demand within a longer adoption curve, helping leaders distinguish cyclical noise from durable growth signals.
- A multi-dimensional segmentation view that connects deployment models, application categories, and regional maturity without reducing the market to disconnected data points.
- A structured competitive profiling section that maps offering focus, geographic roots, and capability emphasis across the companies actively shaping the market.
- An integrated dynamics section that ties regulatory complexity, compliance burdens, labor constraints, and cloud-based operational advantages to purchasing behavior and implementation risk.
- Up-to-date momentum indicators drawn from recent partnerships, trade show activity, and product direction, giving decision-makers a current read on where innovation is being commercialized.
Taken together, these components create a shared language for strategy, operations, and procurement teams. The objective is to enable more disciplined questions: Which capabilities should be standardized and which should remain flexible? Where does compliance pressure justify earlier investment? How should deployment models be chosen across sites with different operating realities? The report provides the analytical scaffolding to answer those questions with greater confidence.
How Leadership Teams Can Use This Intelligence in 2026
For executives planning the next investment cycle, the study serves as a decision filter. It helps clarify whether a near-term purchase is primarily an efficiency play, a compliance play, or a customer-experience play, and it connects each objective to the broader market trajectory. The forecast and competitive mapping also support scenario thinking: what changes if cloud adoption accelerates faster than expected, if AI-enabled automation becomes a stronger hiring and training mitigant, or if regulatory requirements tighten further across key regions.
Equally important, the research is built to support vendor conversations with more precision. By understanding where specialized providers concentrate their value and where larger platforms extend their reach, operators can evaluate proposals against a clearer benchmark. That reduces the risk of buying into generic capability claims and increases the likelihood of selecting solutions that fit the operational cadence of convenience retail.
Accessing the Full Strategic Picture
This briefing is intended as a directional preview. The complete report extends well beyond the summary signals presented here, offering a fuller mapping of market structure, competitive positioning, and the operational forces shaping adoption through 2032. For teams that need to move from high-level awareness to procurement-ready insight, the full study provides the depth required to align technology strategy with business strategy.
The convenience store software market is expanding within a defined but dynamic corridor, and the operators who navigate it most effectively will be those who treat software selection as a strategic process rather than a tactical purchase. Our research is designed to make that process more transparent, more evidence-based, and more actionable for 2026 decision-making and the years that follow.
Convenience Store Software Market
For detailed analysis of this topic, please visit the official page: Convenience Store Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


