



PW Consulting: Cleanroom Air Filters Market to Reach $1.2B by 2032, Growing at 5.2% CAGR

Navigating the Cleanroom Air Filters Market: Strategic Imperatives for 2026 and Beyond
Executive Overview
The global cleanroom air filters market stands at a pivotal inflection point. From a baseline of approximately 652.0 million USD in 2025, the sector is projected to expand to roughly 890.1 million USD by 2026, continuing a steady trajectory toward nearly 1.2 billion USD by 2032. This growth, underpinned by a compound annual growth rate of 5.2 percent across the 2026 to 2032 forecast window, reflects more than incremental demand. It signals a structural recalibration of how critical industries approach contamination control, regulatory compliance, and operational resilience. For executives, procurement leaders, and capital allocators, the coming cycle demands a nuanced understanding of technological differentiation, supply chain reconfiguration, and shifting compliance architectures.
This analysis introduces our latest comprehensive Cleanroom Air Filters Market research, designed specifically to equip decision-makers with actionable intelligence ahead of the 2026 planning cycle. Rather than presenting a static snapshot, the report functions as a strategic operating manual. It dissects historical performance, maps forward-looking demand vectors, and evaluates competitive positioning with surgical precision. The following sections outline the core analytical pillars, competitive dynamics, and forward-looking scenarios that will shape capital deployment, vendor selection, and market entry strategies over the next several years.
Market Architecture and Forward Trajectory
Historical Performance and Growth Inflection
The past five years have demonstrated consistent expansion for cleanroom filtration systems, with revenue climbing from 506.02 million USD in 2020 to a validated baseline of 652.0 million USD in 2025. This trajectory reflects sustained capital expenditure in high-purity manufacturing environments, accelerated facility standardization, and an uncompromising stance on airborne particle control. The 2026 projection of 890.1 million USD indicates a pronounced year-over-year acceleration, suggesting that multiple demand drivers are converging simultaneously rather than operating in isolation.
Looking ahead, the forecast period extends through 2032, with revenue milestones scaling progressively to 952.23 million USD in 2027, 987.3 million USD in 2028, 1.024 billion USD in 2029, 1.088 billion USD in 2030, 1.168 billion USD in 2031, and a terminal estimate of 1.197 billion USD in 2032. This steady compounding pattern is not merely a statistical artifact. It reflects durable structural demand, incremental technology adoption cycles, and a global manufacturing footprint that increasingly treats cleanroom integrity as a non-negotiable operational requirement.
Key Demand Vectors Shaping the Forecast
The market is shaped by several overlapping forces that will dictate growth velocity and regional prioritization. Semiconductor fabrication continues to demand tighter particle control as feature sizes shrink and yield sensitivity intensifies. Pharmaceutical and biologics production has tightened environmental validation protocols, particularly as contract development and manufacturing organizations scale sterile fill-finish operations. Concurrently, the rise of lithium-ion battery production, advanced medical device assembly, and controlled hospital environments has broadened the application spectrum beyond traditional high-volume cleanroom deployments. These vectors are not uniform in their pacing. Some accelerate rapidly in response to technology roadmaps, while others evolve more gradually as regulatory frameworks mature and capital cycles align.
Material science evolution also plays a central role. HEPA and ULPA filter media increasingly incorporate high-grade microglass fibers and advanced polymers, with production costs influenced by shifts toward sustainable material sourcing in medical-grade cleanroom applications. This dynamic creates both margin pressure and differentiation opportunities for manufacturers that can optimize pleatability, reduce pressure drop, and maintain compliance without compromising throughput.
Competitive Landscape and Strategic Positioning
Profiling the Core Players
The competitive field is anchored by a cohort of established filtration specialists and diversified industrial manufacturers, many of whom maintain concentrated positions in high-efficiency cleanroom solutions. Camfil, headquartered in Stockholm, Sweden, specializes in HEPA and ULPA cleanroom panels, ceiling modules, and Pharmaseal ducted filter systems tailored for ISO 5 to 8 environments and pharmaceutical or biotechnology facilities. Parker Hannifin, based in Cleveland, Ohio, offers complete lines of cleanroom HEPA and ULPA standalone and pre-filters with efficiencies reaching up to 99.9995 percent for critical manufacturing applications. 3M, from St. Paul, Minnesota, manufactures Filtrete HEPA air purifier filters and industrial filtration cartridges deployed in cleanroom environments for particle removal.
Cleanroom Air Filters Market
Donaldson Company, headquartered in Bloomington, Minnesota, provides panel collector filters and industrial air filtration systems, including cleanroom solutions for pharmaceutical and semiconductor applications. Freudenberg Filtration Technologies, operating from Weinheim, Germany, supplies HEPA and ULPA filters, Fan Filter Units, and BIBO containment systems for cleanroom and battery manufacturing environments. MANN+HUMMEL, based in Linden, Germany, develops HEPA and ULPA filters and ceiling systems specifically for cleanroom applications in operating theaters, pharmaceuticals, and microelectronics. AAF International, from Louisville, Kentucky, offers HEPA and ULPA filters, containment systems, and full-line air filtration for cleanroom, semiconductor, and pharmaceutical use. Dafco Filtration Group, based in Canada, produces high-efficiency cleanroom filters and specialized filtration solutions for controlled environments. Nippon Muki, headquartered in Tokyo, manufactures ULPA to pre-filter systems and cleanroom equipment for semiconductor, LCD, and high-purity applications. Hollingsworth and Vose, from East Walpole, Massachusetts, stands as a global leader in HEPA and ULPA filter media engineered for cleanroom performance with low pressure drop and superior pleatability. CleanAir Solutions, Inc., located in Fairfield, California, specializes in HEPA filters and Fan Filter Units for modular hardwall and softwall cleanrooms and contamination control.
Market Concentration and Competitive Differentiation
The industry exhibits notable concentration, with the top three firms capturing approximately 55 percent of market revenue and the top five firms extending that share to roughly 65 percent. This concentration suggests that scale, technical certification capabilities, and compliance infrastructure remain powerful moats. At the same time, it creates opportunities for mid-tier specialists to compete on application-specific engineering, regional service coverage, and customized containment architectures. Differentiation is increasingly driven by validation readiness, installation efficiency, filter lifecycle economics, and the ability to integrate containment systems with broader facility airflow strategies.
Recent Corporate Developments Reshaping the Field
The competitive landscape is actively evolving through capacity expansion, portfolio enhancements, and strategic consolidation. In September 2025, Camfil expanded HEPA and ULPA filter production at its Manesar plant, increasing supply capacity for hospitals, pharmaceutical cleanrooms, and biotechnology laboratories while aligning output with EN 1822 and ISO 29463 standards. In November 2025, Freudenberg Filtration Technologies launched next-generation Fan Filter Units, upgraded BIBO containment systems, and NMP-resistant filters designed for semiconductor, pharmaceutical, and lithium-ion battery cleanrooms, emphasizing improved energy efficiency. Also in November 2025, AAF International introduced the AstroScan M system for in-situ validation and leak testing of bag-in and bag-out HEPA containment systems in cleanroom applications. More recently, in January 2026, Cleanova acquired U.S.-based Airflotek and TES-Clean Air Systems to expand capabilities in advanced cleanroom and high-efficiency air filtration solutions for controlled environments.
Air Filters Market
These developments illustrate a broader pattern: manufacturers are investing not only in incremental capacity but also in validation technologies, containment integration, and application-specific material resistance. The result is a market where product performance and compliance documentation are becoming inseparable from commercial competitiveness.
Regulatory and Technical Dynamics Defining Market Behavior
Cleanroom filtration performance is governed by a dense framework of standards that shape procurement criteria, vendor qualification, and lifecycle planning. HEPA and ULPA filters are required to meet EN 1822 and ISO 29463 standards for particle removal and integrity testing in pharmaceutical and semiconductor applications. Filter performance for cleanroom applications is further governed by IEST CC RP-CC001 protocols for DOP and PAO leak testing, alongside MPPS efficiency verification at the 0.12 to 0.3 micron range. For hospitals and biopharma facilities, cleanroom installations must comply with ISO 14644-1 classifications for air cleanliness levels, particularly across Class 5 to 8 sterile environments.
On the commercial side, pharmaceutical and medical device cleanroom filtration solutions can be eligible for capital equipment reimbursement under relevant DRG and CPT codes for hospital containment systems supporting sterile production. This reimbursement pathway can influence procurement timing, facility budgeting, and vendor selection in healthcare-adjacent deployments. Together, these regulatory and reimbursement dynamics create a compliance-first purchasing environment where documentation, testing transparency, and lifecycle validation often outweigh price alone.
What the Full Report Delivers for 2026 Decision-Making
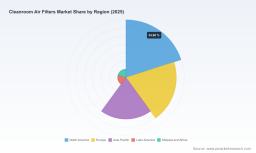
Our Cleanroom Air Filters Market research translates these macro trends into a structured, decision-ready framework. The report provides a complete market sizing and forecast architecture built on historical performance from 2020 through 2025 and a forward projection spanning 2026 to 2032. It examines segmentation across type, application, and regional demand structure, while preserving strategic confidentiality around granular splits that are most valuable when accessed in full. The analysis includes competitive profiling, market concentration assessment, and scenario-based interpretation of how supply-side actions and demand-side adoption cycles may interact over the forecast horizon.
Operationally, the report is designed to support multiple use cases. Strategic planners can use it to calibrate capacity investments and assess demand durability across application categories. Procurement teams can use it to contextualize vendor offerings against compliance requirements and performance benchmarks. Investors and corporate development groups can use the competitive and concentration analysis to evaluate consolidation risks, partnership opportunities, and market entry barriers. Throughout, the report emphasizes practical interpretation over raw data presentation, ensuring that figures are linked to decision logic rather than isolated as abstract statistics.
Strategic Takeaways for Executive Teams
The cleanroom air filtration market in 2026 will reward organizations that treat contamination control as a strategic capability rather than a commoditized procurement line. Several themes stand out for leadership teams preparing their next planning cycle.
- The forecast trajectory indicates that demand expansion is broad-based, but growth will not be uniform across applications, regions, or filter categories. Prioritization should follow application criticality and compliance intensity rather than headline market size alone.
- Regulatory validation and standards alignment have become core commercial differentiators. EN 1822, ISO 29463, IEST testing protocols, and ISO 14644-1 classification requirements are entering purchasing decisions as gating criteria, not afterthoughts.
- Market concentration suggests that scale players hold structural advantages in certification infrastructure and global supply consistency, but targeted specialists can compete effectively through application-specific engineering, containment integration, and localized service models.
- Recent capacity expansions, product launches, and acquisitions point to an industry actively tightening its offerings around energy efficiency, containment validation, and material resistance for advanced manufacturing. Vendors that can demonstrate measurable operational benefits beyond particle capture will gain a stronger position in qualified buyer evaluations.
- Material cost dynamics and sustainable sourcing shifts are beginning to influence production economics, especially in medical-grade cleanroom applications. Lifecycle cost modeling and filter change-out strategy will become increasingly important in total cost of ownership assessments.
For executives, the central question is no longer whether cleanroom air filtration demand will grow, but where value will concentrate as the market matures. The companies and institutions that succeed in 2026 will be those that align procurement, compliance, and capacity planning with a clear view of application-specific demand, technical differentiation, and competitive momentum.
Closing Perspective
The cleanroom air filters market is moving from steady expansion into a phase defined by standards intensification, application diversification, and selective consolidation. The 2026 to 2032 forecast window offers a multi-year lens through which to evaluate capital allocation, vendor partnerships, and market positioning. This report is built to provide that perspective with analytical rigor and practical relevance. For teams that need a complete view of segmentation structure, regional demand architecture, company-by-company positioning, and forward scenarios, the full research delivers the depth required to convert market intelligence into executable strategy.
For detailed analysis of this topic, please visit the official page: Cleanroom Air Filters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


