



PW Consulting Gene Therapy Market Forecast: $12B in 2025, 19.25% CAGR Through 2032

Navigating the Gene Therapy Revolution: Strategic Intelligence for 2026 Corporate Decision-Making
The global gene therapy landscape has entered a definitive phase of commercial acceleration. After years of clinical promise and regulatory caution, the sector is now characterized by tangible revenue generation, expanding indication profiles, and a regulatory environment that is actively streamlining development pathways. For executive teams, board members, and investment strategists, the challenge has shifted from assessing feasibility to orchestrating scalable commercialization, supply chain resilience, and market access frameworks. Our latest comprehensive study on the Gene Therapy Market delivers the operational intelligence required to navigate this inflection point with precision.
Between 2020 and 2025, the industry demonstrated a consistent upward trajectory, with revenue climbing from approximately 4.89 billion USD to 12.0 billion USD. This foundational growth establishes a robust baseline as we enter the 2026 to 2032 forecast period. Current projections indicate that the market will surpass 14.5 billion USD in 2026 and continue its aggressive expansion, reaching roughly 40.82 billion USD by the close of the forecast window. This progression reflects a compound annual growth rate of 19.25 percent, a pace that places gene therapy among the most dynamic segments in modern biopharma. Understanding the structural drivers behind this momentum, the competitive architectures shaping it, and the operational complexities that will determine execution success is no longer optional. It is a strategic imperative.
The 2026 Decision-Making Imperative
Gene therapy commercialization in 2026 operates within a fundamentally altered ecosystem. Regulatory agencies have recognized that traditional development frameworks often misalign with the unique biology and manufacturing realities of advanced therapy medicinal products. In response, policymakers are recalibrating approval pathways, reimbursement mechanisms, and manufacturing oversight to accelerate patient access while preserving safety standards. Simultaneously, payers and health technology assessment bodies are grappling with the economic implications of one-time, high-upfront interventions. These converging forces create both unprecedented opportunity and substantial execution risk.
Corporate leaders must now address questions that extend far beyond clinical efficacy. How should organizations structure manufacturing partnerships to mitigate supply chain volatility? Which geographic markets will offer the most favorable regulatory and reimbursement environments for specific therapeutic modalities? How can commercial teams design pricing and access strategies that align with evolving payer expectations without compromising long-term franchise value? The answers require granular, scenario-tested intelligence that generic market summaries cannot provide. Our research is engineered to fill that gap, transforming macroeconomic trends into actionable strategic roadmaps.
Understanding the Market Architecture
The revenue trajectory observed over the past half-decade reflects more than incremental adoption. It signals the maturation of delivery technologies, the successful navigation of pivotal clinical trials, and the emergence of standardized manufacturing protocols that reduce historical bottlenecks. The forecast period through 2032 suggests that these gains will compound rather than plateau. Several structural factors underpin this outlook.
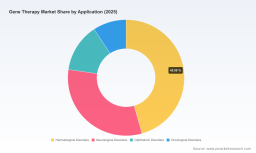
- Therapeutic pipelines are diversifying across hematologic, neurologic, oncologic, and ophthalmic indications, reducing historical concentration risk and expanding the addressable patient population.
- Delivery vector innovation continues to improve transduction efficiency and tissue specificity, enabling developers to target diseases that were previously considered pharmacologically inaccessible.
- Manufacturing and supply chain infrastructure is undergoing targeted investment, though organizations must still navigate significant cost pressures related to ultra-cold logistics and specialized biological raw materials.
- Regulatory flexibility is increasing, with oversight bodies implementing more adaptive chemistry, manufacturing, and controls frameworks to reduce development friction and accelerate submission timelines.
Our analysis dissects how these forces interact across technology platforms, therapeutic categories, and regional commercial environments. Rather than presenting static snapshots, the report maps the causal relationships that will determine which programs achieve sustainable commercial traction and which encounter structural headwinds.
Competitive Landscape and Strategic Positioning
The gene therapy market is defined by a relatively concentrated leadership tier, with a small group of multinational organizations commanding a substantial share of commercial revenue and pipeline value. This concentration reflects the capital intensity of development, the technical complexity of manufacturing, and the strategic advantage of established regulatory and commercialization infrastructure. Yet the competitive dynamics extend well beyond market share arithmetic.
Leading organizations are executing differentiated strategies that align with their therapeutic focus, manufacturing capabilities, and partnership ecosystems. Novartis continues to leverage its pioneering position in neuromuscular gene therapy, building commercial infrastructure around transformative treatments for spinal muscular atrophy. Bristol-Myers Squibb has integrated cell and gene therapy assets into a broader oncology portfolio, using CAR T and related modalities to strengthen its hematologic malignancy franchise. Janssen Biotech, operating within Johnson & Johnson, has advanced CAR T platforms that target multiple myeloma, emphasizing the convergence of cellular engineering and commercial scale.
Vertex Pharmaceuticals has positioned itself at the intersection of gene editing and hemoglobinopathies, bringing forward therapies for sickle cell disease and beta-thalassemia that represent a paradigm shift in chronic disease management. bluebird bio maintains a multi-product portfolio spanning hematologic and cerebral adrenoleukodystrophy indications, reflecting a strategy built on durable patient relationships and specialized delivery networks. Sarepta Therapeutics has expanded the frontier of neuromuscular intervention with gene therapy programs for Duchenne muscular dystrophy, while BioMarin Pharmaceutical and CSL Behring have targeted hemophilia with single-dose approaches that promise to redefine standard-of-care economics. Smaller but highly specialized players such as Krystal Biotech and PTC Therapeutics are capturing niche indications with breakthrough potential, demonstrating that focused platforms can still achieve meaningful commercial differentiation.
The research provides detailed competitive profiling that goes beyond corporate descriptions. It evaluates pipeline adjacency, manufacturing scalability, regulatory posture, and commercial execution risk, enabling decision-makers to benchmark their positioning against the strategies of peers and potential partners.
Stem Cell Therapy Market
Dynamics Shaping Commercial Execution
Market growth alone does not guarantee commercial success. The operational realities of gene therapy commercialization introduce complexities that require deliberate strategic design. Several dynamics are particularly consequential in 2026.
Reimbursement frameworks are evolving rapidly to accommodate the economic profile of one-time interventions. High upfront costs have prompted payers to explore outcome-based agreements that tie compensation to durable clinical benefit, shifting financial risk and aligning incentives across manufacturers, providers, and insurers. In parallel, public payer programs have introduced mechanisms such as expanded New Technology Add-on Payment frameworks to offset a substantial portion of qualifying therapy costs during the early adoption phase. European markets have moved further toward mandating outcomes-based managed entry agreements for single-dose gene therapies, creating a harmonized expectation that commercial strategies must incorporate real-world evidence generation and long-term follow-up infrastructure.
Manufacturing and supply chain management remain among the most capital-intensive and operationally sensitive components of gene therapy programs. Biological raw materials and cold-chain logistics can represent a significant share of total supply chain expenditure due to the requirements for ultra-cold shipping and specialized handling. Organizations that fail to secure resilient sourcing, validated distribution networks, and contingency capacity risk delays that can erode clinical momentum and commercial launch windows.
Regulatory developments continue to reshape development velocity. Recent flexibilities in chemistry, manufacturing, and controls requirements reflect a broader willingness to adapt oversight frameworks to the unique characteristics of cell and gene therapies. Updated approvals and expanded product lists demonstrate that regulatory pathways are becoming more navigable, but they also raise the stakes for organizations that must maintain compliance while accelerating timelines.
Our report integrates these dynamics into a cohesive operational framework. It identifies where cost structures are most sensitive, which regulatory adaptations offer the greatest timeline advantages, and how market access strategies can be structured to satisfy payer requirements without constraining long-term pricing flexibility.
What the Report Delivers
This study is designed for strategy, business development, commercial operations, and investment teams that require more than high-level market narratives. It delivers an integrated analytical architecture that connects macroeconomic growth indicators with the operational, competitive, and regulatory factors that determine execution outcomes. The report includes the following core components.
- A comprehensive market sizing and forecast model that traces revenue evolution from historical baselines through the 2026 to 2032 projection period, with scenario analysis that accounts for regulatory, clinical, and commercial variables.
- A structured segmentation analysis that examines technology platforms, therapeutic applications, and regional commercial environments, emphasizing the interplay between modality characteristics and market access conditions.
- Detailed competitive profiling of leading manufacturers and specialized developers, including pipeline positioning, product portfolio strategy, manufacturing considerations, and commercial execution risk factors.
- An operational dynamics assessment covering reimbursement architecture, regulatory developments, supply chain cost structures, and the practical implications of outcomes-based agreements for pricing and launch planning.
- Strategic recommendations that translate analytical findings into actionable guidance for market entry, partnership evaluation, capacity planning, and portfolio prioritization.
Throughout the analysis, we maintain a focus on decision utility. Every dataset, framework, and competitive observation is oriented toward helping organizations answer concrete questions: where to allocate resources, which partnerships offer the strongest strategic fit, how to anticipate payer and regulator behavior, and what operational capabilities must be built or secured before launch.
Why This Research Matters Now
The gene therapy market is transitioning from a phase of technological validation to one of commercial scaling and strategic differentiation. In this environment, organizations that rely on fragmented data sources or outdated assumptions risk misjudging both opportunity and exposure. The convergence of regulatory flexibility, reimbursement innovation, and expanding clinical evidence creates a narrow window in which strategic decisions will have disproportionate long-term impact.
Access to the complete research enables teams to move beyond directional awareness and into precise planning. It provides the depth required to evaluate pipeline adjacency, assess manufacturing and supply chain exposure, model reimbursement scenarios, and benchmark competitive positioning with confidence. Most importantly, it reveals the market-specific data and scenario analyses that allow leaders to stress-test their strategies against realistic contingencies rather than optimistic projections.
The full study includes the granular segmentation values, regional commercial breakdowns, modality-level growth trajectories, and competitive intelligence that organizations need to construct informed, defensible strategies for the 2026 to 2032 period. To access the complete dataset, detailed segmentation analysis, and executive recommendations, visit the PW Consulting research portal and obtain the full Gene Therapy Market report. Equip your team with the intelligence required to convert market momentum into sustainable strategic advantage.
Gene Therapy Market
For detailed analysis of this topic, please visit the official page: Gene Therapy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


