



PW Consulting: Last Mile Delivery Market to Hit $353.57M by 2032 at 9.8% CAGR

Last Mile Delivery Market Outlook 2026: Navigating Growth, Complexity and Strategic Opportunity
The last mile delivery sector stands at a decisive inflection point. As urban commerce accelerates and consumer expectations converge around speed, transparency and reliability, the operational layer that moves goods from local depots to end recipients is no longer a cost center to be minimized. It is a competitive battleground that shapes brand loyalty, margin structures and geographic expansion. Our latest market research on the Last Mile Delivery Market translates this complexity into a structured, decision-ready intelligence framework designed explicitly for leaders planning their 2026 operating and investment strategies.
This research is built for executives who need to move beyond headline market narratives. It maps the trajectory of the sector through a rigorous historical-to-forecast lens, anchors growth assumptions in verifiable market sizing, and then unpacks the operational, competitive and regulatory forces that will separate resilient operators from those forced into reactive positioning. The objective is straightforward: provide a precise enough view of where the market is heading to inform capital allocation, partnership evaluation, technology roadmapping and regional prioritization, while deliberately leaving the most granular breakdowns for the full report.
Market Trajectory and the Strategic Context for 2026
Over the past five years, the last mile delivery market has demonstrated a consistent expansion trajectory thatoutpaces many adjacent logistics segments. Historical market sizing from 2020 through 2025 reflects a compound growth pattern shaped by e-commerce penetration, retail network reconfiguration and the normalization of same-day and next-day fulfillment expectations. From a base of approximately 115.2 million USD in 2020, the market expanded steadily year over year, reaching an estimated 183.76 million USD by 2025. This historical run-rate sets the foundation for the forward-looking period, and the forecast horizon through 2032 signals that the sector is not merely sustaining momentum but accelerating it.
The projected compound annual growth rate of 9.8 percent across the forecast window positions last mile delivery as one of the more structurally attractive segments within the broader logistics and supply chain ecosystem. Growth is not uniform across time or geography, and the report treats that heterogeneity as a strategic variable rather than background noise. By 2026, market sizing moves to an estimated 204.78 million USD, and forward projections extend upward through the early 2030s, with the trajectory reflecting the combined effects of volume expansion, vehicle and technology mix evolution, and service model diversification. The strategic implication for 2026 planning is clear: organizations that treat last mile delivery as a fixed-cost operational function will face a widening gap relative to competitors who design their networks around scalable, data-driven cost-to-serve models.
For decision-makers, the most valuable lens is not the size of the market alone, but the structure of participation within it. The report examines market concentration patterns that illustrate how value is distributed across incumbents, technology-forward platforms and specialized regional operators. This concentration context matters because it informs realistic expectations around vendor leverage, partnership competition, pricing power and the likelihood of consolidation. Rather than presenting a simple leaderboard, the analysis situates concentration within the operational realities of routing optimization, workforce management, regulatory exposure and customer communication expectations that now define competitive parity.
What the Research Delivers: An Executable Intelligence Framework
This market research is structured as a practical instrument for strategy, operations and investing teams, not merely a descriptive overview. The report combines market sizing, forecast modeling and segmentation analysis with a detailed mapping of competitive offerings, recent corporate activity and the operational forces reshaping cost and service economics. The intent is to provide a common factual foundation that can support scenario planning, vendor evaluation, market entry analysis and operational redesign.
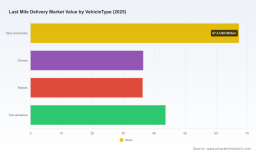
The segmentation architecture explores how the market decomposes across vehicle types, service approaches, delivery models and end-use applications. These dimensions are analyzed to surface where operating economics diverge, where technology adoption is driving measurable efficiency gains, and where structural headwinds or regulatory pressure may alter the attractiveness of specific pathways. Regional splits are examined to reflect differences in urban density, infrastructure readiness, labor market dynamics and consumer purchasing behavior. The analysis is deliberately framed to show how each segment influences cost structures and service feasibility, so that leaders can assess where their own operating model is most exposed or most advantaged.
Beyond segmentation, the report delivers a detailed competitive landscape that profiles leading platforms and logistics software providers. These profiles are built around real operating capabilities rather than marketing positioning, covering route optimization logic, real-time visibility, dispatch and courier network management, exception handling, customer communication and integration patterns. The research also tracks recent corporate developments that signal how capital and partnerships are being deployed to reshape competitive positioning. These developments include major acquisition activity, cross-market expansion moves, same-day shipping partnerships and capacity-strengthening transactions. Read together, they reveal where incumbents are reinforcing their networks, where technology platforms are pursuing scale, and where consolidation is likely to alter procurement and partnership options.
The research also integrates the operating conditions that determine whether growth translates into profitable execution. Labor economics remain a central pressure point, with workforce costs representing a substantial share of total last mile expenses and express delivery commanding premium wage structures. At the same time, regulatory attention is intensifying around urban delivery facilities, truck emissions, subcontracted labor models and local traffic management. Cities are expected to impose stronger restrictions on delivery traffic over the coming years, creating a structural tension between rising parcel volumes and sustainability and access constraints. Energy costs, labor availability and the disproportionate operating cost burden associated with the final delivery stage all reinforce a central point: volume growth alone does not guarantee margin expansion. The report uses these dynamics to help leaders identify where operational redesign, automation, route density improvement and network orchestration can materially shift cost-to-serve outcomes.
Importantly, the report maintains a disciplined boundary between public-facing industry context and proprietary analytical depth. High-level market sizing, concentration indicators and segment architecture provide a strong directional foundation, while the finer breakdowns in regional share, application-level value, vehicle-type splits and company-level benchmarking are reserved for the full study. This design allows executive readers to immediately grasp the strategic shape of the market while preserving the report's differentiated data as a reason to engage with the complete intelligence package.
Strategic Decisions the Report Is Built to Inform
The research is organized around several high-stakes decisions that leaders are actively facing for 2026 and adjacent planning cycles. First, it supports market prioritization logic by clarifying how growth patterns, concentration and operating conditions differ across geographies and usage contexts. For organizations evaluating new regional entry, expansion sequencing or capacity investment, the report provides a framework for weighing demand momentum against infrastructure readiness, labor dynamics and regulatory friction.
Second, the analysis is built to support technology and vendor strategy. As last mile operations become more dependent on routing intelligence, real-time visibility and customer-facing communication, the choice of platform or orchestration layer increasingly determines service consistency and operational flexibility. The competitive profiles and operating capability comparisons help teams assess which solution characteristics matter most for their delivery model, fleet composition, courier network structure and exception-management requirements.
Third, the research informs partnership and procurement planning in a period of active consolidation. Recent acquisition activity and partnership announcements in the broader delivery ecosystem signal that the vendor landscape is changing quickly. For operators negotiating routing software, courier networks, fulfillment partnerships or capacity agreements, the report provides context on where capabilities are being combined, where scale is being accumulated, and where competitive tension may create better negotiating positions or, conversely, reduce alternative sourcing options.
Last Mile Delivery Market
Fourth, the study is designed to support cost and service trade-off analysis. Because labor intensity, traffic restrictions, energy expenses and density variability all influence profitability, leaders need a structured way to evaluate where service-level commitments are economically sustainable and where operational redesign is necessary. The report frames these trade-offs without over-simplifying them, allowing executives to identify the levers most relevant to their own network design, vehicle mix and service promises.
Same-day Delivery Market
How to Use This Research for 2026 Planning
The strongest value of this research emerges when it is used as a shared reference point across strategy, operations, procurement and technology teams. Rather than treating market growth as a single metric, leaders can use the report to align on the underlying drivers that make growth achievable or risky in specific contexts. That includes differentiating between demand-led expansion and capacity-led expansion, between technology-enabled efficiency and labor-dependent service models, and between regions where regulatory and infrastructure conditions support rapid scaling versus those where access and cost pressures require more cautious sequencing.
For capital planning, the report supports more disciplined scenario construction by linking historical growth, forecast momentum and concentration patterns to realistic assumptions about vendor selection, partnership availability and operating cost behavior. For operational planning, it helps identify where route optimization, visibility, customer communication and exception management are likely to remain differentiators rather than table stakes. For corporate development and partnership teams, the recent activity tracked in the research offers a practical lens on where consolidation and capability accumulation are reshaping the competitive map.
The analysis also encourages leaders to think in terms of resilience rather than optimization alone. In a market where parcel volumes continue to rise while regulatory, labor and access constraints intensify, the most durable operating models are those that can adapt vehicle mix, dispatch logic, customer communication and network density without sacrificing service reliability. The research provides the factual scaffolding needed to evaluate where that adaptability is already present and where it must be built.
Accessing the Full Intelligence
The overview presented here establishes the strategic shape of the last mile delivery market, surfaces the core operating and competitive dynamics shaping 2026 decisions, and frames the decisions the full research is designed to support. What it does not attempt is to extract the complete segmentation detail, company-level benchmarking, regional value breakdowns or proprietary analytical conclusions that give the study its decision-grade specificity. Those elements are preserved in the full report so that executives, analysts and operating leaders can work from a precise, internally consistent dataset rather than a generalized summary.
For teams that need to allocate budget, select vendors, prioritize markets, assess partnership options or redesign cost-to-serve logic in the current environment, the full research offers the depth required to move from directional awareness to concrete action. The objective of this introduction is to give you enough substantive insight to recognize the analytical rigor behind the study, while maintaining the core data and differentiated findings as a reason to access the complete market research directly.
If your 2026 planning depends on a clear, evidence-based view of where last mile delivery is heading and how leading operators are repositioning around it, the full report provides the structured intelligence necessary to make those choices with confidence.
For detailed analysis of this topic, please visit the official page: Last Mile Delivery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


