



PW Consulting: Garbage Disposer Market to Reach $302.53 Million by 2032, 5.0% CAGR

Navigating the Garbage Disposer Market: Strategic Intelligence for 2026 and Beyond
The global waste management landscape is undergoing a structural transformation, driven by tightening environmental regulations, evolving consumer expectations, and rapid technological integration across residential and commercial kitchen ecosystems. At the center of this shift lies the garbage disposer market, a category that has quietly transitioned from a basic utility fixture to a strategically relevant component of sustainable infrastructure and appliance portfolios. As organizations map out capital allocation, product development pipelines, and regional expansion strategies for 2026, the need for precise, forward-looking market intelligence has never been more critical.
Our latest market research initiative delivers a comprehensive, data-grounded assessment of the garbage disposer industry, designed specifically to support executive decision-making, competitive positioning, and risk-managed growth planning. This overview outlines the strategic architecture of the study, highlights the macro-economic trajectory shaping the sector, and demonstrates how the full intelligence suite can be deployed to accelerate 2026 strategic execution.
Market Trajectory and Macro-Economic Context
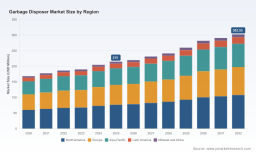
The garbage disposer market has demonstrated consistent, measurable expansion over the past half-decade, reflecting broader trends in residential renovation, commercial kitchen upgrade cycles, and municipal waste diversion mandates. Historical performance from the early 2020s through the base year of 2025 reveals a steady revenue climb, supported by both replacement demand and incremental new installations across mature and emerging consumer markets.
Looking ahead, the forecast period spanning 2026 through 2032 projects a compound annual growth rate of approximately 5.0 percent. This trajectory is anchored by several converging forces: sustained housing and remodeling activity, growing adoption of high-rotation-speed disposal units that align with advanced wastewater treatment capabilities, and regulatory tailwinds that favor on-site food waste reduction over landfill dependency. Revenue forecasts across the horizon indicate a clear upward inflection, with market size expanding from the 2026 baseline toward a materially larger footprint by the early 2030s.
For strategic planners, this growth profile is not merely a top-line statistic. It signals a market that is scaling predictably enough to justify product investment and distribution expansion, yet dynamic enough to reward players who can accurately segment demand, anticipate regulatory shifts, and align product engineering with end-user performance expectations. Understanding where value is created across this expansion window is essential for prioritizing R&D budgets, setting pricing architectures, and determining go-to-market timing.
Structural Drivers Shaping Competitive Positioning
The contemporary garbage disposer market is being reshaped by a blend of environmental policy, infrastructure capability, and consumer preference evolution. Municipal solid waste management continues to face mounting pressure, with food waste representing a significant share of landfill volume and contributing disproportionately to methane emissions. This reality has elevated disposal units from convenience appliances to recognized components of broader waste diversion strategies.
Simultaneously, wastewater treatment infrastructure in many regions has advanced to the point where disposed food waste can be processed into renewable energy and nutrient-rich byproducts. This closed-loop potential strengthens the environmental case for disposer adoption and provides a regulatory and sustainability narrative that manufacturers, distributors, and commercial facility operators can leverage in their positioning. Government initiatives that promote sustainable waste management practices further reinforce procurement preferences for higher-rotation, higher-efficiency units capable of processing a broader range of organic waste with reduced clogging and maintenance overhead.
On the commercial and residential installation side, total project economics remain a critical decision factor. Professional replacement and installation workflows carry meaningful cost considerations, and end-user sensitivity to leak prevention, code compliance, and long-term reliability continues to influence brand selection and channel partnerships. These dynamics create an environment where product durability, service network strength, and installer education become differentiators as important as unit-level specification sheets.
For 2026 strategy teams, these drivers translate into several actionable imperatives: aligning product roadmaps with sustainability messaging that resonates with both regulators and end-users, evaluating pricing and installation-service bundling opportunities, and preparing for regulatory environments that may accelerate adoption in specific jurisdictions while constraining less efficient legacy technologies in others.
Competitive Landscape and Corporate Strategy Signals
The market features a diverse set of established appliance manufacturers, specialized disposal producers, and plumbing fixture brands that compete across residential and commercial segments. Competitive differentiation is increasingly rooted in technology integration, acoustic performance, connectivity and serviceability features, and the ability to embed disposal solutions within broader kitchen or facility equipment ecosystems.
Market concentration remains moderately fragmented, with leading players holding a combined share that leaves substantial room for regional specialists, niche innovators, and portfolio-integrated appliance brands to compete on specific value propositions. This structure encourages continuous feature evolution and creates a landscape where strategic partnerships, channel alignment, and brand positioning can be as impactful as volume production scale.
Several incumbents have demonstrated how targeted portfolio moves and product launches can recalibrate market expectations. InSinkErator, recognized as the world's largest manufacturer of food waste disposers, continues to emphasize multi-stage grinding architectures, sound-dampening engineering, and simplified connectivity features across its residential and commercial lines. Recent catalog and point-of-sale material releases have highlighted next-generation disposer designs alongside integrated hot water tap offerings, signaling a broader push toward kitchen experience enhancement rather than isolated appliance performance.
Whirlpool Corporation leverages its global production and distribution footprint by integrating food waste disposers into a wider kitchen appliance portfolio, enabling cross-selling opportunities and unified service narratives across installed bases. Anaheim Manufacturing Company operates through the Waste King brand, delivering a full line of residential and commercial disposers that emphasize durability and broad performance coverage. Moen Incorporated positions garbage disposals within its plumbing fixture ecosystem, aligning disposal offerings with faucet and sink configurations for residential kitchen projects. GE Appliances maintains continuous-feed disposal options within its home appliance lineup, drawing on brand recognition and install-base familiarity. Joneca Company, LLC focuses on high-quality residential and commercial disposers and adjacent kitchen appliance products, while Franke Management AG targets premium disposal solutions for European and global residential markets, underlining the importance of regional design expectations and finish integration.
On the commercial side, Salvajor specializes in commercial-grade garbage disposals and food waste systems, addressing high-throughput environments where reliability, service intervals, and compliance with commercial kitchen standards are decisive procurement factors.
These corporate profiles illustrate a market where competitive advantage is built through a combination of product engineering, channel strength, brand trust, and segmentation focus. For 2026 planning, the strategic question is not simply who holds share today, but which players are best positioned to capture demand shifts arising from regulatory momentum, installer preferences, and commercial facility upgrade cycles.
Beyond established players, the market is also being influenced by discrete operational events that signal where management attention is flowing. Recent catalog launches, updated point-of-sale materials, and product showcase initiatives indicate intentional efforts to reset buyer expectations around performance, aesthetics, and integrated kitchen solutions. These moves often precede broader pipeline changes, making them valuable leading indicators for competitive monitoring and benchmarking.
Garbage Disposer Market
Worldwide Kitchen Food Waste Disposal Machine Market
What the Full Research Study Delivers
This market study is structured to move beyond surface-level sizing and provide an operational intelligence framework that strategy, finance, and product teams can apply directly. The analysis integrates historical performance, forward forecasts, segmentation logic, competitive profiling, and industry context into a single decision-support architecture. The objective is to equip stakeholders with a clear line of sight from macro trends to segment-level implications, without relying on assumptions that rapidly age out of relevance.
The report unpacks the demand environment across residential and commercial use cases, examining how installation behavior, replacement cycles, end-user priorities, and commercial throughput requirements shape volume distribution. It evaluates the type-level composition of the market, highlighting how performance characteristics, material considerations, and application fit influence adoption patterns and price sensitivity. Regional analysis is presented with an emphasis on structural demand drivers, infrastructure readiness, and market maturity differentials, allowing planners to assess where growth is most durable and where execution risk is highest.
Competitive intelligence sections profile the major participants, mapping their product architectures, brand positioning, channel dynamics, and recent strategic actions. This enables benchmarking of feature sets, identification of whitespace opportunities, and assessment of how portfolio breadth or specialization affects competitive resilience. The study also incorporates regulatory and environmental context, including waste diversion statistics, methane emission dynamics, and the role of wastewater treatment capabilities in reinforcing the value proposition of modern disposers. Infrastructure and installation economics are addressed as practical planning inputs, ensuring that total cost-of-ownership considerations are reflected in market modeling rather than treated as afterthoughts.
Importantly, the research framework is designed to support multiple internal use cases. Corporate development teams can use it to evaluate partnership and acquisition targets. Product leaders can use it to prioritize feature investment and specification roadmaps. Sales and marketing organizations can use it to shape channel messaging and installer engagement programs. Finance and strategy functions can use it to stress-test revenue scenarios and align capacity planning with demand inflection points.
Implications for 2026 Strategic Decision-Making
As organizations finalize 2026 plans, the garbage disposer market presents a clear test of strategic discipline. Growth is forecast to continue at a steady pace, but the distribution of that growth across segments, regions, and application types will reward those who can translate market-level trends into targeted execution. The firms that outperform will be those that connect product performance, installer relationships, sustainability positioning, and commercial service reliability into a coherent value proposition.
Several strategic questions should guide internal planning. How does the organization intend to position against both portfolio-integrated appliance brands and specialized disposer manufacturers? Which performance attributes and installation-service factors most influence purchase decisions in the target segment, and how should messaging and channel incentives be structured around them? Where do regulatory and infrastructure trends create the strongest adoption pull, and how should go-to-market resources be weighted across regions with differing maturity levels? How should product engineering and warranty/service strategies evolve to reduce total cost-of-ownership concerns and strengthen long-term brand trust?
Addressing these questions requires market intelligence that is both credible and actionable. Macro-level sizing and growth expectations provide the strategic backdrop, but the real planning advantage comes from understanding the segmentation logic, competitive dynamics, and industry context that determine where share gains are achievable and where defensive positioning is necessary.
Accessing the Full Market Intelligence
This overview has outlined the strategic contours of the garbage disposer market and demonstrated how the full research study is designed to support 2026 decision-making across product, commercial, and corporate functions. The complete report provides the detailed segmentation analysis, competitor benchmarking, regional structural assessment, and scenario-ready forecasting that executives and planners need to move from broad trend awareness to precise strategic action.
Readers seeking the full dataset, segment-level breakdowns, company profiles, and forward-looking modeling can access the complete market research through our official publication channel. The comprehensive study is built to serve as a working intelligence asset throughout the planning cycle, enabling teams to validate assumptions, compare strategic options, and align execution with the most reliable view of market direction available.
For organizations preparing to invest, expand, reposition, or defend in the garbage disposer market, the difference between reactive planning and strategic advantage lies in the depth and reliability of the intelligence underpinning decisions. The full report delivers that foundation, and it is available now for teams ready to translate market insight into 2026 execution.
For detailed analysis of this topic, please visit the official page: Garbage Disposer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


