



PW Consulting: AAC Market to Hit $359.4M by 2032 on 6.98% CAGR

Navigating the Next Wave: Strategic Intelligence for the Autoclaved Aerated Concrete Market (2026–2032)
The built environment is undergoing a structural realignment. Decarbonization mandates, shifting material cost dynamics, and an accelerating preference for lightweight, high-thermal-performance solutions have propelled Autoclaved Aerated Concrete (AAC) from a niche alternative to a mainstream strategic consideration. As corporate decision-makers plan capital allocation, supply chain positioning, and geographic expansion for 2026 and beyond, the AAC market has emerged as a critical intersection of construction demand, regulatory tailwinds, and operational efficiency gains. Our latest research publication provides a comprehensive, decision-grade mapping of this trajectory across the forecast horizon through 2032.
The foundation of this outlook is built on a clear historical arc. From a base of USD 178.5 Million in 2020, the market progressed to USD 227.8 Million by 2025, reflecting compounding annual growth even amid intermittent supply chain friction and raw material price volatility. Moving into the forecast period, the trajectory accelerates into a robust growth corridor, with the market expected to cross the USD 244.0 Million threshold in 2026, continue upward through the mid-to-late 2020s, and approach USD 359.4 Million by 2032. Underlying this expansion is a forecast-period CAGR of 6.98 percent, a figure that signals sustained, structurally supported demand rather than a short-lived cyclical spike. For executives evaluating capacity planning, technology licensing, distributor partnerships, or regional entry strategies, these macro indicators establish the baseline for scenario modeling and investment prioritization.
Yet macroeconomic aggregates alone do not dictate competitive success. The strategic value of this research lies in its translational architecture: rather than presenting abstract totals, the study decomposes growth drivers into actionable dimensions that align with corporate planning cycles. Decision-makers are guided through a structured evaluation of how market momentum bifurcates across product formats, end-use applications, and regional ecosystems, enabling targeted positioning instead of broad, unfocused exposure. The report is designed to bridge the gap between market observation and execution, translating demand signals into procurement roadmaps, capacity expansion logic, and partnership criteria.
What the Report Delivers: Actionable Intelligence for 2026 Decisions
This publication is structured as an operational toolkit rather than a passive market summary. The analytical framework is engineered to support cross-functional teams—strategy, operations, supply chain, and business development—in validating assumptions and stress-testing strategic initiatives. Key components include:
- Historical Reconstruction and Baseline Calibration: A granular review of market evolution from 2020 through 2025, isolating inflection points, recovery patterns, and the structural factors that shaped volume and value trends. This retrospective anchors all forward-looking estimates and establishes the credibility of the forecast model.
- Forecasting Architecture for 2026–2032: A multi-variable projection framework that incorporates demand-side drivers, supply-side capacity dynamics, and regulatory pacing. The forecast does not rely on linear extrapolation; instead, it integrates sector-specific momentum to map a realistic growth corridor for the next seven years.
- Segment-Level Strategic Decomposition: Detailed analysis across product categories and application verticals, enabling readers to identify where value creation is concentrating, which formats are scaling most efficiently, and how end-use demand patterns are shifting in response to construction practices and building performance expectations.
- Regional Ecosystem Mapping: An assessment of how geographic markets differ in maturity, adoption intensity, regulatory influence, and competitive saturation. The analysis clarifies where demand is emergent, where it is consolidating, and where strategic entry or expansion may yield disproportionate returns.
- Competitive Positioning and Capability Benchmarking: A panoramic view of the operating landscape, including established manufacturers, technology providers, licensed plant operators, and distribution-focused players. Profiles are evaluated against production tenure, geographic footprint, product breadth, and strategic moves that signal future competitive intent.
- Industry Dynamics and Vulnerability Mapping: Targeted examination of the forces shaping margins and operational resilience, including raw material pricing behavior, policy interventions, and certification-driven procurement shifts. These insights allow organizations to anticipate cost pressure, evaluate substitution trends, and align sourcing strategies accordingly.
Collectively, these elements form a decision-support ecosystem. Rather than leaving readers with isolated data points, the report constructs a continuous logic chain: from historical evidence, through structural drivers, to competitive reality, and finally to strategic implication. The objective is to enable leaders to ask sharper questions—about capacity timing, product mix optimization, distributor alignment, and regional prioritization—and to answer them with evidence that withstands scrutiny.
Market Dynamics: Regulatory Acceleration, Material Realities, and Demand Reconfiguration
The AAC market's expansion is not occurring in a vacuum. It is being reshaped by intersecting forces that alter both the demand curve and the cost structure of production. One of the most consequential shifts involves regulatory and certification environments. In several advanced construction markets, green building certification frameworks have increasingly favored materials that combine structural utility with lightweight characteristics and thermal insulation performance. This has translated into higher procurement visibility for AAC within project specification processes, particularly where energy efficiency targets are tightening and where building envelopes must satisfy stricter performance thresholds. Parallel policy mechanisms in parts of Europe have further reinforced this trajectory, as energy codes and retrofit mandates effectively position AAC as a pragmatic solution for both new builds and renovation programs seeking measurable thermal gains.
At the same time, material-side dynamics are introducing a more complex operating environment. The core input architecture of AAC manufacturing—dependent on cement and lime as primary binding agents—remains exposed to pricing volatility. Seasonal fluctuations, regional supply constraints, and broader commodity cycles have periodically pressured input costs, affecting margin stability across block and panel producers. This has elevated the importance of sourcing strategy, formulation flexibility, and vertical coordination for manufacturers seeking to protect unit economics. In certain markets, policy-driven substitution initiatives have begun reshaping input dependency by encouraging alternative material pathways, lowering embodied carbon intensity and altering the traditional cost equation for AAC production. These regulatory and material intersections are not peripheral concerns; they are central to understanding where competitive advantage will be earned or eroded over the forecast period.
Autoclaved Aerated Concrete (AAC) Market
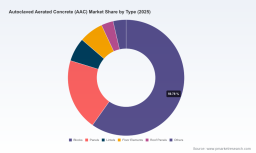
On the demand side, the configuration of end-use adoption is evolving as construction priorities shift. Residential applications continue to reflect substantial demand, supported by housing activity cycles and the material's suitability for efficient wall systems. Commercial development contributes a distinct demand layer, where speed of assembly, weight reduction, and building performance specifications influence material selection. Infrastructure and industrial applications, while representing smaller share tiers in aggregate, introduce specialized requirements that reward product consistency, durability, and tailored engineering profiles. The report evaluates these demand streams not merely as volume contributors, but as strategic segments where specification influence, purchasing behavior, and competitive differentiation diverge meaningfully.
Competitive Landscape: Established Players, Regional Expansion, and Strategic Signaling
The competitive architecture of the AAC market reflects a blend of long-entrenched manufacturers, technology-and-licensing operators, distribution-centric participants, and newer entrants expanding capacity to capture demand momentum. In North America, the landscape is anchored by producers with substantial operational tenure and established supply relationships. One of the region's oldest manufacturers has built a multi-decade presence in AAC blocks and panels, reinforcing channel depth and regional familiarity. Alongside it, another significant North American supplier has sustained production and market participation for over two decades, contributing to a competitive base that values reliability and specification acceptance. More recent activity has also brought newer manufacturing capacity into the region, with production commencing in 2022, signaling that market growth is attracting additional investment rather than consolidation alone.
In Europe, the competitive picture is shaped by a mix of manufacturers, structural system suppliers, and technology providers operating through licensed plant networks. A major Northern European producer has established scale across Estonia and Latvia, positioning itself as a leading regional manufacturer of blocks and panels. In Poland and broader Eastern Europe, additional producers are reinforcing regional supply, while in the UK, a manufacturer and supplier continues to extend structural wall system offerings across domestic and international channels. Technology-and-licensing operators also play an important role, enabling production capacity beyond the boundaries of vertically integrated manufacturers and expanding the market's geographic reach through partnership-based models.
Asia introduces a different dynamic, characterized by capacity expansion and diversified participation. In India, the sector has seen meaningful manufacturing scale-up, with one major producer completing a phased capacity expansion to a substantial annualized volume for blocks, bricks, and panels. Another significant player has moved into AAC production through a dedicated product line launched in 2025, reflecting the strategic use of broader cement and building materials portfolios to enter or deepen participation in lightweight concrete segments. Additional Indian manufacturers continue to build out block and panel output, underscoring the region's role as a focal point for both volume growth and operational scaling.
Distribution-focused participants further complicate and enrich the competitive fabric. In several markets, distributors act as critical intermediaries, sourcing and supplying AAC blocks and panels to construction projects where manufacturing presence may be limited or where project-specific procurement logistics favor intermediary scale. This dual structure—manufacturers building capacity and distributors extending reach—creates multiple pathways for market participation and complicates simplistic views of competitive intensity. The report evaluates these roles in context, highlighting where manufacturing control, technology licensing, or distribution capability constitutes the more decisive strategic asset.
Strategic Implications for 2026 Planning
For organizations entering 2026 with AAC exposure or considering it, the strategic implications fall into several priority areas. First, the growth trajectory justifies disciplined capacity and supply chain planning, but only when paired with segment-specific demand intelligence. Broad market growth does not automatically translate into uniform opportunity across product types or application verticals. Decisions regarding which formats to prioritize, which applications to target, and where to locate or expand production should be informed by the segmentation patterns revealed in the full study.
Second, competitive positioning will increasingly depend on how well firms manage the tension between demand tailwinds and input cost variability. Companies that can stabilize cost structures, optimize formulation strategies, or align sourcing with regional pricing behavior will be better positioned to preserve margins while scaling. Similarly, firms that understand where regulatory and certification pressures are converting into procurement preference will be able to align product specifications and marketing positioning more effectively.
Third, the competitive landscape suggests that market access is not uniform. In some regions, established manufacturing presence, specification history, and channel relationships create meaningful barriers. In others, licensed production models, distributor networks, and new capacity additions are loosening those barriers and opening room for strategic entry. Evaluating which pathway is most viable—direct manufacturing, technology partnership, or distribution alignment—requires a clear view of regional saturation, demand cadence, and incumbent behavior, all of which are examined in depth in the complete report.
Closing Perspective: The Case for Full Intelligence
The AAC market is entering a phase in which strategic advantage will belong to those who can interpret momentum with precision rather than approximation. The headline growth path outlines an attractive opportunity, but the real decision architecture lies beneath it: in the interplay of segment concentration, regional heterogeneity, regulatory pacing, input cost volatility, and competitive maneuvering. This research is built to expose those layers systematically, giving leadership teams a structured basis for planning capital, refining product strategy, and choosing where to commit operational resources.
The analysis presented here is intended as a strategic preview. It establishes the scale, direction, and structural logic of the market, and it highlights the operational realities that will shape execution in 2026 and beyond. For the full segmentation breakdown, regional demand mapping, competitive benchmarking detail, and the complete forecast tables that support internal modeling, we invite you to access the full report. The complete study provides the depth required to convert market visibility into concrete, defensible action.
Worldwide Cellular Concrete Market
For detailed analysis of this topic, please visit the official page: Autoclaved Aerated Concrete (AAC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


