



PW Consulting ESWL Market Hits $381.96M in 2025, Projects 5.5% CAGR to $552.74M by 2032

Strategic Horizons in Extracorporeal Shock Wave Lithotripsy: A 2026 Market Perspective
The global landscape for Extracorporeal Shock Wave Lithotripsy (ESWL) is entering a decisive phase of transformation. As healthcare systems worldwide balance cost containment with the demand for minimally invasive urological interventions, understanding the trajectory of this market is no longer optional for strategic planners—it is imperative. This article serves as an executive overview of our latest comprehensive market research, designed to equip stakeholders with the intelligence needed to navigate the forecast period from 2026 through 2032.
Our analysis indicates that the market is on a steady upward path. Following historical growth patterns observed between 2020 and 2025, where revenue climbed from approximately 294.62 Million USD to 381.96 Million USD, the momentum is expected to continue. The forecast period projects a compound annual growth rate (CAGR) of 5.5 percent. By 2032, the market volume is anticipated to reach significant maturity, driven by technological advancements and shifting clinical preferences. However, raw figures only tell part of the story. The real value lies in understanding the underlying dynamics that will dictate profitability, market share, and operational feasibility for providers and manufacturers alike.
Market Dynamics and Operational Realities
The ESWL sector does not operate in a vacuum. It is influenced by a complex interplay of regulatory frameworks, reimbursement structures, and capital expenditure constraints. Our report dives deep into these friction points to provide a realistic view of market entry and expansion opportunities.
Regulatory and Clearance Milestones
Recent regulatory activities highlight the pace of innovation and the hurdles remaining for new entrants. For instance, recent clearance events have validated new devices under specific federal classifications, signaling both opportunity and heightened scrutiny. The approval of specific lithotripters under Class II regulations demonstrates that while the pathway is established, the bar for clinical efficacy and safety documentation remains high. Companies aiming to launch new units must navigate these regulatory corridors with precision. Our research details the specific implications of these clearances for future product pipelines and competitive barriers.
Reimbursement and Economic Viability
Financial sustainability for ESWL procedures relies heavily on reimbursement codes. The economic environment for 2026 suggests varied payment structures depending on the care setting. National average Medicare payments differ significantly between ambulatory surgical centers and hospital outpatient departments. This disparity influences where providers choose to locate their services and how they structure their billing practices. Understanding the nuances of Current Procedural Terminology codes and their associated payment rates is critical for forecasting net revenue. Our report dissects these reimbursement landscapes to help stakeholders model accurate financial projections.
Capital Investment Considerations
The barrier to entry for ESWL technology remains substantial. Initial capital investment for systems varies widely, ranging from mobile units to stationary configurations. The cost differential between these options impacts hospital budgeting cycles and procurement strategies. Mobile units offer flexibility but may limit throughput, while stationary systems provide stability at a higher upfront cost. Strategic decision-makers must weigh these capital costs against expected utilization rates and maintenance expenses. We provide a granular breakdown of cost structures to assist in capital allocation decisions.
Technology Segmentation and Clinical Application
The market is segmented by technology type and clinical application, each presenting distinct growth vectors. While the overall market expands, specific technologies are gaining traction due to improved precision and reduced complications. Similarly, the prevalence of different stone types dictates where demand will concentrate.
Technology Evolution
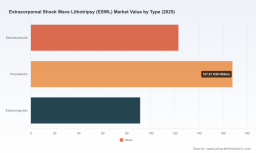
Different shock wave generation technologies compete on efficacy, durability, and cost. The market includes electrohydraulic, piezoelectric, and electromagnetic systems. Each type carries different implications for maintenance, energy consumption, and patient outcomes. Our analysis evaluates the maturity and adoption rates of these technologies across different healthcare settings. We examine how technological shifts are influencing purchasing decisions among major healthcare providers.
Application Diversity
While kidney stones remain the primary driver of demand, other applications are contributing to market expansion. Ureteral stones, pancreatic stones, and salivary stones represent additional revenue streams that are often overlooked in broader analyses. The clinical protocols for these conditions vary, influencing the type of equipment required and the specialist involved. Our report maps the volume and growth potential across these applications, providing a clear picture of where niche opportunities exist.
The competitive landscape is moderately concentrated, with a few key players holding significant market share. This concentration suggests that while there is room for innovation, competitive pressure on pricing and service levels is intense. Our report provides a detailed competitive intelligence section that profiles the strategies of leading manufacturers.
Key Players and Strategic Moves
Several companies are defining the current market standards. German engineering firms have historically held strong positions, leveraging reputation for durability and precision. Simultaneously, manufacturers from emerging manufacturing hubs are increasing their presence through aggressive pricing and rapid innovation cycles.
-
Dornier MedTech: A longstanding participant known for establishing clinical benchmarks in shock wave technology. Their strategy focuses on maintaining high clinical efficacy standards.
-
Karl Storz GmbH & Co. KG: Integrates ESWL solutions within broader endoscopic and urological portfolios, offering bundled solutions that appeal to comprehensive care centers.
-
Siemens Healthineers: Leverages extensive imaging and diagnostic capabilities to enhance the precision of lithotripsy procedures, positioning technology as a integrated diagnostic-therapeutic solution.
-
Shenzhen Wikkon Precision Technologies Co., Ltd.: Represents the growing influence of manufacturers from the Asia-Pacific region. Recent activities indicate a push towards global regulatory approval and branding.
Extracorporeal Shock Wave Lithotripsy (ESWL) Market
Recent Developments and Market Shifts
Recent actions by key competitors signal shifting strategies. In mid-2025, Shenzhen Wikkon Precision Technologies Co., Ltd. achieved a significant regulatory milestone with FDA 510(k) clearance for their U200 Extracorporeal Shock Wave Lithotripter, specifically indicated for kidney stone treatment. This clearance under 21 CFR 876.5990 opens the US market to this specific device. Following this, in late 2025, the company launched a new brand identity and announced global expansion plans during a meeting of the Chinese Urological Association. These moves suggest a deliberate strategy to scale presence in Western markets while consolidating strength in home regions.
However, competition is not limited to these profiled entities. The market concentration metrics indicate that the top three players hold over half of the market revenue, and the top five control approximately 65 percent. This structure implies that market entry for new players requires significant differentiation, either through cost leadership or proprietary technology. Our report analyzes the strategic postures of these leaders to identify potential vulnerabilities and partnership opportunities.
Strategic Imperatives for 2026 and Beyond
As we look toward the forecast period, several key strategic imperatives emerge for stakeholders involved in the ESWL market. Success will depend on the ability to align technology procurement with reimbursement realities, manage capital expenditures efficiently, and adapt to a competitive landscape that is both concentrated and dynamic.
Optimizing Procurement and Deployment
Healthcare providers must look beyond the sticker price of ESWL systems. The total cost of ownership, including maintenance, disposable components, and energy consumption, must be factored into procurement decisions. With capital costs ranging significantly based on system type, facilities need to model their expected patient volume to justify the investment. Our research provides frameworks for calculating return on investment based on procedure volumes and reimbursement rates specific to different care settings.
Navigating Regulatory Pathways
For manufacturers and distributors, the regulatory environment remains a critical gatekeeper. Recent clearances demonstrate that compliance is achievable, but the process requires robust clinical data. Companies planning product launches must anticipate regulatory timelines and prepare corresponding quality management systems. The report outlines the specific regulatory requirements and recent precedents that will shape future approval processes.
Capitalizing on Regional Variances
Market growth is not uniform across geographies. Different regions exhibit varying levels of adoption based on healthcare infrastructure, reimbursement policies, and disease prevalence. While some regions show higher immediate revenue potential, others may offer faster growth rates due to developing healthcare access. Strategic expansion plans should be tailored to these regional characteristics rather than applying a one-size-fits-all approach. Our report includes detailed regional analysis to guide market entry and resource allocation.
Conclusion
The Extracorporeal Shock Wave Lithotripsy market presents a landscape of steady growth tempered by complex operational challenges. With a projected CAGR of 5.5 percent leading into the next decade, the opportunity for value creation is substantial. However, realizing this potential requires more than superficial market knowledge. It demands a deep understanding of reimbursement mechanics, capital constraints, regulatory pathways, and competitive strategies.
This article has provided a high-level overview of the forces shaping the ESWL market. Yet, the true depth of intelligence lies in the data points, specific segmentation values, and detailed company profiles contained within our full report. For executives and investors who need to make precise decisions regarding market entry, product development, or investment allocation, the granular details are essential. We invite you to access the full market research report to uncover the specific data driving these trends. The complete analysis offers the actionable intelligence required to turn market insight into strategic advantage.
Extracorporeal Shock Wave Therapy Device Market
For detailed analysis of this topic, please visit the official page: Extracorporeal Shock Wave Lithotripsy (ESWL) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


