



PW Consulting: Structural Steel Pipe Market to Hit $489.1M by 2032, 3.45% CAGR

Strategic Imperatives in the Structural Steel Pipe Market: Navigating the 2026-2032 Cycle
The structural steel pipe industry stands at a critical juncture as it moves through the 2026 fiscal year. For executives, procurement leaders, and investors, understanding the trajectory of this market is no longer optional—it is a prerequisite for resilient supply chain design and capital allocation. Our latest market research delivers a comprehensive examination of the forces shaping demand, pricing, and competitive positioning across the global structural steel pipe landscape. This introduction outlines the strategic value embedded in the full report, highlights the macro trends that demand attention, and explains how data-driven foresight can convert market volatility into competitive advantage.
The Macro Trajectory: Recovery, Expansion, and Measured Growth
Historical data reveals a market that has steadily climbed out of the pandemic-era disruptions and into a phase of structured expansion. Between 2020 and 2025, total market revenue moved from approximately 298.45 million USD to 386.5 million USD, reflecting a compound annual growth rate that underscores the sector's underlying resilience. The upward momentum carries into the forecast window: 2026 opens at an estimated 399.37 million USD, and the trajectory advances toward 489.1 million USD by 2032, supported by a projected CAGR of 3.45 percent.
While these aggregate figures establish the baseline, the real strategic insight lies in understanding why growth is unfolding at this pace and where the inflection points will emerge. The forecast period through 2032 does not imply a straight line. Year-over-year movement shows nuanced fluctuations that reward stakeholders who look beyond headline numbers. Readers who engage with the full report will find a detailed quarter-by-quarter and year-by-year narrative that connects macroeconomic signals—such as interest rate environments, infrastructure appropriations, and industrial construction cycles—to the demand patterns driving pipe procurement across multiple downstream sectors.
Diversified Demand Centers and the Changing Application Mix
Structural steel pipe is no longer a single-purpose commodity. Its deployment spans oil and gas infrastructure, commercial and civil construction, water and wastewater systems, and an expanding set of industrial applications that rely on high-integrity tubular products. The market's breadth means that shifts in any one vertical can materially alter procurement strategies, inventory planning, and pricing negotiations.
Our research dissects the application landscape without reducing it to simplistic rankings. The full report maps how project pipelines, regulatory mandates, and regional infrastructure spending are redistributing demand across use cases. It also examines the degree to which certain applications are becoming more cyclical while others exhibit steadier, policy-driven consumption. For executives planning multi-year supply agreements or evaluating capacity investments, this granularity matters. It allows organizations to anticipate which segments will tighten during downturns and which will remain robust, enabling more precise hedging of procurement exposure.
Equally important is the interplay between application demand and product type. Seamless pipes, welded pipes, and spiral welded variants each serve distinct performance and cost profiles. The report analyzes how engineering requirements, cost pressures, and manufacturing capabilities are shaping the adoption mix across these categories. Decision-makers who understand these dynamics can better align sourcing strategies with technical specifications, avoiding over-specification in cost-sensitive programs or under-specification in high-stress applications.
Geographies in Motion: Regional Dynamics That Reshape Sourcing
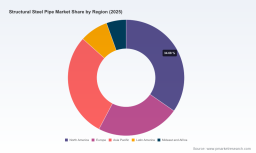
No market analysis is complete without a rigorous view of regional performance. The structural steel pipe market reflects divergent economic conditions, trade policies, and construction cycles across North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa. Each geography carries its own set of demand drivers, supply constraints, and policy risks that directly influence landed costs and availability.
In the full report, we avoid surface-level regional snapshots. Instead, we provide an integrated assessment of how cross-border trade flows, local production capacity, and infrastructure investment programs interact to create pricing divergence and availability gaps. This regional lens is especially valuable for multinational operators and distributors who must coordinate procurement across multiple markets. The analysis identifies where local supply is tightening, where import dependency creates exposure, and where domestic production is gaining strategic importance. Readers will see how these regional conditions translate into actionable sourcing recommendations rather than abstract market commentary.
Competitive Landscape: Vertically Integrated Leaders and the Battleground for Share
The competitive structure of the structural steel pipe market is defined by a mix of large, globally integrated steelmakers and specialized domestic producers with strong regional footprints. Market concentration remains moderate, with the top three firms holding approximately 25.8 percent of revenue and the top five reaching 32.4 percent. This structure suggests that while scale confers advantages, there is meaningful space for regional specialists to compete on service, lead times, and product specificity.
Nucor, headquartered in Charlotte, North Carolina, exemplifies the vertically integrated approach. As an electric arc furnace producer of domestic hollow structural sections and tested steel pipe—covering ASTM A500, A135/A795, and A53 specifications—Nucor has positioned itself around low-embodied carbon certification and domestic supply reliability. That positioning has translated into conspicuous pricing activity: in October 2025, the company announced a 50 USD per ton increase across tube steel, HSS, mechanical, and piping products, followed by a further 60 USD per ton increase implemented in February 2026. These moves signal not only cost pass-through but also a deliberate effort to protect margin in an environment where input costs and demand are both elevated.
ArcelorMittal, based in Luxembourg City, remains a global force in tubular products, producing high-strength structural steel pipe and welded pipes for infrastructure and energy applications. Its recent product development activity highlights the innovation dimension of competition: by May 2026, ArcelorMittal Nippon Steel India had commenced commercial production of EQ70 grade high-strength welded steel pipes with a 690 MPa yield at its Hazira mill, enabling weight savings in structural applications. Such advances illustrate how competitors are using grade differentiation and performance improvements to capture premium segments, rather than competing solely on volume.
Structural Steel Pipe Market
United States Steel Corporation, headquartered in Pittsburgh, continues to supply welded and structural steel pipe and tubing critical to construction and infrastructure programs. Meanwhile, California Steel Industries, based in Fontana, serves the western United States with ERW structural steel pipe and tubing for load-bearing and low-pressure applications. These regional specialists matter because they shape localized availability and lead time dynamics. In February 2026, structural tubing mills broadly extended lead times to 6–8 weeks amid rising pricing and demand—an industry-wide signal that procurement planning horizons must lengthen and inventory buffers may need recalibration.
The full report goes deeper into how these players—and the broader field—compete on pricing, product certification, lead time reliability, and sustainability credentials. It evaluates where vertical integration provides genuine insulation from input volatility and where it may create rigidity. It also examines how low-embodied carbon positioning is becoming a differentiator in bids where procurement teams are weighing total cost of ownership against decarbonization commitments.
Forces Reshaping Cost Structures and Pricing Power
Pricing in the structural steel pipe market is being influenced by a convergence of cost pressures, trade policy, and demand timing. Raw material and labor dynamics remain central. In the first quarter of 2026, steel scrap prices stayed firm to upward, with China pricing at 347.20 USD per metric ton and India at 397.20 USD per metric ton. These levels were supported by tight supply and higher freight costs, reinforcing the upward bias in producer input costs and constraining the ability of mills to absorb cost shocks without passing them downstream.
Trade policy has added another layer of complexity. Section 232 tariffs on steel imports were raised to 50 percent in June 2025 and affirmed in April 2026, applying directly to steel pipe and structural products. In parallel, Section 301 tariffs on steel pipe, tube, and structural shapes from excess-capacity countries continued to impact import costs as of May 2026. Together, these measures have altered the relative attractiveness of imported versus domestic supply, tightened available sourcing channels, and strengthened the pricing hand of domestic producers in certain markets.
The price environment has responded accordingly. Steel pipe and tube prices rose 12.5 percent year-over-year in spring 2026, with the producer price index for metals reaching 354.9 in March 2026. These movements matter for budgeting, bidding, and contract structuring. For buyers, they raise the stakes of contract timing, escalation clauses, and inventory strategy. For producers and distributors, they create opportunities to defend margins but also increase the reputational and operational risks associated with lead time reliability and service continuity.
The report provides a structured framework for interpreting these dynamics. It connects raw material indices, tariff timelines, and demand seasonality to practical forecasting tools that help organizations model price scenarios, evaluate make-versus-buy trade-offs, and design procurement contracts that share risk more intelligently. Rather than simply documenting that prices have risen, it explains the mechanisms behind the increases and the conditions under which they may ease or intensify.
What the Full Report Delivers: Operational Intelligence for 2026 and Beyond
This introduction provides the strategic framing; the complete report delivers the operational intelligence required to act on it. Designed for executives, category managers, supply chain planners, and investors, the study translates market data into decision-ready formats. Key content includes a detailed historical reconstruction from 2020 through 2025, a forward-looking forecast spanning 2026 to 2032, and scenario analyses that stress-test assumptions around input costs, tariffs, and demand cycles.
Readers will find a robust segmentation evaluation covering product types and application verticals, along with a regional assessment that connects local supply conditions to cross-border trade realities. The competitive section profiles major players and analyzes recent moves—including price actions, grade launches, and lead time shifts—that signal where market power is being exercised and where vulnerabilities are emerging. The regulatory and cost environment is examined not as background noise but as an integral input to procurement and investment decisions.
Structural Steel Market
Equally important, the report emphasizes practical application. It outlines how to interpret lead time extensions, how to evaluate the implications of tariff structures on total landed cost, and how to incorporate sustainability credentials into sourcing criteria without losing sight of cost and performance. It also provides the analytical scaffolding needed to anticipate where the market is likely to tighten or loosen over the forecast horizon, giving stakeholders a basis for proactive rather than reactive planning.
Why This Research Matters Now
The structural steel pipe market in 2026 is defined by strong but uneven growth, elevated input costs, shifting trade policy, and a competitive field in which both global scale and regional agility matter. Organizations that treat these conditions as isolated events risk mispricing risk and misaligning supply strategies. Those that integrate them into a coherent, data-backed view can make better decisions on contracting, inventory, capacity, and market entry.
The complete report is built to support that integration. It combines the macro trajectory—moving from 386.5 million USD in 2025 toward 489.1 million USD by 2032 at a 3.45 percent CAGR—with the granular, decision-level detail that turns numbers into strategy. For teams responsible for procurement, planning, or investment in structural steel pipe, the difference between reacting to price spikes and anticipating them can be material.
To access the full segmentation analysis, regional assessments, competitive profiles, and scenario-based forecasts, request the complete market research. The methodology, data tables, and actionable recommendations are structured to give your organization a clear line of sight from market intelligence to executive decision-making in 2026 and across the forecast period to 2032.
For detailed analysis of this topic, please visit the official page: Structural Steel Pipe Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


