



PW Consulting Projects 9.5% CAGR for High Speed Oven Market to Hit $7.88B by 2032

Strategic Intelligence for the High Speed Oven Market: Navigating the 2026–2032 Growth Cycle
The commercial foodservice sector is undergoing a profound operational transformation, driven by acute labor constraints, rising real estate costs, and an unprecedented demand for rapid ticket-to-order fulfillment. In this volatile environment, the high speed oven market has emerged as a critical enabler of kitchen efficiency, bridging the gap between traditional cooking methodologies and the aggressive throughput requirements of modern quick-service and fast-casual operations. As we analyze the trajectory of this sector through 2032, our latest market research provides a comprehensive strategic blueprint for manufacturers, investors, and foodservice operators aiming to capitalize on a projected industry expansion. This article outlines the macro-economic foundations of the sector, highlights the competitive dynamics shaping vendor strategies, and details the actionable intelligence embedded within our full report.
The Macro Trajectory: A High-Growth Window Across 2026–2032
Market data spanning the evaluation period paints a clear picture of sustained acceleration. Following a robust historical baseline, the industry has entered a steep growth phase, with the overall market value reaching $4,370.0 million in 2025 before projected to chart $4,686.06 million in 2026. Our forecast models indicate that this momentum will compound consistently, pushing revenue toward $7,880.0 million by 2032. This represents a compound annual growth rate of 9.5 percent, a figure that significantly outpaces broader commercial kitchen equipment benchmarks and underscores a structural shift in how operators are designing their culinary workflows.
The valuation trajectory does not merely reflect cyclical demand; it signals a permanent reorientation of commercial cooking infrastructure. As high-throughput concepts proliferate and legacy kitchen footprints contract, speed cooking appliances are transitioning from supplementary tools to central production assets. Organizations that align their capital expenditure strategies with this growth pattern stand to secure meaningful first-mover advantages in supply chain positioning, channel partnerships, and menu innovation capabilities.
Market Structure and Demand Drivers Shifting the Landscape
Segmentation Dynamics and End-Use Priorities
The current market architecture reveals a balanced but rapidly evolving distribution of demand across equipment configurations and deployment environments. Operators are increasingly evaluating built-in installation formats against standalone countertop solutions, with the strategic choice heavily dependent on modular kitchen design, ventilation constraints, and throughput targets. Simultaneously, end-use applications are bifurcating between high-volume restaurant environments and a diverse array of other commercial deployments, including corporate cafeterias, educational dining facilities, retail food halls, and airport concessions. This diversification is critical, as it insulates the market from overreliance on a single dining segment and broadens the addressable customer base for manufacturers and distributors.
Geographic Expansion and Infrastructure Maturation
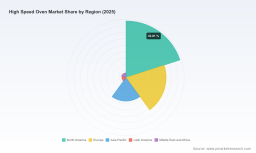
Regional adoption patterns are stabilizing around established commercial foodservice hubs while demonstrating clear upward pressure in emerging markets. North American and European territories continue to anchor substantial share, anchored by mature restaurant supply chains, stringent health and safety compliance frameworks, and widespread adoption of ventless and impingement cooking technologies. Meanwhile, Asia Pacific and Latin American markets are exhibiting accelerating deployment rates as quick-service brands expand internationally and local operators prioritize operational efficiency to offset rising commodity and labor costs. Middle Eastern and African regions, though smaller in absolute valuation, are carving out niche growth corridors driven by hospitality infrastructure projects and tourism-centric foodservice concepts.
Regulatory Compliance and Operational Cost Pressures
The commercial deployment of high speed ovens is strictly governed by a multi-layered certification ecosystem. Equipment destined for U.S. and Canadian commercial kitchens must satisfy UL and NSF safety and sanitation standards, while ETL certification remains mandatory for market entry across North America. Ventless configurations introduce an additional compliance layer, requiring catalytic converter certification to meet stringent emissions thresholds. Furthermore, energy efficiency frameworks, including Energy STAR and related efficiency certifications, are increasingly influencing procurement decisions, particularly for models that integrate convection, microwave, and broil capabilities in a single footprint.
Worldwide Build-in High Speed Oven Market
Beyond regulatory overhead, labor economics are the most potent demand catalyst in the current cycle. High speed ovens routinely deliver cook times up to 80 percent faster than conventional equipment, directly compressing staffing requirements and reducing dependency on highly specialized culinary labor. In an environment where wage inflation and recruitment volatility remain unresolved, this labor efficiency premium is no longer a convenience feature—it is a financial imperative that dictates capital allocation and menu engineering strategies.
High Speed Oven Market
Competitive Arena: Strategic Moves and Product Evolution
Market concentration remains firmly consolidated, with the top three participants commanding a combined 62 percent share and the top five firms extending that footprint to 65 percent. This structure rewards scale, technical differentiation, and robust service networks, while simultaneously raising the barrier for new entrants attempting to disrupt established channel relationships.
Several active manufacturers are currently defining the competitive tempo through targeted product evolution and strategic positioning. Prática Klimaquip, operating out of Minas Gerais, Brazil, has solidified its footprint in commercial rapid-cook applications with stackable configurations such as the FIT XL and Rocket Express, specifically engineered for pizza, wing, and quick-service workflows. The Middleby Corporation, leveraging its TurboChef Technologies subsidiary based in Elgin, Illinois, continues to deploy impingement-based rapid-cook architecture optimized for high-volume foodservice throughput. Hatco Corporation, through its Ovention Ovens brand in Milwaukee, Wisconsin, maintains a strong emphasis on 100 percent ventless impingement systems that integrate seamlessly into constrained kitchen footprints without extensive exhaust infrastructure.
Merrychef Ltd., headquartered in Elkhart, Indiana, remains a pioneer in high-speed oven technology, with its eikon and conneX series reflecting a consistent focus on streamlined kitchen operations and connectivity-driven workflow management. Panasonic Corporation, from its Osaka base, extends its commercial reach through convection-microwave-broil hybrids such as the NE-SCV3 series, targeting restaurants and cafes that require multi-functionality within a single appliance footprint. UNOX S.p.A. contributes a distinct European engineering perspective from Italy, offering commercial speed ovens such as the SPEED.Pro line that merge convection, steam, and microwave capabilities for versatile culinary outputs. Sharp Corporation has also entered the acceleration curve with its Celerity high speed oven, showcasing advanced thermal engineering capable of reducing whole-chicken cook times to roughly one-third of conventional methods. Additionally, Buffalo Equipment has expanded its proprietary portfolio by unveiling two new high-speed models, reinforcing the trend of domestic and regional manufacturers investing heavily in rapid-cook technology differentiation.
2026–2027 Product Cycle: Real-Time Market Signals
The competitive landscape is being actively reshaped by a concentrated wave of product launches, catalog updates, and application-focused messaging during mid-2026. Ovention Ovens recently refreshed its product catalog with detailed guidance on integrating high-speed ovens into modular kitchen designs and optimizing team workflow allocation. TurboChef simultaneously promoted its Bullet Oven for campus dining environments and high-volume service settings, emphasizing throughput efficiency and space-conscious deployment. Merrychef announced an expansion of its conneX high-speed oven range, positioning the new line as a solution for consolidated kitchen operations and reduced equipment sprawl. Buffalo Equipment followed with the unveiling of two new models within its branded cooking range, signaling continued investment in rapid-cook capacity across retail and foodservice channels. These concurrent developments reflect a broader industry pivot toward operational modularity, deployment flexibility, and menu-agnostic performance.
Inside the Report: Operational Intelligence and Decision Frameworks
Our full market research publication extends well beyond macro-valuation summaries to deliver a tactical decision-support architecture. The report systematically deconstructs market sizing across historical baselines and forward-looking forecast periods, enabling precise revenue modeling and capacity planning. It examines structural segmentation splits that illuminate how built-in versus countertop configurations are performing across distinct commercial environments, while also mapping end-use distribution between restaurant-grade deployments and alternative foodservice applications. Geographic coverage is analyzed through a lens of market maturity, infrastructure readiness, and regional adoption velocity, providing a nuanced view of where demand is stabilizing and where it is accelerating.
The competitive intelligence section profiles active market participants, mapping headquarters locations, technological specializations, and recent developmental activity. Recent product launches, catalog revisions, and targeted promotional campaigns are cataloged to reveal how vendors are responding to shifting operator requirements. Beyond hardware and vendor mapping, the report incorporates regulatory and certification pathways, ensuring that compliance planning is integrated directly into procurement and deployment strategies. Labor cost mitigation scenarios are quantified against conventional cooking benchmarks, and energy efficiency considerations are evaluated alongside certification requirements to provide a complete total-cost-of-ownership perspective. This multidimensional framework is designed to support capital planning, channel strategy formulation, competitive positioning, and menu engineering initiatives with minimal reliance on secondary interpretation.
Strategic Imperatives for Stakeholders
For equipment manufacturers and technology developers, the 9.5 percent growth trajectory and concentrated market share structure underscore the necessity of differentiated engineering, robust ventless and hybrid-cooking portfolios, and proactive compliance alignment. For foodservice operators and franchise groups, the immediate priority lies in evaluating kitchen reconfiguration opportunities that leverage 80 percent faster cook times to compress labor dependency, improve ticket throughput, and expand menu flexibility within constrained footprints. For investors and financial analysts, the diversification across end-use environments and regional growth corridors provides a clear framework for assessing exposure, identifying channel expansion opportunities, and monitoring vendor consolidation patterns. The data demonstrates that high speed ovens are transitioning from tactical kitchen tools to strategic infrastructure assets; companies that embed this reality into their planning cycles will be better positioned to navigate the operational and financial demands of the coming half-decade.
Conclusion: Accessing the Complete Strategic Blueprint
The high speed oven market is entering a phase of sustained, structurally driven expansion marked by technological consolidation, regulatory rigor, and intensifying competitive maneuvering. The aggregate market trajectory, segment dispersion patterns, vendor activity cycles, and compliance frameworks documented in our full research publication provide a comprehensive foundation for informed capital allocation, product planning, and operational optimization. While the overview presented here captures the essential strategic contours, the complete report contains granular sizing breakdowns, detailed vendor profiling, segment-level deployment dynamics, regional adoption mappings, and actionable scenario models that are essential for precise decision-making. To access the full intelligence suite and integrate these findings directly into your 2026 planning cycle, please visit the official market research portal and download the complete publication.
For detailed analysis of this topic, please visit the official page: High Speed Oven Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


