



PW Consulting: Intravesical BCG Market Hits $195M in 2025, Projected 8.97% CAGR Through 2032

Navigating Supply Chain Complexity and Treatment Demand: Strategic Insights into the Intravesical BCG Market
As the global healthcare landscape continues to evolve, the management of non-muscle invasive bladder cancer remains a critical focal point for urologists, pharmaceutical manufacturers, and healthcare administrators. The Intravesical Bacillus Calmette-Guérin market has experienced steady expansion over the past five years, reflecting both the clinical indispensability of BCG therapy and the structural challenges inherent in biological manufacturing. Our latest market intelligence study provides a comprehensive examination of this evolving landscape, offering executives and strategy teams a rigorous foundation for capital allocation, supply chain planning, and competitive positioning through the 2026 to 2032 forecast horizon.
The therapeutic context for intravesical BCG is unambiguous. Major clinical guidelines continue to position BCG as the preferred adjuvant treatment for intermediate- and high-risk disease presentations, underscoring a durable demand profile that transcends short-term pricing fluctuations or regional reimbursement variations. At the same time, the biological nature of BCG production introduces constraints that have repeatedly tested supply resilience. Understanding how these clinical mandates intersect with manufacturing bottlenecks, regulatory pathways, and regional procurement patterns is precisely the kind of strategic clarity that our research is designed to deliver.
Historical Trajectory and Forecast Outlook
The market has followed a measured but consistent growth curve since the early 2020s, driven by steady adoption in established markets and gradual expansion of access in developing regions. Our historical reconstruction places total market revenue at approximately 150 million dollars in 2020, progressing to 158 million dollars in 2021, 168 million dollars in 2022, 178 million dollars in 2023, and 184 million dollars in 2024. The base year analysis for 2025 reflects continued momentum, with the market reaching 195 million dollars as procurement cycles stabilized and clinical demand maintained its upward trajectory.
Looking forward, our forecast modeling projects the market to exceed 214 million dollars in 2026, followed by progressive expansion toward 237 million dollars in 2027, 241 million dollars in 2028, 279 million dollars in 2029, 292 million dollars in 2030, 315 million dollars in 2031, and 342 million dollars by 2032. The compound annual growth rate across the forecast period is calculated at 8.97 percent, a figure that captures the combined effect of sustained clinical utilization, capacity investments by key manufacturers, and incremental market participation from newly authorized or expanded-access formulations. This trajectory is not merely a statistical projection; it is a strategic signal that underscores the importance of long-term planning for procurement teams, investors, and clinical network operators who must anticipate both volume growth and supply volatility.
Structural Dynamics Shaping Market Behavior
The Intravesical BCG ecosystem is defined by a small number of entrenched manufacturers, each operating within distinct regulatory environments and supply chain architectures. Because BCG is a live biological product, production is inherently sensitive to process validation, strain stability, facility compliance, and distribution logistics. These factors have historically limited the number of viable commercial suppliers and concentrated market participation among a handful of established entities. Our research maps these structural realities in detail, offering decision-makers a clear view of where supply-side constraints originate and how they influence procurement strategies across different clinical settings.
Shortages have been a recurring theme in the market narrative, particularly in regions where a single manufacturer has served as the primary domestic source. This concentration has prompted repeated discussions within clinical guideline bodies regarding dose modification protocols and alternative sourcing strategies when supply disruptions occur. At the same time, recent authorization and supply-agreement developments have begun to diversify the availability landscape, introducing expanded-access programs and cross-border supply arrangements that create new options for treating centers. Our report examines these developments not as isolated announcements, but as interconnected signals that reshape procurement risk, pricing expectations, and competitive dynamics over the forecast period.
The Competitive Landscape: Positioning Among Core Participants
A defining feature of this market is the strategic positioning of its leading commercial participants, each of whom brings a different combination of manufacturing capability, regulatory footprint, and supply-chain response to the table. Our analysis evaluates these participants with a focus on operational readiness, product presentation, and the ability to respond to demand pressure.
One of the most closely watched developments involves the sole U.S.-based manufacturer of a widely recognized intravesical formulation. This company has publicly outlined plans to construct a new production facility intended to significantly expand output capacity, with an operational timeline that positions the expansion to intersect with the later years of our forecast window. The strategic significance of this investment extends beyond volume; it reflects an effort to address persistent supply limitations that have influenced clinical scheduling, procurement planning, and payer discussions for years. Our research explores how this capacity expansion is likely to alter supply risk perceptions and what it implies for market share stability among competing sources.
Alongside this effort, other participants have pursued complementary routes to strengthen availability. One manufacturer and distributor involved in U.S. intravesical administration continues to play a central role in the commercial pathway for a well-established product, maintaining its presence as a key node in the domestic supply chain. In parallel, an Indian-based producer has advanced a lyophilized formulation with broad international authorization for non-muscle invasive bladder cancer treatment, supported by a multi-year shelf-life profile and a presentation designed for practical clinical use. This participant has also been linked to recent regulatory authorization activity that expanded access to a recombinant BCG approach under specific program conditions, signaling a more direct response to shortage-driven demand.
A Japanese manufacturer adds another dimension to the competitive picture through its intravesical offering built on a distinct strain with specific potency characteristics. This supplier's product has been associated with recent supply arrangements intended to broaden availability in key markets, including an exclusive development and supply framework for U.S. activity. These moves illustrate how strain differentiation, dosing conventions, and regional authorization strategies all feed into a competitive environment where supply assurance can be as strategically important as the product itself. Our report unpacks these positioning choices and evaluates how they interact with procurement realities across hospital and clinic settings.
Segmentation Logic and Revenue Concentration Patterns
Our segmentation framework is designed to help executives understand where revenue is generated, which product formats dominate commercial activity, and how procurement is distributed across clinical care environments. The study examines product-type dynamics across the principal vial presentations that define commercial supply, with particular attention to how volume concentration differs across dosage forms. The analysis also maps application-level demand patterns, distinguishing between the largest care setting that anchors bulk utilization and the secondary setting that contributes a smaller but strategically meaningful share of total demand.
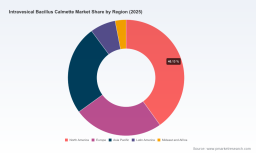
In addition, the research evaluates regional revenue distribution to identify where commercial activity is most concentrated and where growth potential is emerging. Rather than presenting percentages in isolation, our analysis situates regional data within the broader context of procurement habits, guideline adoption, and supply accessibility, enabling readers to interpret geographic patterns in a way that directly informs market-entry discussions, partnership evaluation, and inventory planning. The report further addresses market concentration metrics to clarify how revenue is distributed among leading participants, providing a realistic picture of the degree to which the market remains consolidated and where competitive pressure may intensify.
Report Contents and Operational Utility for Decision-Makers
This study is structured to support practical decision-making rather than abstract market observation. Readers will find a detailed examination of the demand drivers that shape utilization, the supply-side factors that influence availability, and the regulatory and guideline environment that governs treatment selection. The report includes a comprehensive competitive profiling section that describes each major participant's operational base, product positioning, and strategic response to market constraints. It also provides a forward-looking synthesis of how capacity investments, authorization activity, and supply agreements may alter the balance of availability across the forecast period.
Beyond competitive mapping, the report delivers actionable analytical building blocks for pricing strategy, sourcing diversification, and network planning. Procurement teams can use the segmentation analysis to better understand where demand concentrates and how product formats are distributed across end-use settings. Executive teams can draw on the forecast structure to test scenario assumptions around capacity release, shortage mitigation, and regional expansion. Investors and business development professionals can use the concentration and competitive assessments to evaluate entry feasibility and partnership opportunities without relying on incomplete or anecdotal information.
The study also incorporates discussions of cost considerations and treatment-course economics where relevant to strategic planning, alongside the practical implications of strain potency differences, dosing conventions, and product presentation choices. These details matter because they influence both clinical workflow and procurement behavior, and our report places them in context so that strategic conclusions are grounded in operational reality rather than surface-level market descriptors.
Why This Research Matters for 2026 Strategy
The 2026 to 2032 window represents a period in which the Intravesical BCG market is likely to be shaped as much by supply-side restructuring as by underlying clinical demand. Capacity expansion commitments, authorization pathways, and cross-company supply arrangements are beginning to alter the availability landscape, yet the biological and regulatory complexity of BCG production means that uncertainty will not disappear overnight. In this environment, decision-makers need more than top-line growth figures; they need an integrated view of how product formats, care settings, regional dynamics, and competitive actions combine to create risk and opportunity.
Our report is designed to provide that integrated view. It connects market size progression and forecast expansion to the operational realities behind the numbers, helping organizations anticipate where supply resilience will improve, where dependence on limited sources may persist, and how different procurement strategies may perform under varying shortage and authorization scenarios. For executives planning budgets, sourcing frameworks, or competitive responses in 2026, this research offers the level of detail required to move from reactive positioning to informed strategy.
BCG Vaccine Market
Conclusion and Next Steps
The Intravesical BCG market is at a point where clinical importance, manufacturing complexity, and evolving supply arrangements converge to create both challenge and opportunity. Our study translates that convergence into a structured, forward-looking analysis that supports strategic planning across commercial, operational, and investment decisions. The full report provides the complete segmentation detail, competitive assessment, and forecast architecture needed to evaluate market potential with confidence. Readers interested in the full set of regional breakdowns, application-level revenue patterns, product-type splits, and concentration metrics are encouraged to access the complete study for the comprehensive intelligence required to guide 2026 decision-making.
Intravesical Bacillus Calmette Market
For detailed analysis of this topic, please visit the official page: Intravesical Bacillus Calmette Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


