



PW Consulting: Isothermal Packaging Market Hits $91.4M in 2025, Set for 5.7% CAGR Through 2032

Strategic Intelligence for the Isothermal Packaging Market: Navigating the 2026 Decision Landscape
The isothermal packaging sector stands at a critical inflection point. As global supply chains tighten and temperature-sensitive logistics become increasingly complex, the ability to maintain controlled temperatures without relying entirely on active refrigeration is no longer a tactical convenience; it is a strategic imperative. PW Consulting understands that executive teams require more than high-level market summaries. They need structural clarity, competitive positioning, and forward-looking intelligence that can be immediately applied to capital allocation, product development, and partnership strategy. Our latest comprehensive market research on the Isothermal Packaging Market is built precisely for that purpose, offering decision-makers a rigorous foundation to act with confidence throughout 2026 and beyond.
The narrative emerging from the full report is one of disciplined expansion, material innovation, and regulatory maturation. Gross revenue has progressed from 68.5 million USD in 2020 to 91.4 million USD in 2025, reflecting both sustained demand and the sector’s gradual ability to absorb higher compliance costs and sustainability expectations. Looking ahead, the forecast window tracked in the study extends through 2032, with the trajectory anchored by a projected compound annual growth rate of 5.7 percent. By 2032, total market revenue is positioned to reach 134.8 million USD. These headline figures are not abstract indicators; they frame a market that is large enough to reward focused investment yet fragmented enough to penalize undifferentiated strategy. The real question for leadership teams is not whether isothermal packaging will grow, but which segments, capabilities, and partnerships will convert that growth into durable competitive advantage.
Why This Research Matters for 2026 Decision-Making
Over the past five years, historical data shows a market that has consistently advanced in step with broader cold chain complexity. Revenue moved from 74.78 million USD in 2021 through 76.69 million USD in 2022, 79.64 million USD in 2023, and 87.09 million USD in 2024 before crossing the 90 million USD threshold in 2025. That path matters strategically because it signals a market that has moved past isolated growth spurts into a more predictable, structurally supported expansion phase. For 2026, this means planning cycles can no longer rely on assumption-driven growth estimates or generic trend commentary. Corporate strategy requires evidence-based segmentation, competitor benchmarking, and a clear read on the operational forces shaping adoption.
The forecast period from 2026 to 2032 further underscores the value of disciplined foresight. Starting from an estimated 94.8 million USD in 2026, the projected climb to 102.62 million USD in 2027, 108.95 million USD in 2028, 113.39 million USD in 2029, and 121.09 million USD in 2030 reflects an environment where demand is broadening across end-use categories while supply-side innovation is steadily reshaping cost structures and performance specifications. Executives evaluating M&A, capacity expansion, service-line extensions, or geographic entry will find that the study provides a reasoned framework rather than a static snapshot. In fast-moving life sciences and temperature-controlled logistics markets, the difference between a reactive decision and a strategically timed one often comes down to how well an organization understands the forces shaping the next several quarters, not just the current quarter.
Equally important, the research is designed to support practical decisions around product architecture and operational footprint. Isothermal solutions are increasingly judged not only on thermal performance, but also on reusability, reverse logistics, material sourcing, and compliance readiness. As a result, strategy teams need insight that connects market size and growth to operational realities, including how manufacturers are adapting to evolving standards, what raw materials are gaining prominence in packaging construction, and where sustainability expectations are beginning to influence procurement and design choices. The full report is structured to help leaders translate these dynamics into concrete actions, whether that means refining a product roadmap, reassessing supplier relationships, or identifying where differentiation can be built into both engineering and service models.
How the Study Is Structured for Actionable Intelligence
This research is organized to serve multiple internal audiences at once. It is detailed enough for strategy, product, and supply chain teams that need granular context, while remaining clear enough to inform board-level discussions about market positioning, investment priorities, and risk exposure. Rather than presenting a single aggregated story, the study breaks the market down across meaningful structural dimensions so that executives can identify where growth is concentrated, where competitive pressure is most intense, and where long-term differentiation is most achievable.
Refrigeration Packaging Market
By type, the market includes distinct material and design pathways, each with its own cost, performance, and sustainability profile. The study examines how these categories compete on functionality and customer preference, and where engineering trade-offs influence adoption. In practice, the type landscape matters because it determines not only what is being purchased, but why it is being purchased. Performance requirements tied to heat retention, weight constraints, reusability, and end-of-life handling can shift demand between materials and designs, which means product strategy must account for both technical compatibility and procurement behavior.
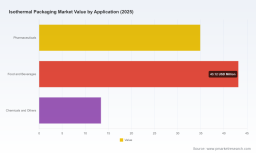
By application, isothermal packaging serves multiple high-stakes sectors, each with different compliance burdens, shipment patterns, and tolerance thresholds. The report explores how demand diverges across these usage contexts and why some applications are more sensitive to innovation in reusable systems, monitoring integration, and sustainable material substitution. Application-level insight is especially valuable in 2026, because buyer expectations are no longer limited to basic temperature control; they increasingly include assurance, transparency, and evidence of environmental or operational responsibility throughout the product lifecycle.
By region, the analysis reflects the uneven pace of adoption and the differing regulatory environments that shape local demand. Geography is not treated as a decorative layer of data, but as a strategic lens for understanding where volume, competitiveness, and market entry barriers differ. This regional framing helps companies evaluate distribution models, localization requirements, and partnership opportunities with the nuance they require, particularly when deciding whether to serve a market through existing infrastructure or build a dedicated presence. Regional dynamics can also reveal where certain materials or packaging formats gain traction more quickly, which can influence sourcing, service design, and expansion timing.
Beyond segmentation, the study connects the market to an evolving operating environment that is shaping how players compete. Regulatory expectations are becoming a more active force in packaging design and procurement, especially where temperature-sensitive shipments must satisfy stringent handling standards. At the same time, producer responsibility frameworks are increasingly influencing how packaging components are evaluated at end-of-life, pushing attention toward recyclable and reusable configurations. Raw material choices are also part of the conversation, with certain insulation structures continuing to play a central role in isothermal packaging construction while recycled inputs are making measurable inroads into more sustainable shipper designs. These forces are not peripheral; they are reshaping cost structures, product roadmaps, and customer selection criteria. Understanding them in context is essential for any organization that wants to anticipate change rather than simply respond to it.
Competitive Dynamics That Define Strategic Positioning
The competitive landscape is shaped by a specialized set of manufacturers and solution providers whose capabilities span thermal engineering, compliance, sustainability, and logistics support. The report provides company-level context that helps leaders understand how incumbents are positioning themselves and where the market may be vulnerable to new entrants or partnership-driven disruption.
-
EMBALL'ISO specializes in high-performance passive isothermal packaging solutions for life sciences, including vaccines and biologics, with reuse and reverse logistics services.
-
Sofrigam designs, manufactures, and deploys lightweight, sustainable isothermal packaging for pharmaceutical, biotech, and healthcare temperature-sensitive products.
-
Cryopak provides complete cold chain packaging solutions including insulated containers, gel packs, phase change materials, and sustainable reusable programs.
-
Peli BioThermal offers reusable and single-use thermal packaging solutions for pharmaceuticals, clinical trials, and life sciences cold chain distribution.
-
Cold Chain Technologies delivers sustainable thermal packaging including reusable pallet and parcel solutions with digital monitoring for life sciences.
-
Intelsius manufactures environmentally sustainable temperature-controlled packaging and sample transport solutions compliant with UN regulations.
-
Isovation manufactures innovative isothermal packaging for healthcare, food, and logistics to maintain controlled temperatures.
-
Zfoam supplies foam materials and solutions for isothermal packaging in food, pharma, and industrial applications.
What distinguishes this group is not only the breadth of their technical offerings, but the strategic directions embedded in them. Several players are leaning into reusable and reverse logistics models, suggesting that the market is beginning to reward lifecycle thinking over single-transaction product sales. Others are emphasizing lightweight construction and sustainable materials, aligning product design with procurement expectations around environmental impact. Some are integrating monitoring and digital capabilities into thermal packaging programs, which points to a broader shift toward visibility and assurance as part of the value proposition. For decision-makers, this matters because competitive advantage may increasingly depend on how well a company can combine thermal reliability, compliance readiness, and sustainable service design in a single coherent offering.
Market structure also suggests that concentration is meaningful, but not absolute. The study examines concentration indicators that help explain where scale, reputation, and integrated service capabilities matter most. In markets with meaningful share held by a limited set of established providers, new entrants often have to compete through differentiated design, niche application expertise, or a stronger sustainability and logistics narrative. In that context, understanding competitor profiles is not about memorizing company names; it is about recognizing capability clusters, identifying where incumbents are stretched, and assessing which buyer segments are most open to alternative solutions.
What Strategic Leaders Should Watch in 2026
As isothermal packaging moves further into a period of material and regulatory evolution, several themes warrant close attention. The first is the increasing importance of compliance as a design constraint. Temperature-sensitive shipments involving biological and medical materials must align with recognized handling standards, which means packaging is no longer a passive shell but a regulated component of the logistics chain. Companies that treat compliance as a late-stage requirement risk rework, delayed adoption, and weaker customer confidence.
The second theme is the pressure to reduce environmental footprint without sacrificing thermal performance. Extended producer responsibility considerations and broader sustainability expectations are influencing how packaging components are sourced, used, and recovered. At the same time, post-industrial recycled inputs are being integrated into more sustainable shipper designs, signaling that circularity is moving from aspiration to engineering practice. For manufacturers and buyers alike, this trend raises practical questions about trade-offs between reuse, recyclability, weight, insulation effectiveness, and total cost.
The third theme is the role of insulation material choices in shaping both performance and market positioning. In many isothermal packaging structures, polyurethane foam insulation remains a core raw material, reinforcing the importance of material availability, consistency, and innovation in product development. Yet the broader landscape is not static; demand is also shaped by alternatives and hybrid approaches that aim to balance thermal reliability with weight, cost, and sustainability goals. Companies that understand these material dynamics can make more informed decisions about sourcing, product architecture, and differentiation.
Isothermal Packaging Market
The fourth theme is the rise of service-oriented value. Reuse and reverse logistics, digital monitoring, and program-based deployment models are becoming more visible in the market, indicating that buyers increasingly value outcomes over components alone. This shift has strategic implications for pricing, customer retention, and competitive differentiation. It also means that companies evaluating their market position should consider not only what they sell, but how they support it across the shipment lifecycle.
Why the Full Study Is Built for Decision-Makers
This research is designed to help leadership teams convert market intelligence into decisions that are defensible, timely, and specific. The complete report provides deeper segmentation analysis, competitor context, regulatory and materials dynamics, and forecast pathways that support planning across 2026 and the 2026–2032 horizon. It is intended for strategy, operations, product, and investment teams that need to assess where the market is heading and how their organization can respond with precision.
Because isothermal packaging sits at the intersection of performance, compliance, sustainability, and logistics, isolated data points are rarely enough. Decision-makers benefit most from a structured view that links market size, growth trajectory, segmentation behavior, and competitive posture into a single coherent narrative. That is the purpose of the full study: to give executives a reliable foundation for prioritizing investments, refining product and service strategy, and anticipating the forces that will shape demand in the coming years.
If your team is preparing for 2026 planning cycles, evaluating market entry or expansion, or assessing how thermal packaging strategy should evolve alongside regulatory and sustainability expectations, the complete report offers the depth required to move from broad awareness to actionable insight. The full analysis goes beyond summary figures to examine the structural forces that will determine where growth concentrates and how competition intensifies. For organizations that rely on temperature-controlled distribution, this is the kind of intelligence that can help shape decisions before the market shift becomes obvious to everyone else.
The complete PW Consulting study on the Isothermal Packaging Market is available through our research portal, where you can access the full segmentation framework, competitive profiles, regulatory and materials context, and the extended forecast view that supports strategic planning well beyond the 2026 horizon. For teams seeking a clear, evidence-based path through a market that is both expanding and becoming more demanding, this report is built to deliver exactly that.
For detailed analysis of this topic, please visit the official page: Isothermal Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


