



Industrial Tape Market Projects 5.65% CAGR to Reach $300.3M by 2032

Strategic Horizons for the Industrial Tape Market 2026: Navigating Growth, Consolidation, and Material Disruption
The industrial tape market stands at a critical inflection point as enterprises move deeper into the 2026 forecasting cycle. What was once viewed as a commoditized ancillary supply has evolved into a strategically sensitive category, where adhesive formularies, liner chemistry, regulatory compliance, and supplier consolidation directly shape manufacturing resilience and downstream product performance. Our latest Industrial Tape Market research is designed to give leadership teams and category managers a clear, decision-grade view of the terrain ahead, translating multi-year momentum into actionable procurement, sourcing, and market-entry strategies.
This overview outlines the strategic value embedded in the full study, highlights the structural forces reshaping supply and demand, and previews the competitive landscape that procurement and R&D leaders must navigate. Detailed segment sizing, regional contribution breakdowns, application share tables, and company-level revenue splits are intentionally reserved for the complete report, because industrial procurement decisions require the precision that only the full methodology and dataset can deliver.
Why the 2026 Outlook Matters for Enterprise Decisions
Industrial tape is no longer an incidental line item. It is an enabling material across automotive assembly, structural bonding, electrical and electronics insulation, protective packaging, and construction sealing. As OEMs and tier suppliers tighten cost structures while simultaneously demanding higher reliability and sustainability, the tape category has become a proxy for broader supply chain discipline. Companies that treat tape sourcing as a tactical buy risk exposure to raw material volatility, reformulation cycles, and supplier concentration. Companies that approach it strategically can unlock better total cost of ownership, improved qualification timelines, and stronger negotiation leverage.
The 2026–2032 period is particularly consequential because multiple forces are converging at once. Demand is moving on a steady upward trajectory, but the path is not uniform across regions, end-use sectors, or chemistries. At the same time, raw material economics, regulatory scrutiny on fluoropolymer coatings, and shifting labor and manufacturing costs are compressing margins and forcing reformulation. The firms that succeed will be those that can see past headline growth and understand where value is created, where risk is concentrated, and which supplier capabilities will matter most over the next cycle.
Macro Trajectory Anchored in 2020–2032 Data
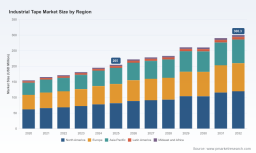
The long-horizon view shows a market that has built consistent momentum from 2020 through the base year of 2025 and is positioned for continued expansion through 2032. The historical arc from 2020 to 2025 reflects a market that has absorbed pandemic-era disruptions, rebalanced procurement, and benefited from renewed industrial activity. Looking forward, the forecast period projects steady growth through 2032, with the overall market expanding at a CAGR of 5.65 percent in USD terms.
This trajectory is not just a top-line figure; it is a structural signal. Steady compound growth in a mature category indicates that demand is being driven by recurring industrial usage, incremental substitution toward higher-performance adhesive solutions, and continued penetration in end markets that depend on reliable bonding and sealing. Yet the forecast also contains nuance. Mid-decade figures show year-to-year variation that underscores the importance of segment-level analysis rather than reliance on a single aggregate number. In practice, this means procurement leaders should plan for growth while recognizing that regional demand patterns, application-specific purchasing cycles, and product-type mix will determine where the growth is actually captured.
Because the detailed regional and application splits, as well as type-level revenue figures, are part of the full dataset, we encourage readers to consult the complete report before locking in volume commitments, capacity plans, or supplier diversification strategies. Aggregate direction is useful; segment precision is essential.
Structural Forces Shaping Procurement and Product Strategy
Three intersecting dynamics are redefining how industrial tape buyers and suppliers operate in 2026. These forces are not isolated; they compound, and they demand a more integrated sourcing posture.
- Raw material economics and feedstock volatility: Acrylic monomers and synthetic rubber inputs have faced meaningful price pressure, with industry reporting indicating increases in the 20–30 percent range in 2026 tied to petrochemical feedstock variability. For pressure-sensitive industrial tapes, this translates into higher manufacturing expenses and greater sensitivity to index-linked pricing, inventory timing, and formulation optimization. Buyers should anticipate more active negotiation around pass-through mechanisms, multi-quarter commitments, and qualification of alternative grades where performance allows.
- Regulatory pressure on release liner chemistry: Restrictions on PFAS in release liner fluoropolymer coatings are accelerating reformulation requirements for industrial adhesive tapes. This is not merely a compliance checkbox; it affects line speed, unwind behavior, adhesion consistency, and downstream conversion performance. Suppliers that can deliver equivalent functionality with compliant chemistries will gain preference, particularly in applications where qualification cycles are long and switching costs are high.
- Manufacturing cost and labor dynamics: Fluctuations in raw material costs and labor expenses have collectively lifted manufacturing costs for pressure-sensitive industrial tapes. The practical effect is a tighter margin environment that rewards operational efficiency, localized production where feasible, and suppliers with proven scale and process control. For buyers, this means total cost analysis should extend beyond unit price to include logistics, changeover efficiency, technical support, and supply continuity.
These dynamics reinforce the value of a report that connects market sizing with the operational levers that determine real-world outcomes. Understanding the direction of travel is important, but understanding which levers are available, which suppliers are best positioned to pull them, and where reformulation or substitution risk is highest is what turns insight into execution.
Competitive Landscape: Consolidation, Capability, and Recent Moves
The market is moderately concentrated, with the top three players accounting for 35.8 percent of revenue and the top five reaching 42.2 percent. This level of concentration suggests a landscape where scale, brand trust, and application-specific expertise provide meaningful defensibility, while still leaving room for differentiated specialists and regional performers to compete on service, customization, and niche performance.
Several established players define the center of gravity in this market, each with distinct strengths that procurement and engineering teams evaluate differently depending on the application.
- 3M Company, based in St. Paul, MN, continues to develop and produce high-performance pressure-sensitive adhesive tapes for industrial sealing, masking, and assembly applications. Its breadth across industrial use cases makes it a frequent reference point for multi-application programs and standardized specifications.
- Nitto Denko Corporation, headquartered in Osaka, specializes in functional industrial tapes for electronics, automotive, and battery bonding solutions. Its orientation toward higher-value functional applications aligns with the broader industry shift toward precision bonding and electrification-related demand.
- tesa SE, located in Norderstedt, Germany, manufactures pressure-sensitive industrial tapes for automotive, construction, and general industrial uses. Its European base and multi-sector coverage make it a relevant benchmark for companies sourcing across both industrial and infrastructure-adjacent applications.
- Intertape Polymer Group Inc. (IPG), based in Sarasota, FL, produces carton sealing, filament, and performance industrial tapes for packaging and protective applications. Its focus on protective and packaging-adjacent solutions positions it as a key reference in segments where sealing speed, filament reinforcement, and printability matter.
- Scapa Industrial, operating under the Mativ brand from Alpharetta, GA, manufactures adhesive tapes and films for automotive, cable, construction, and specialty industrial markets. Its film and tape portfolio supports customers who need integrated material solutions across mixed industrial environments.
- Avery Dennison Corporation, headquartered in Simi Valley, CA, supplies pressure-sensitive tapes for industrial bonding, labeling, and protective uses. Its breadth across bonding and labeling-adjacent applications makes it a versatile supplier for programs that blend identification, protection, and assembly needs.
- Nichiban Co., Ltd., based in Tokyo, produces high-quality pressure-sensitive tapes for industrial and general applications. Its reputation for consistent quality supports customers seeking reliable performance in demanding industrial contexts.
Recent developments illustrate how these companies are responding to shifting end-market priorities and regulatory realities. In April 2025, Avery Dennison introduced a new Solar Panel Bonding Portfolio featuring pressure-sensitive adhesive tapes designed for solar panel manufacturing, signaling targeted investment in renewable-energy-adjacent assembly workflows. In July 2025, Shurtape Technologies launched the AP 251 custom-printed acrylic packaging tape for manual or automated carton sealing of light to medium weight cartons, underscoring continued product-level refinement in packaging efficiency and branding integration.
These moves matter because they show where leading suppliers are placing their bets: in renewable energy supply chains, in packaging automation, and in formulations that can withstand both performance demands and regulatory change. For buyers, the implication is clear. Supplier selection should weigh not only current pricing and availability, but also the trajectory of a company’s application focus, its ability to support reformulation, and the depth of its technical service in the specific verticals a buyer serves.
What the Full Report Delivers for Decision-Makers
This study is built to support decisions that require both breadth and specificity. It frames the market from multiple operational angles so that procurement, R&D, and strategy teams can align on the same evidence base before committing to volume plans, supplier reallocations, or qualification programs.
The report provides a structured view of segmentation across region, type, and application, along with historical context and a forward forecast through 2032. It includes an examination of market concentration, enabling readers to assess where bargaining power is concentrated and where alternative sourcing may be necessary. It also integrates recent product launches and industry context to connect macro trends with real commercial activity, helping readers distinguish between temporary noise and durable shifts.
Equally important, the full study is designed to support practical workflows:
- Sourcing strategy: identifying which supplier capabilities, formulations, and geographies align with risk tolerance and performance requirements.
- Cost planning: interpreting raw material volatility, labor dynamics, and regulatory-driven reformulation as part of a multi-quarter procurement plan rather than a single purchase event.
- Application planning: understanding where demand is most durable across automotive, construction, packaging, electrical and electronics, and other industrial uses, so that inventory, specification, and qualification decisions reflect likely usage patterns.
- Competitive positioning: using concentration data and company profiles to gauge where incumbents have structural advantages and where differentiated suppliers can win on service, customization, or compliance readiness.
Because the report contains segment-level magnitude, regional contribution levels, application share figures, and company-specific context, it is best used as a decision system rather than a high-level summary. The aggregate growth story establishes the environment; the detailed breakdown determines the playbook.
How to Use This Intelligence in 2026 Planning
For executives planning the 2026 sourcing and strategy cycle, the most valuable use of the full report is to create a shared baseline before negotiations begin. Start by aligning on the forecast horizon, then map demand assumptions to the relevant type and application segments that affect your portfolio. From there, assess supplier exposure against concentration dynamics and recent product developments, especially where reformulation or feedstock volatility may affect continuity or cost.
Procurement teams should also use the study to pressure-test total cost models. A lower headline price can be misleading if it comes with higher changeover complexity, weaker technical support, or greater exposure to raw material indexing. Conversely, a premium supplier may deliver lower total cost if it reduces qualification risk, supports compliant liner chemistry, or offers more stable fulfillment in a volatile feedstock environment. The report’s structure is intended to make those tradeoffs explicit.
Finally, use the competitive and regulatory context to shape qualification roadmaps. Where PFAS-related reformulation is relevant, prioritize suppliers that can demonstrate transition readiness. Where solar, automotive, or packaging automation is a growth vector, consider suppliers that have already invested in application-specific portfolios. The firms that plan around capability trajectories, rather than only current price sheets, will be better positioned as the cycle advances.
Secure the Complete Dataset for Segment-Level Precision
The industrial tape market is moving with steady momentum, but the real strategic opportunity lies in the details: where growth is concentrated, which chemistries face cost and compliance pressure, how concentrated the supplier base is, and which companies are actively shaping the next generation of industrial bonding and sealing solutions. This overview has outlined the strategic frame, the structural forces, and the competitive context that make the category worth watching closely in 2026 and beyond.
Electrical Tape Market
To move from directional understanding to executable plan, access the complete Industrial Tape Market research. The full report provides the segment-level sizing, regional and application contributions, type-level context, concentration metrics, company profiles, and integrated industry developments needed to make informed procurement, sourcing, and strategy decisions with confidence. The macro picture is clear; the segment-level precision that drives real decisions is available in the complete study.
Industrial Tape Market
For detailed analysis of this topic, please visit the official page: Industrial Tape Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


