



PW Consulting: Coding Equipment Market Hits $6.75B in 2025, Projects CAGR of 6.12% to $10.27B by 2032

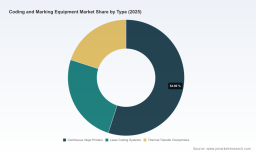
Strategic Imperatives in the Global Coding and Marking Equipment Market: Navigating Growth Through 2032
In an era where supply chain transparency, regulatory compliance, and packaging sustainability dictate competitive advantage, the coding and marking equipment market stands at a critical inflection point. Manufacturing leaders, procurement directors, and automation strategists are no longer asking whether to upgrade their marking infrastructure, but how to align capital allocation with a market that is expanding at a steady pace while simultaneously fragmenting under technological, regulatory, and material-cost pressures. Our latest comprehensive study on the Coding and Marking Equipment Market transforms raw trajectory data into a decision-ready framework, offering executives a clear line of sight into the operational and financial implications of the 2026–2032 forecast window.
The market’s historical foundation provides essential context for forward-looking strategy. Between 2020 and 2025, sector revenue climbed from approximately 5.0 billion USD to 6.75 billion USD, reflecting a period of accelerated line automation, heightened traceability mandates, and widespread adoption of advanced coding technologies across high-volume production environments. This momentum is projected to sustain itself through the end of the decade, with market valuation expected to reach 7.21 billion USD in 2026 and continue its upward trajectory toward 10.27 billion USD by 2032. The forecast period compound annual growth rate of 6.12 percent underscores a mature but structurally resilient industry, one whose expansion is increasingly driven not by volume alone, but by precision, compliance readiness, and lifecycle optimization.
For enterprise decision-makers, these figures represent more than a top-line growth narrative. They signal a shifting capital allocation landscape where legacy equipment refresh cycles, cross-platform compatibility, and total cost of ownership calculations must be recalibrated against a backdrop of evolving packaging substrates, tightening food-safety disclosures, and intensifying competitive consolidation. Our report translates these macro trends into actionable intelligence, enabling strategy teams to stress-test investment theses, benchmark regional performance vectors, and anticipate demand inflection points before they materialize in procurement cycles.
Decoding the Operational Architecture of the Analysis
The study is engineered for practitioners rather than passive observers. It maps the full lifecycle of coding and marking deployment, from technology selection and line integration to maintenance economics and compliance verification. Readers will encounter a methodical dissection of how different printing modalities interact with production throughput, substrate variability, and regulatory labeling requirements. The analysis places particular emphasis on the operational tradeoffs that procurement and engineering teams face daily: balancing ink-based continuity against laser permanence, evaluating thermal transfer durability under abrasive or temperature-fluctuating conditions, and aligning printer head lifecycle with line-speed targets and changeover frequency.
Beyond equipment taxonomy, the report integrates upstream cost dynamics that directly influence capital expenditure planning. Recent shifts in raw material pricing have compressed margins across packaging supply chains, creating ripple effects for coding system operators who must now weigh upfront hardware investments against ongoing consumables volatility. The analysis incorporates these material-cost pressures into scenario modeling, helping executives evaluate whether modular upgrades, ink-substitution strategies, or full-line conversions offer the most defensible path to sustained ROI. This practical orientation ensures that financial teams can align operational roadmaps with realistic cost curves rather than static vendor quotes.
Compliance architecture forms another critical pillar of the study. As labeling requirements become more granular and audit expectations more stringent, the functional scope of coding equipment has expanded beyond simple identifier placement. The report examines how verification workflows, third-party audit readiness, and automated inspection integration are reshaping procurement priorities. Organizations seeking to future-proof their packaging lines will find structured guidance on aligning coding capabilities with traceability mandates, nutrient-disclosure frameworks, and sustainability-driven substrate transitions.
Competitive Dynamics and Strategic Differentiation
The market’s competitive architecture reflects both entrenched 리더십을 and continuous technological repositioning. The sector remains moderately concentrated, with the top three players collectively commanding roughly 45.8 percent of revenue and the top five firms controlling approximately 61.2 percent. This distribution indicates a landscape where scale advantages, service networks, and cross-vertical application expertise create meaningful barriers, yet leave sufficient headroom for specialized innovators and regional specialists to capture value through niche performance differentiation.
At the center of the competitive field are organizations that have built deep application fluency across high-demand verticals. Domino Printing Sciences, headquartered in Cambridge, United Kingdom, has maintained a strong focus on continuous inkjet, laser, and hybrid inkjet coding systems, with dedicated solutions engineered for high-speed traceability on cans, bottles, cartons, and cases. Its recent product cadence illustrates the pace of innovation shaping the market: in March 2026, the company introduced the Cx150i direct-to-box printer utilizing oil-based ink for more sustainable and accessible coding on food packaging, alongside the Ux360i UV Laser Coder designed for high-speed sustainable packaging applications in food and beverage lines. The same period saw the release of the Gx-Series PRO Printhead, built to support the industry’s transition toward 2D coding on food packaging. These developments were preceded by the October 2025 introduction of the Dx1060i CO2 Laser Coder and F-Series fibre lasers, which target permanent code generation on beverage cans, glass, and plastics.
Videojet Technologies, based in Auckland, New Zealand, continues to position its CIJ, TIJ, and laser coder portfolio around permanent, food-safe prints tailored for food and beverage packaging lines. Markem-Imaje, operating from Aubervilliers, France, offers thermal inkjet, continuous inkjet, and laser marking systems calibrated for product- and case-level coding within food and beverage environments. Matthews International Corporation, headquartered in Pittsburgh, Pennsylvania, supplies TIJ, laser, and labeling systems aimed at high-resolution and permanent coding applications, while ID Technology, based in Minneapolis, Minnesota, delivers thermal inkjet coders and integrated systems for direct marking on cans, jugs, and cartons.
The competitive field also includes significant contributions from industrial equipment manufacturers and compliance-adjacent service providers. Hitachi Industrial Equipment Systems, headquartered in Tokyo, Japan, manufactures laser and inkjet coding systems optimized for traceability in industrial food and beverage settings. SATO Holdings Corporation, also based in Tokyo, provides TIJ and thermal transfer coders focused on packaging identification and regulatory compliance. SGS, headquartered in Geneva, Switzerland, extends the ecosystem through third-party verification and audit services for coding and marking systems deployed in food and beverage packaging lines. Rounding out the roster, Gem Gravure, based in the United States, supplies regulation-quality coding equipment specifically engineered for food and beverage packaging applications.
For strategy teams, this competitive mosaic matters because vendor selection is no longer a straightforward equipment-procurement exercise. It is a multi-year partnership decision that encompasses service responsiveness, technology roadmaps, consumables availability, and compliance-support capabilities. The report provides a structured comparison framework that helps organizations evaluate not just hardware specifications, but the broader value chain resilience each supplier brings to high-volume, high-compliance production environments.
Regulatory and Material-Cost Pressures Redefining Market Dynamics
External forces are accelerating the strategic relevance of coding and marking infrastructure. Regulatory evolution is one of the most immediate drivers. In January 2025, the FDA proposed a rule requiring a front-of-package Nutrition Info box on most packaged foods, mandating clear display of saturated fat, sodium, and added sugars categorized as Low, Medium, or High. By April 2025, the agency finalized updates to the healthy nutrient content claim definition, tightening limits on added sugars, saturated fat, and sodium. These developments do not merely change label content; they reshape the precision, legibility, and verification demands placed on coding systems, particularly on high-speed lines where print quality, placement consistency, and audit-ready documentation must remain uncompromised.
Simultaneously, raw material dynamics are injecting cost volatility into packaging production and, by extension, into coding system planning. In 2026, PET, PP, and PS plastic sheet prices rose 15–30 percent due to energy costs and paraxylene supply constraints. Corrugated paperboard and paper packaging costs also increased amid higher pulp and energy prices for food packaging production. For coding and marking operators, these shifts affect substrate compatibility, ink adhesion performance, laser interaction with treated surfaces, and overall line-tuning requirements. Equipment that performs reliably on stable substrate profiles may require recalibration, consumables substitution, or complementary inspection modules when material characteristics fluctuate.
These intersecting pressures are reshaping market dynamics in ways that reward proactive planning. Organizations that treat coding infrastructure as a static cost center risk encountering deployment bottlenecks when regulatory label formats change or when substrate transitions alter print stability. Conversely, enterprises that align their equipment strategy with anticipated regulatory timelines and material-cost trajectories can convert compliance and packaging shifts into efficiency gains, reducing downtime, minimizing rework, and improving audit outcomes.
Why This Study Matters for 2026 Decision-Making
The value of this research lies in its translation of trajectory data into operational clarity. Enterprise leaders operating in 2026 must navigate a market that is simultaneously expanding, consolidating, and being reshaped by compliance mandates and input-cost volatility. Top-line growth figures alone cannot guide capital deployment; they must be paired with segmentation intelligence, competitive capability mapping, regulatory horizon scanning, and total-cost modeling that reflects real-world line conditions.
Coding and Marking Equipment Market
Our report delivers that integrated view. It helps strategy and operations teams identify where demand concentration is forming, which technology pathways align with upcoming packaging and labeling requirements, and how vendor portfolios differ in their capacity to support rapid changeover, substrate variability, and verification workflows. It also contextualizes market concentration dynamics, enabling organizations to evaluate whether partnership with a large-scale incumbent, a specialized technology provider, or a service-oriented verification partner best matches their risk tolerance and growth targets.
Crucially, the study is designed to support decisions that extend beyond the current fiscal year. With a forecast horizon stretching to 2032, executives gain a structured basis for multi-phase investment planning, technology refresh scheduling, and capacity alignment. Rather than reacting to equipment obsolescence or compliance gaps after they emerge, organizations can sequence upgrades, model consumables exposure, and stress-test vendor commitments against plausible regulatory and material-cost scenarios.
Accessing the Full Strategic Blueprint
The coding and marking equipment market is entering a phase where precision, compliance, and cost resilience will separate scalable operators from those burdened by reactive procurement. This study provides the analytical foundation needed to navigate that phase with confidence. It combines market trajectory mapping, technology and application segmentation, competitive profiling, and dynamic cost-and-regulation context into a single decision-support instrument.
Coding and Marking Systems and Solutions Market
To explore the complete segmentation breakdown, detailed vendor capability comparisons, scenario-based cost modeling, and region-specific growth vectors, we invite you to access the full report through our source page. The complete intelligence package is structured for immediate integration into capital planning, procurement strategy, and operational roadmapping, enabling your team to move from market awareness to execution-ready strategy.
For detailed analysis of this topic, please visit the official page: Coding and Marking Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


