



PW Consulting: Smoked Salmon Market Hits $541 Million in 2025, Projects 5.6% CAGR Through 2032

Strategic Horizons: Navigating the Smoked Salmon Market Through 2032
The global smoked salmon industry stands at a critical inflection point. As supply chains mature and consumer preferences shift toward premium protein sources, understanding the trajectory of this market is no longer optional for stakeholders operating at scale. Our latest research publication delivers a comprehensive assessment of the sector, distilling twelve years of historical performance and forward-looking projections into an actionable intelligence framework. For executives planning capital allocation, product development, and geographic expansion in 2026, this report serves as the foundational reference for disciplined decision-making.
The value proposition of this study lies not merely in aggregation, but in synthesis. Where many market assessments stop at headline figures, this analysis traces the structural forces that will define competitive positioning over the next seven years. Readers who approach this document as a strategic compass rather than a static dataset will find a clear pathway through an environment characterized by both robust demand fundamentals and intensifying operational complexity.
Industry Trajectory and Structural Momentum
The market has demonstrated consistent expansion across the historical review window, recovering from mid-cycle fluctuations and establishing a higher baseline entering the forecast horizon. After reaching a valuation of 541.0 million USD in the base year of 2025, the sector moves into a projected growth phase that extends through 2032. The compound annual growth rate of 5.6 percent reflects a measured but durable expansion profile, one that rewards participants capable of balancing volume scale with margin discipline.
This trajectory is underpinned by several interlocking dynamics. Consumer demand continues to favor seafood protein as a cornerstone of modern dietary patterns, while retail and food service channels alike are expanding their premium cold-cut and prepared protein assortments. At the same time, the production ecosystem is responding to supply-side pressures ranging from raw material sourcing constraints to evolving regulatory expectations. The interplay between these demand-pull and supply-push forces creates a landscape where operational readiness, rather than market entry alone, determines which organizations capture disproportionate share.
Our forecast framework extends through 2032, tracing a path from the 587.32 million USD expected in 2026 to a projected 788.0 million USD by the terminal year of the analysis window. The progression is not a simple linear extrapolation; it incorporates the shifting weight of channel consumption, the maturation of regional supply networks, and the cadence of product innovation that will redefine value perception among end consumers. Executives who map their internal planning against this progression will be better positioned to synchronize capacity investments, inventory strategies, and go-to-market timing with the actual pace of market absorption.
Competitive Architecture and Strategic Positioning
The competitive landscape is defined by a concentration profile that rewards scale, brand equity, and channel relationships while leaving room for differentiated specialists to capture premium niches. According to the concentration metrics embedded in our analysis, the top three firms account for approximately 32 percent of the market, and the top five together command roughly 45 percent. This structure indicates a moderately consolidated arena where leading incumbents retain meaningful influence over pricing norms, supplier relationships, and category standards, yet where fragmentation below the top tier allows for opportunistic positioning by agile operators.
Across North America, Europe, and select international nodes, a diverse set of manufacturers is shaping the category. Long-established producers such as Acme Smoked Fish Corporation and Haifa Smoked Fish have built distribution footprints that span retail and foodservice, with private label partnerships and broad cold-smoked portfolios anchoring their relevance to large-scale buyers. Operators like Honey Smoked Fish Co., Boston Smoked Fish Co., and Forman & Field emphasize craftsmanship narratives, leveraging traditional smoking methods, local sourcing, and heritage positioning to command premium price points. Meanwhile, vertically integrated and export-oriented players including Bakkafrost Scotland, Trident Seafoods, and Suempol Sp. z o.o. balance volume production with geographic diversification, supplying fresh and smoked salmon variants across multiple destinations.
Recent corporate activity underscores the competitive intensity. In early 2026, Trident Seafoods expanded its smoked salmon line with a premium King Smoked Salmon offering, signaling a direct push into the higher-value tier. Around the same period, Echo Falls Seafoods, operating under Ocean Beauty Seafoods, unveiled flavor and retail packaging innovations for salmon caviar products at Seafood Expo North America, extending the category footprint beyond whole fillet formats. Natural Grocers entered the retail assortment landscape with a private-label Wild Smoked Salmon line featuring sockeye and coho varieties, certified under the Marine Stewardship Council and cold smoked in small batches at a seaside smokehouse. This launch illustrates how retailer-branded offerings continue to pressure branded manufacturers while also raising the bar for quality signaling and traceability.
Not all developments are expansionary. The category has also been shaped by product integrity events that reinforce the centrality of food safety as a strategic asset. In late 2025, both Haifa Smoked Fish and Acme Smoked Fish issued voluntary recalls related to potential Listeria contamination in cold-smoked products, with one involving a private label assortment tied to a major retailer. These episodes highlight the operational accountability that accompanies cold-smoked production, particularly under the FDA's Fish and Fishery Products Hazards and Controls Guidance, which mandates rigorous sanitation and environmental monitoring for Listeria in cold-smoked environments. For decision-makers, the strategic implication is clear: quality assurance infrastructure, supplier oversight, and rapid response capability are competitive differentiators, not merely compliance functions.
Demand Channels and Product Form Evolution
The consumption architecture of the market is distributed across retail and food service channels, each with distinct purchase drivers, format requirements, and price sensitivity profiles. Retail demand favors branded differentiation, convenient packaging, and clear quality credentials, while food service demand emphasizes consistency, portion control, and menu versatility. Our segmentation analysis examines how these channels interact with product types, revealing where margin opportunities concentrate and where volume-led strategies remain viable.
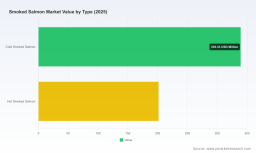
Within product form, cold-smoked and hot-smoked preparations serve different culinary applications and consumer experiences. Cold-smoked offerings generally align with appetizer, deli, and premium retail formats, where texture, aroma, and presentation are primary purchase drivers. Hot-smoked products, by contrast, often connect with ready-to-eat meal occasions and foodservice menus that prioritize warmth, robustness, and ease of preparation. The balance between these forms shapes production planning, smokehouse utilization, and the product innovation agenda of leading manufacturers.
Smoked Salmon Market
Innovation activity in recent months points to a broader category expansion beyond traditional fillet formats. Flavor experimentation, packaging refinement, and the introduction of derivative products such as salmon caviar indicate that manufacturers are seeking incremental growth through differentiation rather than relying solely on volume gains. Retailers and private label operators are simultaneously curating assortments that emphasize species variety, certification signals, and small-batch production narratives. This dual pressure from branded producers and retailer offerings is reshaping shelf strategy and menu integration across both channels.
Regulatory Environment and Trade Friction
Regulatory and trade conditions form a persistent layer of complexity in the smoked salmon market. U.S. import requirements and permitting regimes apply to many fishery products, including smoked salmon from certain origins, driven by disease and health standard considerations. These restrictions can influence sourcing strategies, lengthen lead times, and create volatility in cross-border supply planning. At a regional level, facility-level export constraints have also been observed, with indications that certain operations may face ongoing limitations on shipments to the United States into the first half of 2026. Such disruptions can cascade through downstream distribution networks, making geographic diversification and multi-origin sourcing strategically valuable.
On the domestic compliance side, the enforcement of the FDA's hazard controls guidance places cold-smoked production under continuous scrutiny for sanitation and environmental monitoring. This regulatory backdrop elevates the importance of validated process controls, supplier verification, and documentation rigor. For organizations evaluating capacity investments or supplier partnerships, the compliance burden is not a peripheral concern but a core determinant of operating risk and brand reputation. Our report integrates these regulatory considerations into the broader market framework, enabling readers to assess where friction is likely to persist and how leading operators adapt their operating models in response.
Strategic Relevance for 2026 Decision-Making
The strategic utility of this research for 2026 planning is rooted in its ability to connect macro momentum with operational reality. Executives facing capital allocation decisions can use the growth trajectory and concentration profile to calibrate expectations around market entry difficulty, share capture potential, and the realistic cadence of revenue scaling. Product and innovation teams can align their roadmaps with the observed direction of channel preferences, species and format diversification, and the certification and quality signals that increasingly influence purchase behavior. Supply chain and procurement leaders can benchmark their sourcing strategies against a backdrop of trade restrictions, multi-origin supply dynamics, and the heightened accountability surrounding cold-smoked safety controls.
This report is designed to support scenario-based thinking. Rather than presenting a single predetermined outcome, it structures the evidence so that leadership teams can test assumptions about pricing power, channel mix, capacity expansion, and geographic prioritization. The analysis examines how concentration dynamics affect competitive response times, how regulatory and trade conditions shape the cost and reliability of supply, and how product innovation cycles influence category perception and consumption frequency. Each of these dimensions is mapped to practical decision points, allowing subscribers to translate intelligence into planning inputs with precision.
In a market where the difference between effective and ineffective strategy often comes down to the quality of early-stage information, this study provides the granularity needed to move beyond broad assumptions. The macro outlook establishes the size and pace of the opportunity; the competitive and operational analysis reveals who is acting, how they are acting, and where the structural pressures are most acute; and the channel and product-form discussion clarifies where value creation is most defensible. Together, these elements form a decision-support foundation that is intended to be referenced repeatedly throughout the planning cycle, not merely read once and filed.
Smoked Meats Market
What This Study Delivers
Our methodology combines historical performance review with a seven-year forecast, anchored in a base year of 2025 and extending through 2032. The study examines total market size progression, growth rate assumptions, and the structural components that drive divergence across regions, product types, and applications. Segmentation is presented with the analytical depth required to understand relative scale and strategic relevance, while preserving the confidentiality of the finer breakdowns that constitute the full intelligence asset.
The competitive section profiles the companies that materially influence supply, pricing, and category direction, integrating recent developments such as new product introductions, private label expansions, packaging and flavor innovations, and product integrity events. These developments are contextualized within broader industry dynamics, including macro import patterns for seafood products, the weight and value share of salmon within those imports, and the specific regulatory requirements that shape production and trade. By weaving together company-level action with sector-level conditions, the report enables readers to interpret discrete events as part of a coherent strategic narrative.
Beyond the published segments, the complete study contains detailed regional and application-level breakdowns, type-specific evolution paths, company profiles with operational context, and scenario-oriented interpretation that supports targeted planning. These components are structured to answer the questions that executive teams repeatedly encounter: where growth is concentrated, which players are positioned to benefit, how regulatory and trade conditions alter the cost of participation, and what product and channel moves are most likely to resonate with demand. The report is therefore both an information resource and a planning instrument, intended for use in budgeting, sourcing strategy, product portfolio review, and competitive benchmarking.
Conclusion: Positioning for Durable Advantage
The smoked salmon market in 2026 is neither a nascent category nor a mature commodity play. It is a differentiated protein segment with steady growth characteristics, meaningful concentration among leading operators, and a competitive environment that increasingly rewards quality signaling, channel readiness, and operational discipline. The organizations that navigate the next phase most effectively will be those that treat intelligence as a strategic input rather than a retrospective summary.
This research publication has been designed to support that approach. It provides the scale and trajectory needed to frame opportunity, the competitive and regulatory context needed to manage risk, and the segmentation depth needed to prioritize action. For leaders shaping 2026 strategy, the value lies in using the analysis to pressure-test assumptions, align cross-functional plans, and identify the specific moves that convert market momentum into durable advantage. The full report extends far beyond the outline presented here, offering the complete dataset, company-by-company detail, and interpretive guidance necessary to make those decisions with confidence.
For detailed analysis of this topic, please visit the official page: Smoked Salmon Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


