



PW Consulting: Server Cabinet Market Hits $330M in 2025, Projected 9.1% CAGR to 2032

The Strategic Imperative of Server Cabinet Infrastructure in the Age of AI
The modern data center is no longer merely a repository for digital information; it is the physical substrate of artificial intelligence. As computational workloads shift from general-purpose processing to high-density GPU clusters and AI training environments, the foundational infrastructure that houses these assets—the server cabinet—has emerged as a critical strategic component. For enterprise decision-makers, IT architects, and supply chain leaders, understanding the nuanced dynamics of the server cabinet market is no longer optional. It is a prerequisite for operational resilience, cost efficiency, and technological competitiveness.
PW Consulting's latest in-depth research on the Server Cabinet Market offers a comprehensive lens into this evolving landscape. This article serves as a strategic overview of the market's trajectory, highlighting the macroeconomic forces, competitive pressures, and technological shifts that define the sector. It is designed to contextualize the findings of our full report, providing executives with the necessary framework to appreciate the depth of intelligence available in the complete study.
The transition from traditional enterprise computing to AI-driven hyperscale environments has fundamentally altered the requirements for rack and cabinet systems. Power density, thermal management, and modularity are no longer secondary considerations; they are primary drivers of procurement strategy. As organizations plan their infrastructure roadmaps through 2032, the ability to anticipate market shifts, understand competitor moves, and evaluate regional supply dynamics will separate industry leaders from followers.
This analysis draws upon extensive historical data and forward-looking projections to map the growth trajectory of the sector. By examining the interplay between semiconductor value chains, raw material volatility, and the escalating demands of high-performance computing, we uncover the underlying currents shaping the market. The following sections detail the market size evolution, the competitive architecture among key players, and the dynamic forces driving demand.
Market Size and Growth Trajectory: A Decade of Expansion
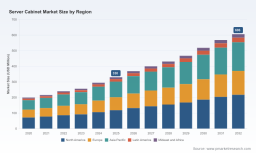
The server cabinet market has demonstrated consistent and robust growth over the past five years, reflecting the broader expansion of global data center capacity. Historical data from 2020 through 2025 reveals a steady upward trend, with the market expanding from approximately 200.0 million USD in 2020 to 330.0 million USD in 2025. This growth underscores the increasing reliance on structured physical infrastructure to support digital transformation initiatives across industries.
Looking ahead, the forecast period from 2026 to 2032 indicates continued acceleration. The market is projected to reach 368.91 million USD in 2026, with growth compounding annually at a CAGR of 9.1 percent. By the end of the forecast horizon in 2032, the market is expected to attain a revenue scale of 606.0 million USD. This trajectory suggests that demand for server cabinet solutions will remain resilient, driven by the proliferation of data-intensive applications and the ongoing construction of new data center facilities.
It is important to note that while the server cabinet market is a distinct segment, it operates within a broader enclosures ecosystem that has also shown significant expansion. Independent industry data points to the wider server rack cabinet enclosures market growing from 3.07 billion USD in 2025 to 3.37 billion USD in 2026, reflecting a CAGR of 9.93 percent. This broader context reinforces the notion that physical infrastructure investment is scaling in tandem with computational demands, validating the strategic importance of focused market intelligence.
For stakeholders, these figures are not merely statistics; they represent planning parameters. Capital expenditure budgets, procurement cycles, and capacity planning must all align with this growth rhythm. The consistency of the CAGR suggests that the market is maturing but still possesses ample room for expansion, particularly as new technological paradigms emerge.
Competitive Landscape: Dominance and Differentiation
The server cabinet market is characterized by a concentrated competitive structure, with a small group of established players commanding a significant share of the revenue pool. Market concentration data indicates that the top three companies account for 70.0 percent of the market, while the top five firms collectively hold 85.0 percent. This level of consolidation implies that incumbents possess substantial resources, established distribution networks, and deep technical expertise, creating high barriers to entry for new competitors.
Among the leading entities, several companies have distinguished themselves through specialized offerings tailored to the evolving needs of modern data centers. Vertiv Group Corp., headquartered in Ohio, USA, has positioned itself at the forefront of the AI infrastructure wave. The company focuses on integrated power and cooling solutions paired with modular high-density rack enclosures specifically engineered for AI and GPU workloads. Their recent product launches highlight a commitment to supporting power densities exceeding 50kW per rack, incorporating advanced thermal management and liquid cooling compatibility.
Eaton Corporation plc, based in Ireland, brings a different strength to the market. Their offering emphasizes advanced power management and reliability-focused server rack and cabinet systems. In an environment where uptime and energy efficiency are paramount, Eaton's approach appeals to enterprises seeking robust, mission-critical infrastructure. Meanwhile, Rittal GmbH & Co. KG, a German manufacturer, provides flexible modular racks and enclosures tailored to diverse deployment needs, offering adaptability for organizations with varied spatial and operational constraints.
Schneider Electric SE, headquartered in France, continues to be a major force with its NetShelter rack solutions, which integrate power, cooling, and monitoring capabilities into unified systems. This holistic approach simplifies management and reduces integration friction for large-scale deployments. On the North American front, L-com, based in Massachusetts, has focused on high-density networking equipment with 42U server rack cabinets available in multiple depth options. Their recent launch of new black and white variants with three depth configurations demonstrates responsiveness to specific networking density requirements.
Other notable players contribute specialized expertise to the ecosystem. Chatsworth Products, Inc., located in California, offers the ZetaFrame Cabinet System designed for high-density deployments and AI/HPC environments. AMCO Enclosures, in Illinois, provides custom electronic racks, cabinets, and shielded enclosures, catering to niche requirements that standard products may not address. Longhorn Reels, based in Texas, has gained attention for precision-engineered custom server rack systems for AI data centers, and recently expanded its manufacturing capabilities in early 2026 to meet the surging demands of AI data centers and chip manufacturing facilities. Martin Enclosures, in New Hampshire, emphasizes high-performance server racks and cabinets built in the USA, while RackSolutions offers high-quality racks and cabinets for data center and enterprise use across the country.
These companies are not merely competing on price; they are competing on technological capability, supply chain reliability, and alignment with the specific demands of next-generation computing. Recent developments illustrate this dynamic. Vertiv's October 2025 product launch addressed the need for high-density enclosures supporting over 50kW per rack with liquid cooling compatibility. L-com's January 2025 launch focused on depth options for high-density networking. Longhorn Reels' February 2026 expansion signaled the industry's response to the growing needs of AI and chip manufacturing.
Market Dynamics and Structural Shifts
The server cabinet market is being reshaped by a confluence of macro trends, regulatory influences, and material realities. Understanding these dynamics is essential for anticipating future demand patterns and supply chain risks.
Server Chassis Market
A primary driver is the rise of AI and high-density GPU deployments. Traditional server cabinets were designed for relatively modest power densities, but modern AI workloads require systems capable of handling extreme thermal loads and power delivery. The industry is increasingly demanding modular, high-power server cabinet systems exceeding 50kW per rack. This shift is not incremental; it represents a fundamental redesign of physical infrastructure. Cabinets must now accommodate advanced cooling solutions, including liquid cooling compatibility, and support the structural and electrical requirements of GPU-accelerated servers.
The semiconductor industry's role in this ecosystem cannot be overstated. According to a recent report from the Semiconductor Industry Association, semiconductors account for 95 percent of an AI Data Server Rack's value. This statistic highlights the deep interdependence between cabinet infrastructure and the broader semiconductor supply chain. As semiconductor availability, pricing, and technological advancements fluctuate, they directly influence the value proposition and design priorities of server cabinets. Procurement strategies must account for this linkage, as disruptions in chip manufacturing or supply can cascade into delays and cost pressures for cabinet deployments.
Raw material costs also play a critical role in shaping market dynamics. Server cabinet manufacturing relies on steel, aluminum, and advanced components, all of which are subject to price volatility. Company filings and sector analysis from 2025 indicate that rising material costs are tied to semiconductor supply chain volatility and broader macroeconomic factors. For manufacturers, managing input costs while maintaining competitive pricing requires sophisticated supply chain management and potentially hedging strategies. For buyers, understanding these cost drivers can inform negotiation tactics and long-term contracting decisions.
Regulatory and vertical-specific demands are adding another layer of complexity. Government and defense verticals are driving requirements for modular, scalable rack solutions that support secure, high-density computing environments. These sectors often impose stringent security, durability, and compliance standards, creating specialized demand pockets that reward manufacturers with the capability to deliver customized, certified solutions. As public sector investments in secure computing infrastructure grow, these requirements will increasingly influence overall market composition.
Segmentation Insights and Strategic Considerations
While the full report provides an exhaustive breakdown of market segmentation, certain high-level structures warrant attention for strategic planning. The market is analyzed across multiple dimensions, including regional distribution, product type, and application vertical. Each of these axes reveals important patterns regarding demand concentration, growth potential, and competitive positioning.
Geographically, the market exhibits distinct regional characteristics. Historical and projected data suggest that North America, Europe, and Asia Pacific represent significant revenue pools, with Latin America and the Middle East and Africa contributing additional, albeit smaller, shares. Regional dynamics are influenced by the location of hyperscale data center campuses, enterprise IT spending patterns, and local manufacturing or supply chain capabilities. Decision-makers operating across multiple regions must navigate differences in regulatory environments, logistics infrastructure, and competitive intensity. The complete report offers detailed regional analysis to support localization strategies and market entry evaluations.
In terms of product type, the market is segmented between open frame racks and enclosed cabinets. Enclosed cabinets typically command a larger share of the revenue, reflecting the growing need for security, thermal control, and organized cable management in modern facilities. Open frame racks remain relevant for specific use cases where airflow and accessibility are prioritized over enclosure. The balance between these types is shifting as deployment environments become more complex and space-constrained. Understanding the relative demand for each type helps inform product portfolio decisions and procurement specifications.
Server Cabinet Market
Application segmentation further illuminates where demand is originating. Hyperscale data centers, enterprise data centers, and colocation facilities each present unique requirements. Hyperscale operators prioritize scale, efficiency, and integration with advanced cooling and power systems. Enterprise data centers often balance performance with flexibility and existing infrastructure compatibility. Colocation providers must meet the diverse needs of multiple tenants while maintaining operational efficiency. The interplay among these application segments influences product design, service offerings, and pricing models. The full study delves into these application-level nuances, providing actionable guidance for targeting specific customer profiles.
Value of the Full Research for 2026 Decision-Making
As enterprises finalize their 2026 strategies and look toward the remainder of the decade, the Server Cabinet Market research from PW Consulting provides a critical decision-support tool. The insights contained in the full report go beyond high-level market sizing to offer granular, actionable intelligence that can inform procurement, product development, investment, and competitive positioning.
For procurement and operations leaders, the report delivers detailed segmentation data, including regional revenue splits, type-based market shares, and application-specific demand patterns. These figures enable precise demand forecasting, inventory planning, and supplier evaluation. By understanding which regions and applications are expanding most rapidly, organizations can align their sourcing strategies and prioritize high-growth opportunities.
For product managers and engineering teams, the competitive profiles and recent development tracking offer a window into the innovation landscape. Understanding the specific capabilities that competitors are bringing to market—such as high-density enclosures, liquid cooling compatibility, modular flexibility, and custom engineering—helps identify gaps and differentiation opportunities. The report's analysis of product launches, expansions, and strategic moves allows teams to benchmark their own roadmaps against industry trends.
For executives and investors, the market concentration data and macro dynamics provide context for assessing industry structure and risk. The high concentration among top players suggests that scale, brand, and technological leadership are valuable assets. At the same time, the presence of specialized manufacturers serving niche requirements indicates that targeted innovation can carve out sustainable positions. The integration of raw material cost dynamics, semiconductor value chain linkages, and regulatory drivers equips decision-makers with a holistic view of the forces that will shape profitability and growth.
The complete report also addresses the practical aspects of data interpretation, offering frameworks for translating market intelligence into strategy. Whether the goal is to evaluate market entry, assess competitor threats, optimize supply chain resilience, or align capital allocation with demand forecasts, the research provides the foundational data and analysis needed to act with confidence.
Conclusion: Navigating Infrastructure Transformation
The server cabinet market stands at the intersection of physical infrastructure and digital ambition. As AI workloads intensify, data centers expand, and computational demands push the boundaries of power and thermal management, the cabinet that houses the equipment is no longer a passive enclosure. It is an active enabler of performance, efficiency, and reliability.
The growth trajectory projected through 2032 reflects the sustained importance of this infrastructure layer. With a CAGR of 9.1 percent and a market scale extending beyond 600 million USD by the end of the forecast period, the sector offers both opportunity and complexity. Navigating this environment requires more than intuition; it demands rigorous, up-to-date market intelligence.
PW Consulting's comprehensive Server Cabinet Market research is designed to meet that need. By combining historical analysis, forward-looking projections, competitive profiling, and dynamic context, the report equips stakeholders with the insights required to make informed, strategic decisions. The full study reveals the detailed segmentation, regional breakdowns, and application-specific data that underpin the market's evolution, providing the depth necessary for precise planning.
For leaders who recognize that the future of computing is inseparable from the quality of its physical foundation, this research offers a clear path forward. Access the complete report to unlock the full spectrum of data, analysis, and strategic recommendations that will drive your organization's success in the years ahead.
For detailed analysis of this topic, please visit the official page: Server Cabinet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


