



PW Consulting: Billet Caster Market to Hit $376M by 2032, 5.5% CAGR

Navigating the Next Wave: Strategic Intelligence for the Billet Casters Market Through 2032
The global billet casters market is entering a decisive phase of evolution. As steelmakers and aluminum producers balance capacity expansion with the imperative for higher metallurgical quality, the equipment that transforms molten metal into usable billets has become a critical leverage point in the value chain. PW Consulting's latest in-depth market research on the Billet Casters Market is designed to give executives, investors, and technology strategists the clarity required to navigate this landscape through 2032. This article previews the strategic architecture of the study, outlining how its data-driven framework, competitive mapping, and operational cost intelligence can be translated into actionable decisions in 2026 and beyond.
Why 2026 Demands a Reset in Equipment Strategy
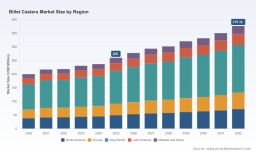
Over the past half-decade, the market has transitioned from a post-pandemic recovery posture to a structurally recalibrated growth trajectory. Historical performance from 2020 through 2025 reveals a market that weathered supply chain disruptions, shifting demand cycles, and capital expenditure hesitancy, yet sustained a clear upward path. Building on that foundation, the forecast window extending to 2032 projects a compound annual growth rate of 5.5 percent, measured in USD millions. This trajectory is not merely a top-line exercise; it reflects the cumulative effect of modernizing legacy casting lines, integrating high-speed continuous casting machines, and addressing the rising demand for precision-defined billets in advanced steel grades and non-ferrous applications.
For decision-makers evaluating capital allocation in 2026, the strategic question is no longer whether the market is expanding, but where the margin for competitive advantage lies. Upgrading a single casting strand, selecting between vertical and horizontal configurations, or incorporating electromagnetic stirring and dynamic secondary cooling can reshape throughput, energy consumption, and scrap rates over the life of a plant. The research underlines that these are not isolated equipment purchases; they are strategic bets on future metallurgical performance, operational resilience, and total cost of ownership. A nuanced reading of market momentum, paired with granular technology and cost benchmarks, helps executives prioritize investments that compound value rather than simply adding capacity.
What the Research Delivers: Content Built for Execution
This study is structured to move beyond descriptive market size and into the operational and commercial territory that influences real budgets and timelines. It opens with a rigorous reconstruction of historical demand through 2025, establishing a defensible baseline against which the 2032 outlook can be stress-tested. From there, the analysis extends into forward-looking scenarios that account for plant modernization cycles, regional capacity additions, and the interplay between product type adoption and end-use requirements.
The report also dissects the economics that shape purchasing decisions. Equipment valuation is influenced not only by the caster itself but by the surrounding ecosystem of design, fabrication, integration, and commissioning. Precision machining, welding, and hydraulic system integration represent a significant share of project value, while research and development together with certification activities add further layers of cost and risk. High-grade alloy steels, refractory materials, and copper for mold tubes and specialized components account for a substantial portion of the total caster cost. On the infrastructure side, greenfield installations encompassing civil engineering and ancillary equipment can reach or exceed fifty million dollars. These cost structures matter because they determine the financial logic behind renovation versus replacement, and because they vary meaningfully across segments, geographies, and machine specifications.
Beyond costs, the study connects technical choices to regulatory and standards-driven realities. Billet casters operating in today's environment must satisfy metallurgical industry standards and safety certifications, particularly when processing high-alloy grades and ultra-large sections approaching diameters of 1000 mm. The research translates these compliance requirements into procurement implications, illustrating how specification rigor, testing protocols, and documentation expectations influence vendor selection, project timelines, and long-term service obligations.
Casters Market
Competitive Landscape and Recent Moves That Matter
The market exhibits a consolidated structure, with the top three participants collectively holding a substantial share and the top five extending that footprint further. This concentration creates a landscape where technology leadership, service networks, and localized execution capabilities are often as important as headline pricing. The research profiles the core companies shaping this environment, examining their engineering philosophies, product families, and go-to-market positioning.
Among the leaders, SMS group GmbH continues to advance its Concast division's custom billet caster offerings, spanning vertical and curved designs with strand configurations from one to ten and casting speeds up to seven meters per minute. Danieli & C. Officine Meccaniche S.p.A. positions its Q-CAST billet casters with POWER MOULD and HY-POWER oscillation systems as a route to higher productivity and billet and bloom quality across varied steel market requirements. Primetals Technologies Limited, through its wholly owned subsidiary Concast India Private Ltd., emphasizes modular casters for mini-mills with a focus on square and rectangular sections and high-speed rebar integration, while Electrotherm E&T Ltd. addresses smaller heat sizes down to five tons with compact, modular designs suited to existing ingot-to-billet conversion scenarios. Concast India Private Ltd. extends this modular logic with five- to seven-strand configurations tailored for steel billet production in mini-mill environments.
What distinguishes the current period is the cadence of live project activity. In October 2025, Danieli & C. Officine Meccaniche S.p.A. secured a contract for a new three-strand continuous casting machine designed to produce ultra-large high-alloy round billets up to 1000 mm in diameter, including specialized grades such as P91 and P92. In January 2026, SMS group GmbH was awarded a modernization contract for an eight-strand continuous caster at a second plant location, with Dynamic Mechanical Soft Reduction intended to improve billet inner quality. Earlier in July 2025, Concast India Private Ltd. received an order for a new billet caster handling 100- to 200-mm square sections, integrated with a high-speed rebar outlet. In April 2025, Danieli's service team completed an upgrade of a six-strand billet caster in Italy, reinforcing the recurring value of modernization alongside new capacity.
These developments are not isolated headlines; they are signals. They reveal where premium specifications are being demanded, how service-led upgrade cycles are being monetized, and why integration with downstream outlet configurations is increasingly part of the value proposition. The study maps these patterns to competitive behavior, highlighting where incumbents defend share through advanced casting technologies and where challengers compete on modularity, footprint, and integration with smaller melt shops.
Dynamics Shaping Investment Logic in 2026
Several intersecting dynamics will determine how aggressively capital is deployed and how equipment specifications are negotiated. Energy efficiency has emerged as a decisive differentiator for high-end multi-strand machines. Advanced casters equipped with electromagnetic stirring, dynamic secondary cooling, and heightened automation command a premium price range between 15 million and 45 million dollars per machine. The business case for such specifications depends on the balance between throughput gains, metallurgical consistency, and operating cost reduction over the machine's service life.
At the same time, total project economics must account for more than the equipment invoice. Greenfield installations require civil engineering, utilities interfaces, and ancillary equipment, pushing aggregate spend to fifty million dollars or more in certain configurations. For organizations operating in brownfield contexts, the calculus shifts toward footprint compatibility, retrofit complexity, and the ability to sustain production continuity during installation and commissioning. The research helps decision-makers compare these pathways using consistent cost and capability benchmarks rather than ad hoc quotations.
Billet Casters Market
Another important dynamic is the tightening relationship between product specifications and downstream performance. As producers target higher-alloy steels and increasingly demanding non-ferrous billets, the tolerance for internal defects, centerline segregation, and surface quality issues narrows. This raises the strategic importance of casting speed control, mold design, oscillation systems, and cooling precision. The report connects these technical levers to segment-level demand signals and to the competitive responses of equipment suppliers, enabling procurement teams to evaluate proposals against a clearer standard of operational readiness.
Strategic Applications for 2026 Decision-Making
This research is intended to be used, not merely read. For capital planning teams, it provides a structured basis to align budget cycles with realistic equipment lead times, installation complexity, and the cost architecture of competing solutions. For technology and procurement leaders, it offers a way to benchmark vendor claims on oscillation systems, mold technology, strand configuration, and downstream integration against the broader market's observed direction. For strategy and corporate development functions, the study clarifies where concentration creates bargaining power and where niche configurations can serve as differentiators in specialized applications.
- Prioritize investment pathways that balance immediate capacity needs with long-term quality and energy performance, using the forecast period to test multiple upgrade and expansion scenarios.
- Evaluate proposals against consistent cost and specification baselines that include machining, welding, hydraulic integration, R&D, certification, and ancillary infrastructure rather than comparing machine prices in isolation.
- Align procurement with regulatory and standards expectations for high-alloy grades and ultra-large sections, ensuring that compliance requirements are factored into vendor selection and project scheduling.
- Use competitive intelligence to anticipate where incumbents will defend share through advanced casting technologies and where modular, smaller-footprint solutions can open opportunities in mini-mills and conversion projects.
- Incorporate recent project activity into scenario planning, recognizing that large-diameter high-alloy billets and dynamic soft reduction upgrades reflect shifting performance priorities that may influence future specification trends.
Where to Focus Next
The full scope of this research extends into more detailed comparative frameworks, scenario analyses, and operational benchmarks that are essential for precise budgeting and vendor evaluation. Because competitive dynamics, cost structures, and specification trends vary meaningfully across segments and project types, the most valuable intelligence resides in the granular layers of the study rather than in the headline totals alone. Readers seeking to translate market momentum into concrete capital decisions will find the complete report most useful when paired with internal plant data, project timelines, and specification roadmaps.
The market for billet casters is no longer defined by volume growth alone. It is being reshaped by quality demands, energy economics, compliance rigor, and the pace of technological differentiation among leading suppliers. PW Consulting's Billet Casters Market research is built to help organizations read these signals correctly and act on them with confidence. For executives preparing 2026 decisions and beyond, the study offers a disciplined way to connect market direction to equipment strategy, cost logic, and competitive positioning. The next step is to examine the detailed intelligence that underpins this outlook and to apply it within the specific constraints and ambitions of each organization's operating environment.
For detailed analysis of this topic, please visit the official page: Billet Casters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


