



PW Consulting: Armrest Market to Hit $20.4B by 2032, 5.81% CAGR

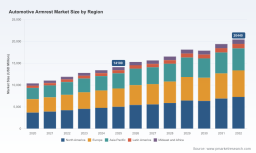
Strategic Intelligence for the Automotive Armrest Market: Navigating Growth Through 2032
The automotive interior landscape is undergoing a quiet but profound transformation. What was once considered a utilitarian component—fixed, functional, and largely overlooked—is now emerging as a critical touchpoint for comfort, sustainability, and modular design. As seating systems evolve from passive ergonomics to active user experiences, the automotive armrest has captured the attention of OEMs, tier suppliers, and aftermarket strategists alike. This shift is not merely aesthetic; it reflects deeper structural changes in vehicle architecture, consumer expectations, and regulatory frameworks. For executives navigating the 2026–2032 horizon, understanding the trajectory of this segment requires more than surface-level market estimates. It demands a disciplined, forward-looking analysis that connects material innovation, competitive consolidation, and regulatory pressure to actionable portfolio decisions.
Our latest research publication on the automotive armrest market is designed precisely for that purpose. Built on a rigorous historical baseline spanning 2020–2025 and extended through a comprehensive forecast window to 2032, the study provides a structured lens into how revenue, adoption patterns, and competitive positioning are being reshaped. The market has demonstrated consistent upward momentum over the past half-decade, with steady expansion across product architectures and material choices. As organizations prepare their strategic roadmaps for the 2026 fiscal year and beyond, this intelligence serves as a critical calibration tool—helping leaders separate cyclical noise from genuine structural inflection points.
Why 2026 Marks a Pivotal Inflection Point
The automotive supply chain enters 2026 under a fundamentally different operating environment than the one that defined the early 2020s. Electrification platforms continue to reconfigure interior packaging constraints, consumer preferences increasingly reward tactile comfort and personalized control surfaces, and regulatory bodies are tightening requirements around component safety, material sourcing, and lifecycle footprints. Within this context, armrest systems have moved from being treated as commodity trim pieces to becoming integrated elements of broader cockpit architecture.
Several forces converge to make this year particularly consequential for strategic planning. First, modular interior architectures are gaining traction across multiple vehicle segments, allowing sliding, folding, and adjustable configurations to be tested and deployed at scale. Second, the push toward lightweight, bio-sourced, and recycled material inputs is accelerating across seating supply chains, creating new performance benchmarks and procurement trade-offs. Third, regulatory developments—including UN Regulation No. 17 requirements for locking systems on comfort devices and updated safety guidelines issued by major oversight agencies in late 2024—are reshaping design validation cycles and compliance cost structures. These dynamics do not operate in isolation. They interact with manufacturing footprints, supplier partnerships, and regional demand rhythms in ways that can materially alter margin profiles and time-to-market assumptions. For decision-makers, the margin for guesswork has narrowed. What is needed is a research framework that connects macro trends to segment-level realities without over-simplifying the complexity on the ground.
A Research Framework Built for Execution
This market study is structured to bridge strategic inquiry and operational execution. Rather than presenting high-level aggregates in isolation, the report is organized around the dimensions that matter most to product planning, procurement, and competitive positioning teams. By integrating historical baselines with a forward-looking projection horizon through 2032, the analysis provides a continuous narrative that leaders can use to stress-test assumptions across multiple scenarios.
The report delivers actionable intelligence across several practical dimensions:
- Comprehensive sizing and trajectory analysis that contextualizes recent performance within long-term growth trends, helping organizations separate baseline expansion from segment-specific accelerations or decelerations.
- A structured breakdown of product architectures and functional configurations, enabling engineering and product teams to evaluate which form factors are gaining traction and under what usage conditions.
- Material and manufacturing pathway analysis that maps the shift toward sustainable inputs, recycled content, and lightweighting strategies, including the performance and cost implications of bio-sourced alternatives and energy-absorbing foam systems.
- Channel and go-to-market dynamics that distinguish how volume flows through integrated OEM supply relationships versus independent aftermarket ecosystems, with emphasis on the operational implications of each pathway.
- Competitive landscape profiling that examines how leading suppliers differentiate through seating system integration, modular console mechanisms, ergonomic component specialization, storage-enabled designs, and heated or comfort-enhanced variants.
- Regulatory and compliance context that translates safety standards and vestigial rule updates into practical implications for design validation, locking mechanisms, and component injury-risk considerations.
Each section is designed to answer the kinds of questions that surface in cross-functional planning sessions: where is demand consolidating, which material transitions are nearing commercial maturity, how are regional demand patterns reshaping sourcing priorities, and what does competitive differentiation look like when armrests are treated as part of a broader interior system rather than a standalone component. By presenting these insights in a cohesive framework, the study equips teams to move from observation to action with greater precision.
Automotive Headrest Market
Competitive Dynamics and the New Differentiation Playbook
The supplier landscape for automotive armrests is characterized by a mix of established interior specialists, seating system integrators, and regional players with deep manufacturing and engineering capabilities. Market concentration remains measured, with a handful of firms holding meaningful share and a broader field competing through engineering differentiation, regional partnerships, and material innovation. In such an environment, the ability to anticipate which competitive moves will compound over the next several years is as important as understanding current positioning.
Several leading companies illustrate the strategic directions currently shaping the market. Adient continues to expand its integrated seating systems capability, including armrest and console integration, reinforced by recent operational moves such as the acquisition of a seating foam plant that strengthens component production continuity and vertical coordination. FORVIA Faurecia has been advancing modular interior concepts, including on-demand center console systems with sliding mechanisms that enhance armrest and console functionality while incorporating sustainable materials and surface activation technologies. Grammer AG occupies a position centered on consoles and armrests for passenger vehicle interiors, with an emphasis on ergonomic components and complementary headrest solutions. TACHI-S Co., Ltd. brings manufacturing depth in seating assemblies that encompass armrest components as part of broader seat architectures. Piston Interiors focuses on practical feature differentiation, including fold-away options, storage integration, and durable latch systems for armrests and center consoles. Yanfeng Automotive Interiors extends its reach across door panels, floor consoles, and armrests, including comfort-oriented heated variants, reflecting the broader trend of treating interior surfaces as multi-functional user interfaces.
These profiles are not static. Competitive advantage is increasingly defined by how effectively suppliers can align engineering roadmaps with sustainability targets, modular design flexibility, and regional manufacturing responsiveness. The report maps these dynamics in greater detail, providing the comparative context needed to evaluate partnership opportunities, supply chain resilience, and technology adoption timing.
Recent industry developments reinforce how quickly the competitive landscape can shift. Strategic acquisitions that expand component production capability, alongside the unveiling of modular console systems with sliding armrest functionality, signal a broader movement toward integrated, adaptable interior architectures. These moves matter because they alter not only who competes, but how value is created—shifting emphasis from discrete part manufacturing toward system-level integration, comfort engineering, and material performance. For organizations assessing their own positioning, understanding the cadence and intent behind such moves is essential.
Regulatory, Material, and Operational Currents
No strategic assessment of this market is complete without addressing the operational currents that shape design choices, cost structures, and launch timelines. Regulatory requirements are one of the most influential of these currents. UN Regulation No. 17 introduces locking-system expectations for comfort devices when their presence could introduce additional injury risk, while updated oversight guidance issued in late 2024 has continued to refine how interior components are evaluated under evolving safety expectations. These frameworks do not merely impose compliance obligations; they influence architecture decisions, validation cycles, and the feasibility of certain mechanical configurations.
At the same time, material strategy is becoming a central competitive variable. Automotive seat armrest production increasingly relies on precise multi-step processes that incorporate bio-sourced and recycled inputs to reduce weight and CO2 footprint, while maintaining the durability and comfort performance expected by end users. In parallel, seat foam production continues to depend on high-density closed-cell materials engineered to meet energy-absorbing and non-flammability requirements relevant to occupant protection. Together, these material shifts create a more complex sourcing environment—one where sustainability, regulatory compliance, and functional performance must be balanced rather than treated as separate workstreams.
For procurement and engineering leaders, this means that armrest strategy is no longer confined to dimensional tolerances or cosmetic finishes. It extends into material traceability, energy-absorption performance, locking reliability, weight targets, and lifecycle impact. The research study provides the structured context needed to navigate these intersecting priorities, linking technical requirements to market-level implications.
Translating Intelligence into Strategic Action
As organizations prepare their 2026 planning cycles, the value of disciplined market intelligence lies in its ability to reduce uncertainty without oversimplifying reality. The automotive armrest market is expanding within a broader interior systems transformation, and the companies that succeed will be those that can interpret growth signals accurately, align product roadmaps with material and regulatory shifts, and position themselves relative to a competitive set that is increasingly defined by integration, modularity, and comfort engineering.
This study is designed to support that effort. It offers the historical grounding, forward-looking projections, and segment-level context necessary to evaluate investment priorities, sourcing strategies, product differentiation, and partnership structures. More importantly, it is built to help leaders ask better questions: which product configurations are gaining durable traction, where do material transitions create cost or performance trade-offs, how do regulatory developments shape design feasibility, and what competitive moves should be monitored as leading indicators rather than retrospective events.
Automotive Armrest Market
The complete analysis goes further, providing the detailed market sizing, trajectory modeling, competitive benchmarking, and segment-level context that decision-makers need to convert market signals into executable strategy. For teams responsible for seating systems, interior components, procurement planning, or competitive intelligence, the full report offers the depth required to act with confidence across the 2026–2032 horizon. Those seeking the complete dataset, regional and application-level breakdowns, material pathway comparisons, and in-depth competitive profiling are encouraged to access the full study directly through our research portal, where the complete intelligence package is available for download and internal distribution.
For detailed analysis of this topic, please visit the official page: Automotive Armrest Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


