



PW Consulting: SerDes Market Hits $900M in 2025, 13.7% CAGR to $2.2B by 2032

Navigating the SerDes Market: Strategic Intelligence for 2026 and Beyond
In the rapidly evolving landscape of high-speed data transmission, the Serial Deserializer (SerDes) market stands as a critical infrastructure backbone for modern digital ecosystems. As enterprises across healthcare, automotive, and industrial sectors demand higher bandwidth and lower latency, the strategic implications of SerDes architecture have never been more pronounced. At PW Consulting, we recognize that understanding the macro-economic trajectory of this sector is not merely an academic exercise but a vital component of capital allocation and technology roadmapping for 2026 and beyond.
This article serves as an executive preview to our latest comprehensive market research release. Our objective is to outline the strategic value this intelligence offers to decision-makers who must anticipate shifts in supply chain dynamics, competitive positioning, and technological adoption rates. The data covered herein spans a robust historical period from 2020 through the base year of 2025, with a detailed forecast extension through 2032. This longitudinal view allows stakeholders to model risk and opportunity with a granularity that short-term forecasts simply cannot provide.
Macro-Economic Trajectory and Growth Indicators
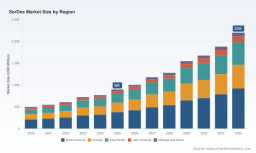
The foundational metric for any strategic investment decision is a clear understanding of market scale and velocity. Based on rigorous analysis of historical performance and forward-looking indicators, the SerDes market has demonstrated a resilient growth pattern over the past half-decade. From approximately 500.0 USD Million in 2020, the market size expanded steadily to reach 900.0 USD Million by 2025. This trajectory underscores the increasing reliance on high-speed serial links as a fundamental component of modern electronic design.
Looking forward into the forecast period extending to 2032, the momentum is projected to accelerate. The market is expected to breach the 1 billion USD Million mark during 2026, reaching 1005.28 USD Million. This growth is not linear; it reflects compounding technological demands and the proliferation of connectivity-enabled devices. By the end of the forecast window in 2032, the overall market size is anticipated to reach 2200.0 USD Million.
This expansion is underpinned by a strong Compound Annual Growth Rate (CAGR). For the period covering 2026 through 2032, the analysis indicates a CAGR of 13.7 percent. This rate of growth suggests that the SerDes market is outpacing many broader semiconductor segments, driven by specific high-demand verticals. For strategists, this percentage is a key indicator of where R&D budgets should be prioritized to capture emerging value pools. It signals a market that is not only expanding but doing so at a pace that warrants aggressive attention from both chipset manufacturers and system integrators.
It is crucial for leadership teams to note that this currency-denominated revenue is tracked in USD across all units of Million. Consistency in reporting standards ensures that cross-border investments and partnerships are evaluated on a comparable basis. The data provided in our full report eliminates ambiguity, allowing CFOs and strategic planners to model revenue projections without the friction of currency conversion assumptions or unit discrepancies.
Operational Intelligence Within the Report
A market report is only as valuable as the actionable intelligence it contains. Our research goes beyond surface-level sizing to provide deep operational insights that directly impact engineering and supply chain strategy. We understand that in the semiconductor industry, the difference between success and obsolescence often lies in the details of supply chain volatility and regulatory compliance.
SerDes Market
One significant area of focus in our analysis is the impact of raw material costs on production economics. Recent industry data indicates that aluminum-based raw materials used for PCB substrates in SerDes components have incurred significant cost increases. This volatility stems from global supply chain disruptions that have persisted through 2025. For procurement officers and production managers, understanding the magnitude of this cost pressure is essential for margin protection. Our report contextualizes these material constraints within the broader manufacturing cost structure, helping organizations factor supply chain risk into their vendor selection processes.
Furthermore, the human element of semiconductor fabrication cannot be overlooked. Our analysis highlights that skilled semiconductor fabrication labor in Asia accounts for approximately 25 percent of SerDes manufacturing costs. This labor dynamic influences where companies choose to manufacture and source components. As geopolitical tensions and labor availability shift, understanding this cost composition helps firms optimize their manufacturing footprint. The report provides the necessary context to evaluate whether near-shoring or maintaining Asian-based fabrication offers better long-term value propositions given the cost structures involved.
HSMT SerDes Chip Market
Infrastructure requirements are another critical pillar of our research. Advanced data center infrastructure, particularly within healthcare facilities, requires low-latency SerDes links for real-time imaging systems. This specific technical requirement drives demand patterns that differ from standard commercial data centers. Our report dissects these infrastructure needs, allowing technology leaders to tailor their connectivity solutions to the rigorous latency and reliability standards demanded by critical sectors like healthcare imaging.
Competitive Dynamics and Market Concentration
The SerDes market is characterized by a high degree of concentration among leading players, creating a complex competitive environment where partnerships and licensing agreements are as valuable as proprietary hardware. Our analysis details a market structure where the top three entities hold a CR3 of 72.0 percent, and the top five extend this concentration to a CR5 of 78.0 percent. This level of concentration indicates significant barriers to entry and suggests that established players possess considerable leverage over pricing and technology standards.
Prominent organizations shaping this landscape include Texas Instruments, headquartered in Dallas, Texas, USA. They offer high-speed SerDes solutions such as the DS90UB954, targeting industrial, automotive, and healthcare data transmission applications. Their presence underscores the importance of versatile solutions that can span multiple verticals. Similarly, Broadcom Inc., based in San Jose, California, USA, provides products like the BCM87412 for networking and data centers, extending into healthcare systems. Their strategy highlights the intersection of networking infrastructure and specialized medical applications.
Intel Corporation, located in Santa Clara, California, USA, supplies the Intel Agilex I-Tile SerDes for high-performance data transmission in healthcare and industrial sectors. Their focus on high-performance transmission aligns with the growing demand for compute-heavy workflows. Marvell Technology, also in Santa Clara, delivers PAM4 400G SerDes solutions that support cloud, 5G, and healthcare connectivity needs. This specific technical implementation indicates a market moving toward higher density and speed protocols to handle increased data loads.
On the intellectual property front, Synopsys Inc. from Mountain View, California, licenses DesignWare 112G SerDes IP for custom semiconductor designs, including those for healthcare and medical devices. Cadence Design Systems, based in San Jose, provides SerDes PHY IP for SoC development in similar sectors. These IP licensing models represent a distinct revenue stream and competitive dynamic compared to physical component manufacturing. Lattice Semiconductor, headquartered in Hillsboro, Oregon, USA, offers an Avant platform with leading 25 Gb/s SERDES for mid-range FPGA applications, including healthcare. This demonstrates that even within FPGA markets, specialized SerDes capabilities are a key differentiator.
International players also exert significant influence. NXP Semiconductors, based in Eindhoven, Netherlands, manufactures components for automotive and healthcare data interfaces. Analog Devices, in Wilmington, Massachusetts, USA, provides high-speed solutions supporting healthcare and 5G applications. ON Semiconductor, from Scottsdale, Arizona, USA, supplies products for industrial, automotive, and medical device connectivity. Finally, STMicroelectronics, located in Geneva, Switzerland, offers solutions for automotive and healthcare sensor fusion systems. The geographic diversity of these headquarters reflects the global nature of the supply chain, even amidst concentration risks.
Regulatory Frameworks and Sector-Specific Drivers
Technology deployment does not occur in a vacuum; it is heavily influenced by regulatory environments and reimbursement structures. Our report integrates these external forces to provide a holistic view of market viability. For instance, ISO 13485 certification for SerDes components in medical devices is required for all healthcare applications. This regulatory hurdle creates a barrier to entry that favors established players with robust quality management systems. It also dictates the timeline for new product introduction in the medical sector, requiring strategists to plan for compliance lead times.
Simultaneously, reimbursement models play a crucial role in demand generation. Medicare and private payers reimburse for healthcare devices incorporating high-speed SerDes connectivity. This financial incentive effectively subsidizes the adoption of higher-cost, higher-performance connectivity solutions in the medical field. For companies targeting the healthcare vertical, understanding the alignment between reimbursement policies and hardware specifications is a key driver of commercial success. Our research highlights how these financial flows support the wider adoption of advanced SerDes architectures in life-critical systems.
These dynamics vary significantly by application focus. While the full report breaks down value by application, it is evident that sectors like Data Centers and Automotive represent substantial value pools, driving the need for robust interfaces. The interplay between regulatory compliance, reimbursement availability, and technical performance creates a complex matrix that engineers and business developers must navigate. Our analysis provides the necessary context to understand which combinations of regulation and reimbursement create the most favorable conditions for market entry or expansion.
Strategic Implications for 2026 Decision-Making
As we move into 2026, the strategic implications of these findings are profound for enterprise leadership. The projected growth to 1005.28 USD Million in 2026 and beyond suggests that SerDes technology will remain a priority investment area. Companies that delay integration or fail to secure reliable supply chains may find themselves at a competitive disadvantage as bandwidth requirements escalate.
For procurement and supply chain executives, the cost volatility associated with raw materials and labor costs necessitates a diversified sourcing strategy. Relying on a single region or supplier type exposes the organization to risks highlighted by the aluminum substrate cost increases and the significant labor cost component in Asian fabrication. Diversification and strategic inventory management become imperative to mitigate these variables.
For technology strategists and R&D leaders, the competitive landscape defined by high market concentration suggests that partnerships may be more fruitful than outright competition for new entrants. Leveraging IP cores from leaders like Synopsys or Cadence, or collaborating with established component manufacturers like TI or Broadcom, may offer faster time-to-market than attempting to develop proprietary high-speed links from scratch. The CR3 and CR5 metrics serve as a reality check on the feasibility of independent development in this saturated space.
Furthermore, the regulatory aspect regarding ISO 13485 certification cannot be an afterthought. Product roadmaps must incorporate compliance testing early in the design phase. The correlation between reimbursement policies and hardware capabilities also suggests that value propositions should be built around the performance benefits that justify higher costs and qualify for reimbursement. Marketing and sales strategies should reflect this alignment to maximize adoption rates in healthcare and other regulated sectors.
Conclusion and Access to Full Intelligence
The SerDes market is entering a phase of accelerated expansion defined by high growth rates, concentrated competition, and rigorous regulatory demands. The data points from 2020 through the 2032 forecast provide a clear narrative of a sector vital to the future of high-speed connectivity. However, the macro-level view only scratches the surface of the complexities involved in successful market participation.
To fully leverage these insights for your organization's specific context, access to the complete dataset, segmentation details, and proprietary analysis is required. Our full report offers granular breakdowns that allow for precise modeling and risk assessment tailored to your operational needs. We invite you to visit our source webpage to download the complete study. There, you will find the detailed segmentation splits and specific regional and application data that inform the broader trends discussed here, enabling you to make fully informed strategic decisions for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: SerDes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


