



PW Consulting: Specialty Carbon Black Market to Reach $400M by 2032, Driven by 6.5% CAGR

Specialty Carbon Black Market Strategic Outlook 2026: Navigating Growth, Volatility, and Competitive Shifts
The specialty carbon black sector is entering a defining phase. As industrial formulations grow more complex and sustainability mandates tighten across major economies, decision-makers require more than backward-looking summaries. They need a forward-looking, data-grounded view of where value is shifting, which applications will absorb incremental capacity, and how leading producers are repositioning their portfolios against feedstock volatility and regulatory pressure. Our latest Specialty Carbon Black Market study is built precisely for that moment. Covering the historical window from 2020 through 2025 and extending forecasts to 2032, the analysis gives procurement leaders, strategy teams, and investors a structured lens on a market projected to reach a 2026 valuation of 270.77 million USD, up from 255.0 million USD in 2025, and to expand steadily toward 400.0 million USD by 2032. This translates to a forecast-period CAGR of 6.5 percent, a pace that signals durable demand but also rewards players who can read the fine print behind the headline numbers.
The report is designed as a decision-support instrument rather than a static market snapshot. It maps how historical inflection points between 2020 and 2025 set the stage for the current cycle, then translates those patterns into actionable scenarios for 2026 and beyond. Readers will find a disciplined breakdown of market architecture by region, type, and application, alongside a focused competitive profile of the organizations shaping pricing, capacity, and product differentiation. Equally important, the study embeds the operational realities that now govern margin outcomes: feedstock cost dynamics, compliance expenditures, and the strategic moves producers are already making to protect or expand their positions.
Why This Study Matters for 2026 Decision-Making
2026 is not a typical baseline year. Companies are operating in an environment where raw material volatility, environmental compliance, and regional capacity shifts are interacting at the same time. The specialty carbon black market reflects that convergence. Over the historical period, the sector moved from 180.0 million USD in 2020 to 255.0 million USD in 2025, a trajectory that underscores consistent expansion but also hides the uneven pace of growth across end-use sectors and geographies. The forward view shows continued uplift, with the market expected to reach 287.83 million USD in 2027, 311.24 million USD in 2028, and 335.4 million USD in 2029 before crossing toward 376.68 million USD in 2031 and 400.0 million USD in 2032.
For executives, the strategic question is not whether the market is growing, but where the growth is structurally concentrated and how to position for it. The study helps answer that by separating signal from noise. It shows how overall momentum is being shaped by a handful of high-value application areas and by regional demand centers that differ in both scale and maturity. It also highlights the competitive reality that market share is not evenly distributed: the top three players account for approximately 55.0 percent of the market, while the top five reach about 68.0 percent. That concentration has real implications for pricing power, contract negotiation, and supply security, especially when leading producers adjust their commercial terms or introduce surcharge mechanisms.
This is exactly why the report is framed around operational relevance. Rather than presenting isolated figures, it connects market size and growth to the decisions that matter in 2026: how to plan for feedstock uncertainty, which product families deserve closer evaluation, how regional demand centers compare in absolute scale, and where competitive intensity is likely to rise as new capacity and import-substitution dynamics take hold.
Market Architecture at a Glance
A clear view of market structure is essential for prioritizing resource allocation and risk management. The study organizes the landscape across three core dimensions, giving readers a structured way to interpret demand, supply, and segmentation without obscuring the differences that drive strategic advantage.
Regional Scale and Demand Patterns
The regional view places absolute market scale in context. Asia Pacific stands as the largest regional market at 96.05 million USD, followed by North America at 66.87 million USD, Europe at 46.51 million USD, Latin America at 30.43 million USD, and the Middle East and Africa at 15.14 million USD. These figures make the geographic hierarchy explicit while leaving room for the report's deeper discussion of growth rates, demand drivers, and local supply conditions. In practice, that means procurement and expansion planning can be anchored in relative market size while still accounting for the distinct regulatory, manufacturing, and logistics realities that differ from one region to another.
Product Families and Value Positioning
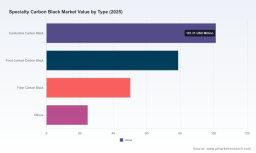
On the type side, conductive carbon black leads at 101.31 million USD, with food contact carbon black at 78.81 million USD, fiber carbon black at 50.18 million USD, and other specialty grades at 24.7 million USD. This structure matters because each family serves different performance requirements and end-market expectations. Conductive grades, for example, are tied to functionality in electronics, battery-related formulations, and advanced polymer applications, while food-contact and fiber-oriented grades carry their own regulatory and processing considerations. The report uses these categories to show where value is being created today and where product development is likely to open additional room for premium positioning.
Application Demand and Portfolio Implications
By application, the market is anchored by plastics at 95.27 million USD, printing inks at 69.51 million USD, paints and coatings at 60.04 million USD, and batteries at 30.18 million USD. These segments collectively illustrate how specialty carbon black has moved beyond traditional bulk uses into formulation-intensive areas where dispersion, conductivity, UV protection, pigmentation, and consistency are critical. The study examines each application cluster not as a simple revenue line, but as a set of performance requirements, substitution risks, and specification sensitivities that influence purchasing behavior and supplier selection. For teams evaluating expansion, reformulation, or dual-sourcing strategies, that application-level clarity is often the difference between a generic market thesis and an executable plan.
Competitive Landscape: Leaders, Moves, and Meaning
The competitive environment is defined by established global players, regional specialists, and emerging producers pursuing higher-value grades and import substitution. The report profiles the organizations that are most influential in shaping pricing, product breadth, and capacity strategy, with a focus on how their offerings map to the specialty carbon black segments that matter most to buyers.
Global Incumbents and Portfolio Breadth
Orion S.A., headquartered in Spring, Texas, is positioned as a global leader in specialty carbon black grades for paints, coatings, inks, toners, plastics, adhesives, polymers, batteries, and tires. With 15 production facilities and a stated emphasis on sustainable and circular solutions, Orion illustrates how scale can be paired with a sustainability narrative that increasingly matters to downstream customers. Cabot Corporation, based in Boston, Massachusetts, is described as the world's largest producer of specialty carbons, with its BLACK PEARLS, EMPEROR, REGAL, and MONARCH lines supporting UV protection, pigmentation, and conductivity across plastics, coatings, toners, and printing inks. Birla Carbon, headquartered in Mumbai, India, is presented as a leading manufacturer of sustainable carbon black additives, with Raven, Conductex, and Ultra brands targeting high-performance applications in paints, coatings, inks, plastics, adhesives, and tires.
Specialty Carbon Black Market
These profiles are not simply corporate summaries. They are used in the study to show how product naming, grade breadth, and application coverage influence customer choice in specification-driven markets. When buyers compare suppliers, they are often evaluating more than price; they are weighing consistency, technical support, regulatory readiness, and the ability to support reformulation or sustainability goals.
Regional Players and Emerging Capacity Strategies
The competitive picture also includes regionally anchored producers and newer entrants that are altering the market's center of gravity. Tokai Carbon Co., Ltd., based in Tokyo, produces ASTM blacks and specialty carbon blacks for tire, rubber goods, plastics, coatings, and inks, with recent Southeast Asia capacity expansion reinforcing its regional presence. PCBL Chemical Ltd., headquartered in Kochi, India, manufactures seven specialty carbon black grades and has moved to enhance capacity for high-margin grades in rubber and industrial applications. In China, Anhui Black Cat Material Science Co., Ltd. is noted as a leading supplier of specialty carbon black that is realizing import substitution in medium and high-value grades for the paint industry, while Shandong Huibaichuan New Materials Co., Ltd., based in Jinan, Shandong Province, produces pigment and conductive carbon black for coatings, inks, plastics, master batches, sealants, and other applications.
Together, these companies highlight a broader trend: competition is intensifying not only through capacity additions, but through grade specialization, regional proximity, and the pursuit of higher-value niches. The study translates these developments into a practical competitive map, helping readers understand where incumbency is strongest, where import substitution is advancing, and where new capacity may alter supply conditions over the forecast period.
Industry Dynamics Shaping Margin and Strategy in 2026
The market does not move in a vacuum. Several concurrent forces are reshaping cost structures, compliance burdens, and commercial behavior, and the report integrates them into a single operational lens rather than treating them as separate side notes.
Feedstock Pressure and Price Environment
Crude oil price volatility in 2026 has intensified feedstock pressure for specialty carbon black production, with coal tar and oil-based inputs rising sharply due to disruptions in the Strait of Hormuz and higher energy costs. This matters because feedstock economics sit at the center of margin stability, inventory planning, and pricing negotiation. The study examines how this pressure is propagating through production costs and how leading producers are responding, including through commercial mechanisms that transfer part of the volatility into contract terms.
Regulatory Tightening and Compliance Costs
On the regulatory front, stringent environmental regulations in the EU and US have imposed stricter air emission standards and workplace exposure rules on carbon black production, raising compliance costs for specialty grades. At the same time, stricter carbon taxes and emissions trading schemes in key markets are constraining traditional carbon black production methods that release particulate matter, NOx, and sulfur compounds. These forces do more than add cost; they influence which production routes remain competitive, how suppliers justify premium grades, and where sustainable or circular solutions gain commercial traction.
Recent Commercial and Strategic Moves
Recent developments make these dynamics concrete. In March 2026, Orion S.A. announced that it will raise prices and introduce a variable surcharge for specialty carbon black products, a move that directly reflects the feedstock and cost environment while signaling how incumbents are protecting margins. In April 2026, Birla Carbon showcased advanced sustainable carbon black solutions at Chinaplas 2026 for high-performance applications in plastics, electronics, cables, and fibers, underlining the growing linkage between sustainability and performance claims in demanding end markets. In May 2026, Orion S.A. launched circular carbon black production in China, and also announced plans to showcase award-winning bio-circular carbon black plus high-jet grades for automotive coatings at the 2026 American Coatings Show. These events are not isolated news items; they illustrate how product innovation, circular production, and targeted application messaging are being used to navigate a more complex operating environment.
What the Report Delivers: A Practical Toolkit for Strategy Teams
The study is organized to support real decision cycles, not just high-level observation. It blends market sizing, segmentation, competitive profiling, and industry dynamics into a single framework that can be used for sourcing strategy, product planning, investment screening, and risk assessment.
Carbon Black Market
- Historical trajectory and forecast structure covering 2020 through 2032, anchored in consistent market sizing and a 6.5 percent forecast-period CAGR
- Clear segmentation views by region, type, and application, with absolute scale provided to support prioritization and comparison
- Competitive profiles that connect product offerings, production footprints, and strategic positioning to the segments most relevant to specialty carbon black buyers
- Integration of feedstock volatility, regulatory pressure, and recent corporate moves into a working view of margin and supply risk
- Focused analysis of concentration dynamics, with top-three and top-five share context that informs supplier dependence and negotiation strategy
- Practical orientation toward 2026 decision-making, including how to interpret price actions, capacity shifts, and sustainability-driven product launches
In short, the report is built to help teams move from awareness to action. It gives readers a defensible basis for evaluating where demand is strongest, which grades and applications warrant closer attention, how competitors are shaping the commercial environment, and what operational pressures are likely to influence cost and availability in the near term.
How to Use This Intelligence
For procurement and supply chain leaders, the study offers a structured way to assess supplier options, anticipate pricing pressure, and understand where concentration and recent price actions may affect contract strategy. For product and formulation teams, it provides context on how application requirements and regulatory trends are influencing grade selection and substitution risk. For corporate strategy and investment functions, it frames the market in terms of structural growth, competitive positioning, and the regions and product families that are likely to define the next phase of expansion.
The full study goes further than the overview presented here. It contains the deeper segmentation detail, company-level analysis, and scenario-based interpretation needed to turn market visibility into concrete decisions. For teams that need the complete picture—region-by-region scale, application-level demand context, type-level value positioning, and the competitive moves that are actively reshaping the market—the source report is the appropriate next step.
The specialty carbon black market is expanding, but the value of that growth will depend on how well organizations can read its structure, anticipate its pressures, and respond to the moves of a concentrated and increasingly adaptive competitive set. This report is designed to give decision-makers exactly that vantage point for 2026 and the years that follow.
For detailed analysis of this topic, please visit the official page: Specialty Carbon Black Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


