



PW Consulting: Fused Magnesia Sales Hit $1.89B in 2025, Projected to Grow at 5.6% CAGR Through 2032

Strategic Intelligence for the Decade Ahead: Why the 2026 Fused Magnesia Outlook Demands Immediate Executive Attention
The global fused magnesia market is entering a phase of structural redefinition. As industries grapple with tightening supply chains, evolving regulatory frameworks, and shifting demand vectors, the need for precise, forward-looking intelligence has never been more critical. Our newly released 2026 Fused Magnesia Market Research Report delivers exactly that: a comprehensive, data-grounded, and strategically actionable analysis designed to equip corporate leaders, procurement directors, and market strategists with the clarity required to navigate the forecast period from 2026 through 2032.
This executive preview outlines the foundational insights embedded in our study, demonstrates how historical trajectories and forward-looking indicators converge to shape near-term decision-making, and reveals the analytical architecture that will guide your organization through an increasingly complex market landscape. We deliberately reserve granular segmentation forecasts and proprietary modeling outputs for the full report, because strategic success depends not only on knowing where the market is heading, but on understanding the underlying mechanics that will determine competitive advantage.
The Macro Trajectory: Historical Resilience Meets Forecasted Expansion
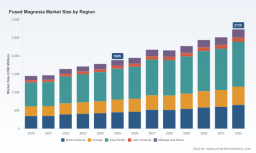
Over the past half-decade, the global fused magnesia sector has demonstrated remarkable resilience, outpacing several downstream commodity benchmarks while absorbing geopolitical friction, energy price volatility, and downstream capacity realignments. Historical data from 2020 through 2025 captures a market that steadily rebuilt momentum after initial pandemic-era disruptions, translating structural demand from core industrial applications into consistent revenue growth. By the close of the base year, the market reached an estimated valuation of approximately 1.885 billion USD, reflecting a compound trajectory that underscores the material's entrenched role across heavy industry, advanced ceramics, and specialized refractory systems.
Looking forward, our analysis projects that this expansion will continue its upward cadence, with the market advancing toward a valuation of roughly 2.730 billion USD by the terminal year of our forecast window. Driving this progression is a forecasted compound annual growth rate of 5.6 percent, a figure that encapsulates both baseline industrial demand and the incremental pull from capacity optimization initiatives, high-performance material substitution, and regional supply chain restructuring. The growth curve is neither linear nor uniform. It is shaped by the interplay of raw material consolidation, trade policy recalibration, and the steady migration toward higher-purity specifications in applications that demand superior thermal stability and chemical inertness.
For decision-makers, the implication is clear: the market is large enough to attract sustained capital allocation, yet dynamic enough to reward organizations that anticipate structural inflection points rather than react to them after they materialize.
Structural Drivers and Market Concentration Dynamics
The fused magnesia ecosystem is characterized by a concentrated yet increasingly competitive landscape. Our assessment indicates that the top three participants command approximately 52 percent of total market share, while the top five collectively represent around 68 percent. This concentration level signals an industry where scale, integrated supply chains, and technical differentiation remain decisive competitive moats. Yet it also suggests that mid-tier producers, regional specialists, and vertically aligned operators are actively carving out defensible positions through application-specific grading, logistics optimization, and strategic partnerships with downstream users.
Several macroeconomic and industrial forces are reinforcing demand durability. The steel and iron sector continues to anchor a substantial portion of consumption, driven by sustained production requirements, refractory lining upgrades, and the broader push toward extended campaign life in high-temperature processing environments. At the same time, emerging applications across advanced ceramics and glass manufacturing are reshaping specification requirements, with end-users increasingly prioritizing consistency, purity thresholds, and customized particle profiles over commoditized bulk supply. Construction-related utilization, though comparatively smaller in absolute terms, continues to provide baseline demand stability as infrastructure programs and building material formulations evolve in response to performance and regulatory considerations.
The market is therefore not merely expanding; it is bifurcating. High-purity segments are attracting premium valuation dynamics and long-term supply commitments, while medium-purity grades remain essential for cost-sensitive bulk applications. Understanding how these layers interact, where substitution risks emerge, and how pricing architecture responds to energy and feedstock variability is central to any credible strategic forecast. Our report isolates those dynamics and maps them against actionable procurement and capacity-planning scenarios.
Policy, Trade, and Supply-Side Realignment: A Landscape in Motion
No contemporary market assessment can be complete without grappling with the regulatory and trade environment shaping input costs, market access, and competitive positioning. Recent developments underscore that fused magnesia is no longer a purely commercial commodity; it is also a product of policy intervention, trade defense measures, and localized consolidation mandates.
One of the most consequential supply-side trends involves the ongoing consolidation of magnesite mining operations in key producing regions. Between 2020 and 2024, the number of active magnesite-mining enterprises in Liaoning declined from 114 to 63, with further consolidation anticipated to bring the total to approximately 56 operators by the end of 2025. This trajectory reflects a deliberate move toward operational scale, environmental compliance, and output coordination. In parallel, provincial guidance in China has emphasized sector-wide output consolidation, signaling that future supply will be increasingly determined by a smaller number of coordinated producers with enhanced control over feedstock availability and pricing.
Trade policy is equally transformative. The U.S. Department of Commerce initiated an antidumping investigation on imported dead burnt magnesite, while the U.S. International Trade Commission voted unanimously to continue the existing antidumping duty order on fused magnesia originating from China. Meanwhile, the Magnesite Association of India filed a petition alleging dumping of dead burnt magnesite from the People's Republic of China, highlighting how trade remedies are becoming a recurring feature of the global refractory raw material landscape. These actions are not isolated; they form a pattern that will influence sourcing strategies, regional cost structures, and the geography of competitive advantage.
Organizations that treat trade measures as peripheral risk factors will likely encounter costly supply disruptions or margin erosion. Those that integrate policy trajectories into procurement diversification, inventory architecture, and regional capacity planning will be better positioned to absorb shocks and capture relative pricing power.
Competitive Architecture: Who Shapes the Market and How
The competitive environment surrounding fused magnesia is defined by a blend of globally integrated incumbents, regionally anchored specialists, and application-focused producers. Our report examines the strategic postures, operational footprints, and positioning strategies of key market participants, including:
Fused Magnesia Market
- RHI Magnesita , headquartered in Vienna, Austria, which operates as a global leader in high-grade refractory products. With fused magnesia production and system-level solutions spanning more than 35 sites, the company serves steel, cement, glass, and non-ferrous metals industries. Its scale and integrated product portfolio make it a benchmark for downstream alignment and technical service differentiation.
- Grecian Magnesite S.A. , based in Athens, Greece, which specializes in magnesite products and grades including fused magnesia for refractories, electrical applications, and industrial uses. Its positioning reflects a focus on specialty-grade consistency and export-oriented distribution networks.
- Kumas Manyezit Sanayi A.Ş. , operating from Kütahya, Turkey, which manufactures refractory materials including fused magnesia and magnesite for industrial applications. Its regional manufacturing footprint provides supply agility and proximity advantages for European and nearby downstream markets.
- Baymag Inc. , headquartered in Calgary, Alberta, Canada, which acts as an integrated producer of magnesium oxide, including fused magnesia derived from its Canadian magnesite deposit. This vertical integration from deposit to processed output supports supply reliability and specification control for refractory and industrial uses.
- Premier Magnesia, LLC , located in Gabbs, Nevada, United States, which is recognized as a global leader in magnesia-based products with natural magnesia supply and processing capabilities for industrial applications. Its North American footprint and feedstock access provide strategic relevance in the context of trade flows and domestic sourcing initiatives.
- Nedmag B.V. , based in the Netherlands, which produces high-purity magnesium oxide products including dead-burned and fused magnesia for refractories and specialty uses. Its emphasis on purity and specialty-grade output aligns with high-value application requirements.
- Martin Marietta Magnesia Specialties , operating in the United States, which supplies high-purity magnesium oxide products including specialty grades for refractory and industrial applications. Its portfolio reflects a focus on performance-grade differentiation and downstream technical support.
- Niche Fused Magnesia Ltd , based in Hull, United Kingdom, which supplies fused magnesia for industrial and refractory applications. As a more specialized participant, its role illustrates how targeted market niches can sustain viable competitive positions without relying solely on scale.
Beyond company profiles, our analysis evaluates the strategic logic underpinning each player's positioning: where integration confers resilience, where geographic proximity drives logistics advantage, and where technical service capabilities create switching costs for end-users. The report also examines how these participants are likely to respond to consolidation pressures, trade remedy developments, and evolving purity requirements. In a market where the top five players already account for a substantial share of revenue, competitive differentiation increasingly depends on supply security, application engineering, and the ability to align product specifications with downstream process optimization.
What the Full Report Delivers: Operational Intelligence, Not Just Forecasts
Market data alone does not generate competitive advantage. The value of a research study lies in how effectively it translates complex signals into executable strategy. Our 2026 Fused Magnesia Market Report is built around that principle. It goes beyond headline growth figures to provide a structured toolkit for decision-makers across procurement, production planning, investment evaluation, and market entry analysis.
The report is organized to support multiple strategic use cases. It maps the historical performance of the market from 2020 through the 2025 base year, establishing a credible baseline against which forecast assumptions are tested. It then extends the analysis through 2032, incorporating segment-level demand patterns, purity-grade evolution, application-driven specification shifts, and regional supply chain considerations. Importantly, it connects these elements to operational implications rather than leaving them as abstract projections.
Readers will find detailed coverage of:
- The structural composition of demand across major application categories, including the relative weight of steel and iron processing, ceramics and glass manufacturing, and construction-related utilization, along with the qualitative drivers that determine how these shares evolve over time.
- How purity segmentation shapes pricing behavior, customer loyalty, and capacity allocation, with attention to the diverging requirements of high-purity and medium-purity value chains.
- Regional demand architecture and the strategic significance of geographic concentration, logistics corridors, and cross-border trade flows, analyzed in a way that helps organizations evaluate sourcing options without relying on static rankings.
- The competitive posture of leading producers and the operational levers that differentiate them, including integration depth, specialty-grade capabilities, and downstream application support.
- Regulatory and trade developments that alter cost structures and market access, with scenario-based considerations for procurement and supply continuity planning.
- Material consolidation trends and their implications for raw material availability, pricing volatility, and long-term contract strategy.
- Forward-looking indicators that signal where demand intensity is likely to intensify, where substitution pressures may emerge, and where investment or capacity decisions carry the highest strategic payoff.
By aligning quantitative trajectory analysis with qualitative industry mechanics, the report is designed to be referenced repeatedly throughout planning cycles. It supports budgeting precision, supplier evaluation, risk mitigation, and competitive positioning without requiring readers to reconstruct the underlying logic from disparate sources.
White Fused Alumina Market
Why This Research Matters for 2026 Decision-Making
The 2026 to 2032 window is not simply a continuation of past trends. It is a period in which the fused magnesia market will be shaped by simultaneous forces: sustained industrial demand, increasing emphasis on material performance, policy-driven consolidation, and trade measures that redraw sourcing maps. Organizations that treat these forces as background noise will likely find themselves reacting late, paying premium prices, or committing to supply arrangements that no longer match market realities.
Conversely, firms that ground their strategies in a rigorous, scenario-aware analysis will be better equipped to negotiate long-term contracts from a position of understanding, diversify sourcing without sacrificing reliability, and identify where purity upgrades or application-specific support can command favorable commercial terms. The strategic question is no longer whether the market will grow; it is how each organization will position itself to capture value as growth unfolds unevenly across segments, regions, and competitive tiers.
Our full report provides the depth, structure, and actionable framing required to answer that question with confidence. It is intended for leaders who need a single, coherent reference point that integrates market sizing, competitive assessment, regulatory context, and forward-looking demand logic into one analytical platform.
Access the Complete Intelligence
This preview has outlined the strategic rationale, high-level market trajectory, competitive architecture, and policy environment that form the foundation of our analysis. It has also made clear that the market's future is not defined by a single metric, but by the interaction of purity requirements, application dynamics, consolidation patterns, and trade policy. To move from directional understanding to decision-ready intelligence, however, organizations need the full scope of segmentation logic, scenario detail, and competitive evaluation that only the complete study can provide.
We invite executives, strategy teams, and procurement leaders to access the full 2026 Fused Magnesia Market Report for comprehensive data, detailed forecasting architecture, and the operational insights required to translate market momentum into competitive advantage. In a sector where timing, specification alignment, and supply resilience determine outcomes, the right intelligence is not an accessory to strategy. It is the foundation of it.
For detailed analysis of this topic, please visit the official page: Fused Magnesia Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


