



Refrigerator Water Filters Market to Reach $3.9B by 2032, 5.9% CAGR; PW Consulting Report

Navigating the Next Era of Refrigerator Water Filters: Strategic Intelligence for 2026 and Beyond
The global appliance ecosystem is undergoing a quiet but decisive transformation. As consumers place greater emphasis on water quality, health consciousness, and appliance longevity, the refrigerator water filter segment has evolved from a routine replacement component into a strategic battleground defined by certification compliance, subscription-based service models, and intensifying competition between original equipment manufacturers and certified aftermarket players. Our newly released market research provides a comprehensive, data-grounded assessment of this landscape, offering enterprise leaders a clear framework for capital allocation, product positioning, and long-term competitive strategy.
This introduction outlines the core strategic value of the study, highlights the operational and regulatory forces currently reshaping the market, and previews the analytical depth available in the full report. For decision-makers operating in 2026, understanding where the market has been and how it is structurally positioned to evolve is no longer optional. It is a prerequisite for sustainable growth.
Water Filters Market
Market Evolution and Strategic Context
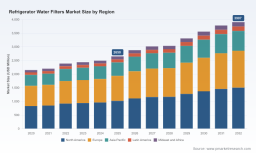
Over the past half-decade, the refrigerator water filter market has demonstrated consistent, structural expansion. Drawing on historical revenue tracking and forward-looking projections, our analysis captures a market that has steadily advanced from approximately $2.15 billion in 2020 to an estimated $2.65 billion in 2025, with continued upward momentum projected through the end of the forecast period. The trajectory reflects more than cyclical demand. It signals a durable shift in consumer expectations around integrated appliance functionality, coupled with increasingly stringent quality and safety benchmarks that collectively reinforce replacement frequency and brand loyalty.
The forecasted period extends through the early 2030s, with an estimated compound annual growth rate of 5.9 percent. This rate suggests a mature but still expanding segment, where growth will be driven less by sudden volume surges and more by sustained replacement cycles, geographic penetration, technology adoption, and service-oriented business models. For executives, this profile carries important implications. It indicates that competitive advantage will increasingly depend on supply chain efficiency, certification readiness, channel strategy, and the ability to convert transactional purchases into recurring revenue streams. The full report maps these dynamics in granular detail, but the overarching message is clear: the market is consolidating around compliance-driven quality and service continuity, and companies that treat filters as commoditized accessories will find themselves outpaced by those who embed filtration into broader product ecosystems and customer engagement strategies.
Regulatory Framework and Certification as Competitive Moats
One of the most consequential forces shaping the refrigerator water filter landscape is the tightening regulatory and certification environment. Industry guidance has increasingly clarified that listings on major retail platforms must demonstrate compliance with NSF/ANSI 42 for material safety, structural integrity, and performance reduction claims. Where manufacturers make additional health-effect or emerging-contaminant claims, NSF/ANSI 53 and NSF/ANSI 401 become relevant. This is not merely a technical footnote. It is a commercial gatekeeper.
Independent testing and certification by accredited organizations remain central to market access and consumer trust. Filters that fail to meet structural integrity or contaminant reduction requirements face heightened risk of discontinuation or recall, a reality that makes verification and documentation essential components of product lifecycle management. In practical terms, certification has become a brand asset and a barrier to entry. Companies that maintain rigorous compliance can command stronger shelf presence, retail partnership confidence, and customer retention, while those that treat certification as an afterthought expose themselves to reputational and operational risk.
At the same time, compliance has introduced real cost pressure. Replacement filters have experienced a notable increase in material and labor costs since 2020, driven in part by the need to meet evolving NSF standards for lead reduction and emerging contaminants. This cost trajectory shapes pricing architecture, margin planning, and the economics of aftermarket substitution. The complete study evaluates how manufacturers and distributors are navigating these pressures through product engineering, scale efficiencies, and value-tier positioning, but the strategic takeaway is already evident: regulatory compliance is redefining the cost floor of the category, and the winners will be those who integrate compliance into design and procurement strategies rather than treating it as an end-of-line checklist.
Competitive Landscape: OEMs, Aftermarket Innovators, and Retail Displacement
The competitive dynamics of this market are defined by a structured interplay between appliance OEMs, certified aftermarket specialists, and retail ecosystems that are beginning to mediate the replacement experience. Several large players anchor the segment through brand-integrated filtration programs, while a growing set of aftermarket providers compete on compatibility, certification, and pricing. The result is a market with meaningful concentration but still enough fragmentation to reward companies that execute sharply on channel strategy and customer retention.
Whirlpool Corporation and its EveryDrop brand illustrate a tightly integrated OEM approach. By manufacturing and distributing genuine refrigerator water filters designed for Whirlpool, KitchenAid, and related appliances, the company leverages installed base compatibility and ongoing replacement programs, including subscription-style replenishment. This model aligns filter sales with broader appliance ownership and builds predictable revenue through repeat purchases. LG Electronics follows a similar logic with its certified filter portfolio, emphasizing lead reduction standards and maintenance programs that include scheduled filter replacement. Samsung Electronics complements this competitive set with integrated filtration solutions engineered for water and ice systems, where model-specific compatibility and certification requirements reinforce OEM lock-in. GE Appliances rounds out the OEM perspective with genuine filters designed to reduce chlorine, lead, PFOA/PFOS, and other contaminants across its refrigerator models, reinforcing the value of appliance-specific ecosystems.
Against this OEM foundation, aftermarket participants have carved out a credible presence by offering NSF-certified compatible replacements. Ecolife Technologies, Inc., operating through its Waterdrop brand, distributes aftermarket filters that align with major OEM platforms including Samsung, LG, Whirlpool, and GE. Aqua Crest and SpiroPure similarly focus on certified replacement options designed for standard OEM housings and widely used refrigerator models. These companies illustrate a market dynamic in which compatibility, certification clarity, and distribution reach can offset the absence of native appliance manufacturing. They also highlight an important strategic question for incumbents: how to defend installed-base loyalty while responding to the pragmatic demand for cost-effective, certified alternatives.
Recent industry developments underscore how quickly the channel itself is evolving. In early 2026, Lowe's Companies, Inc. launched a HomeCare+ subscription service that includes annual refrigerator water filter replacement as part of associate-powered in-home maintenance for MyLowe's Rewards members. This move signals a broader push toward service-led retention models, where filter replacement becomes part of a broader home-care experience rather than an isolated point purchase. Around the same time, Waterdrop expanded its aftermarket refrigerator water filter catalog with additional SKUs targeting Samsung, LG, Whirlpool, and GE models, accompanied by updated NSF listings. These initiatives reflect two parallel trends: the growing importance of subscription and maintenance programs, and the continued expansion of certified aftermarket choice within retail channels.
What the Full Study Delivers for 2026 Decision-Making
The complete market research is designed to translate industry complexity into operational clarity. Rather than stopping at headline market size and growth rate, the study builds a practical decision framework that leaders can use to evaluate risk, prioritize investment, and refine go-to-market strategy. The analysis is structured to support cross-functional teams, from product development and procurement to sales, marketing, and investor communications.
At the core of the report is a detailed assessment of market size evolution and forward projections, anchored in historical performance and a clearly defined forecast horizon. This provides a reliable baseline for scenario planning, demand forecasting, and capacity alignment. The study then examines the structural composition of the market across product architecture and end-use context, helping readers understand where revenue is concentrated, how replacement behavior varies across environments, and which segments are most sensitive to certification, pricing, and compatibility considerations. These breakdowns are intentionally developed as strategic lenses rather than static snapshots, enabling readers to identify where competitive pressure is intensifying and where differentiation remains achievable.
The competitive portion of the research profiles leading participants and maps the forces that shape their positioning. By integrating company profiles, brand strategy signals, and recent developments, the report provides context for interpreting share dynamics, channel influence, and the strategic implications of OEM-versus-aftermarket competition. It also evaluates how service models, retail partnerships, and subscription-oriented offerings are changing the economics of replacement demand. This is particularly valuable for organizations considering whether to enter adjacent distribution channels, launch replenishment programs, or reposition their product tiers in response to cost and compliance shifts.
Another major strength of the study is its treatment of the regulatory and certification environment as a market driver rather than a compliance footnote. The report connects certification requirements to commercial outcomes, including retail eligibility, consumer trust, product lifecycle risk, and cost structure. It also addresses the practical reality that certification failures can trigger discontinuation or recall risk, reinforcing the importance of verification, documentation, and quality assurance in product planning. For companies operating in or entering this market, these insights support more resilient product architectures and more credible market-facing claims.
Finally, the study integrates material and cost considerations into the broader market narrative. By examining how compliance demands and input-cost trends have influenced the economics of replacement filters, the report offers a basis for pricing strategy, margin management, and value proposition design. This is essential for organizations trying to balance affordability with certification credibility, especially as aftermarket competition expands and OEM loyalty programs become more sophisticated.
Strategic Implications for Market Participants
For executives evaluating the refrigerator water filter market in 2026, several strategic priorities emerge from the landscape described in this study. First, certification readiness is a strategic differentiator, not just a technical requirement. Companies should treat compliance as a core element of product design, supplier selection, and retail positioning, because it directly affects distribution access, consumer confidence, and risk exposure.
Second, the shift toward service-connected replacement models is creating new opportunities for recurring revenue and customer lock-in. Subscription programs, maintenance integrations, and retail-led home care offerings are redefining how filter replacements are purchased and valued. Organizations that can align filtration with broader appliance ownership experiences or home maintenance relationships will be better positioned to capture lifetime value from installed bases.
Third, aftermarket competition is maturing, and compatibility with certified standards is increasingly central to its credibility. This creates both a challenge and an opportunity for OEMs and distributors. On one side, certified alternatives can pressure margin and loyalty; on the other, they validate the category's importance and can expand total demand by lowering barriers to replacement. The strategic response depends on whether a company competes through ecosystem integration, cost efficiency, channel strength, or a combination of all three.
Fourth, cost pressures tied to compliance and material inputs warrant ongoing attention in product planning and pricing architecture. As the market continues to expand, the ability to manage these economics without compromising certification credibility will separate resilient operators from those forced into reactive pricing moves.
Closing the Intelligence Gap
The refrigerator water filter market is no longer defined solely by appliance cycles and replacement schedules. It is increasingly shaped by certification standards, subscription-enabled retention, retail service models, and the growing credibility of aftermarket alternatives. For leaders operating in this environment, strategic clarity depends on more than directional trends. It requires a detailed understanding of how market size, segmentation, competitive positioning, and regulatory dynamics interact over time.
This research study was built to provide that understanding. It offers a comprehensive view of historical performance, projected growth, competitive structure, and the operational forces that will define the next several years of category development. The full report expands on every dimension introduced here with greater analytical depth, enabling teams to translate market intelligence into tangible decisions around product strategy, channel investment, compliance planning, and customer retention. For organizations preparing for 2026 and the forecast window ahead, the opportunity is to move from awareness to action with the kind of structured intelligence that supports durable competitive advantage.
Refrigerator Water Filters Market
For detailed analysis of this topic, please visit the official page: Refrigerator Water Filters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


