



PW Consulting: Wall Protection Market Hits $1.17B in 2025, Projects 5.5% CAGR to 2032

The Wall Protection Market 2026 Strategic Outlook: Navigating Growth Amid Regulatory Shifts and Manufacturing Consolidation
The global wall protection market has transitioned from a passive infrastructure maintenance category to a strategically critical component of facility design and risk management. As organizations prepare their operational roadmaps for 2026, understanding the underlying forces shaping this sector is no longer optional. Our latest market research delivery provides executive teams with a structured, forward-looking intelligence framework designed specifically to support capital allocation, supply chain planning, and competitive positioning across the forecast horizon.
Drawing on a rigorous historical baseline spanning 2020 through 2025, the analysis maps an established trajectory of consistent expansion. The market closed the baseline year with total industry revenue of approximately USD 1,170 million, reflecting steady demand accumulation across commercial, institutional, and industrial environments. Forward-looking projections indicate that this momentum will sustain through the 2026 to 2032 outlook period, anchored by a forecast compound annual growth rate of 5.5 percent. By the close of the modeling window, industry revenues are positioned to approach USD 1.71 billion. This expansion trajectory is not merely a function of incremental construction activity. It reflects deeper structural shifts in safety compliance, aging infrastructure renewal cycles, and evolving material specifications across high-traffic environments. The strategic implication is clear: wall protection is increasingly evaluated through the lens of lifecycle performance, regulatory alignment, and total cost of ownership rather than initial procurement price.
Market Dynamics: The Convergence of Specification Pressure and Material Economics
Several interlocking dynamics are reshaping procurement behavior and manufacturer strategy as the 2026 planning cycle unfolds. At the regulatory level, institutional buyers are operating within increasingly precise technical specifications. The U.S. Department of Defense UFGS 10 26 00 standard continues to establish a high-performance benchmark for wall guards, crash rails, and bed locators, requiring minimum impact resistance, defined fire resistance ratings, integral coloration, and explicit chemical, stain, fungal, and bacterial resistance. These requirements are not limited to defense-adjacent projects. They are steadily influencing municipal procurement guidelines, healthcare facility standards, and commercial building specifications across multiple jurisdictions. Healthcare patient safety frameworks have similarly tightened expectations, with recent guidance mandating tested handrails, wall protection assemblies, and toilet accessories in both medium-risk and low-risk care zones. Compliance is no longer treated as a checkbox exercise. It is becoming a baseline qualification for market access.
Parallel to specification tightening, raw material price volatility remains a persistent operational pressure point for manufacturers. Fluctuations in polymer feedstocks, metal alloys, and specialty coatings directly affect production costs and margin stability. Companies that have embedded flexible sourcing strategies, forward procurement agreements, and material substitution capabilities are better positioned to absorb input cost swings without eroding competitive pricing. Conversely, producers relying on rigid supply chains face mounting challenges in maintaining consistent delivery timelines and price predictability. For procurement and facilities leadership, this creates a dual imperative: evaluate supplier resilience alongside product performance, and structure contracts with appropriate escalation mechanisms to preserve long-term project economics.
Segment Architecture: How Product, Application, and Regional Factors Shape Demand
The market’s structure reveals a highly differentiated demand landscape, where product categories serve distinct functional priorities across end-use environments. Among core product families, corner guard solutions represent the largest revenue share, reflecting their universal deployment in high-impact contact zones across institutional, commercial, and healthcare settings. Wall guard assemblies and handrail systems form the next tier of demand concentration, each addressing specific safety and accessibility requirements that vary significantly by facility type and regional building code expectations. Additional product lines, including chair rail profiles and decorative or functional wall covering systems, capture meaningful utilization in specialized applications where aesthetics, impact mitigation, and ease of maintenance must be balanced simultaneously.
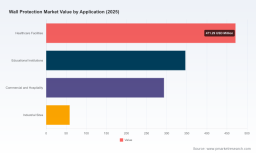
Application-side demand is distributed across several high-intake environments, with healthcare facilities and educational institutions consistently ranking among the most intensive users. These sectors share overlapping specifications related to durability, hygiene, and occupant safety, yet their procurement cycles, budgetary constraints, and renovation cadences differ in ways that materially affect purchasing velocity. Commercial and hospitality environments contribute a substantial and sustained demand stream driven by brand presentation standards, guest safety expectations, and high-traffic wear patterns. Industrial sites, while smaller in absolute volume, present distinct performance requirements where heavy-duty impact resistance and chemical exposure tolerance dictate material selection.
Geographically, the market continues to reflect mature demand centers alongside expanding adoption in emerging infrastructure corridors. North American and European procurement ecosystems remain deeply integrated with established specification standards, certified product listings, and long-standing supplier relationships. In contrast, Asia Pacific and Latin American markets exhibit different growth drivers tied to urbanization, public facility modernization programs, and evolving institutional procurement frameworks. Each regional context requires a tailored commercial approach that accounts for local compliance expectations, installation service availability, and sensitivity to total installed cost versus unit pricing.
Worldwide Wall Cladding Market
Because exact regional revenue splits, product family breakdowns, and application-level valuations are mapped in detail within the full report, we focus here on the structural relationships that matter for strategy. The critical insight for 2026 planning is that pricing power, channel access, and specification wins increasingly depend on demonstrating performance differentiation rather than competing solely on availability or initial cost. Buyers are evaluating vendors on documented compliance records, installation efficiency, replacement cycle predictability, and environmental product declarations that align with internal sustainability targets.
Competitive Landscape: Consolidation, Certification Leadership, and Specialized Product Positioning
Market concentration provides an additional lens for understanding competitive behavior and customer decision-making. The sector is anchored by a relatively consolidated group of established manufacturers, with the top three players collectively accounting for approximately 72 percent of total industry revenue, while the top five extend that share to around 85 percent. This concentration pattern reflects the strategic advantages held by companies with broad specification libraries, diversified product portfolios, and mature distribution networks. It also underscores the importance of channel relationships and technical specification support as primary competitive differentiators.
Leading participants have built their positions around distinct capability sets that align with high-demand application segments. Inpro Corporation operates as a prominent U.S.-based provider with a broad portfolio spanning door and wall protection, corner guards, handrails, crash rails, and full wall guard systems tailored for commercial, healthcare, and education environments. Koroseal Interior Products maintains a focused commercial wall protection line that includes corner guards, protective wallcovering materials, Korogard sheets, Flex Decorative Wall Protection, and Fusion Wall Protection, positioning the company across both functional protection and aesthetic integration use cases. SPM Professionnels, headquartered in France, serves as a specialist in wall protections and handrails for healthcare, education, hospitality, industry, and retail, offering PVC panels, plates, bumpers, and recently introduced Fin'Line profile systems alongside its DECOCHOC bestseller. Acrovyn contributes a recognized wall protection line featuring corner guards, handrails, crash rails, wall and door protection products, and Rubstrips supported by NSF-certified environmental product declarations. Pawling Systems emphasizes heavy-duty wall protection systems for commercial environments, utilizing rubber and stainless steel constructions across wall guards, corner guards, crash rails, and bed head protection applications. Protek Systems and Durable Corporation both maintain strong positions in metal and extruded guard solutions, with Protek focused on stainless steel and metal systems across guards, corner guards, handrails, crash rails, and door and frame protection, while Durable targets commercial and industrial settings including loading docks through extruded wall guards and rubber corner guards. Wallprotex completes the competitive field with a broad offering of bumper guards, corner guards, wall guards, wall sheets, and handrails.
Recent industry activity highlights how certification validation and product refreshes are being used to reinforce market positions. In December 2025, NSF Product and Service Listings confirmed the ongoing validity of environmental product declarations for multiple Acrovyn wall protection products, including Rubstrips, wall covering sheets, wall panels, and BG crash rails, with coverage extending through December 2030. During the same period, an Inpro Corporation coverage gap report verified core wall protection and door protection listings valid into January 2026. In July 2025, SPM Professionnels released a new e-catalogue and introduced the Fin'Line elegant profile to enhance panel applications for wall protection deployments. These developments matter because documented environmental compliance, specification continuity, and catalog modernization directly influence procurement confidence, especially in healthcare and public-sector environments where auditability and lifecycle documentation are increasingly scrutinized.
Report Coverage: What the Full Intelligence Package Delivers
This market research is structured to support practical decision-making rather than abstract market description. The complete study provides a detailed segmentation architecture covering product types, application environments, and regional markets, allowing teams to isolate the demand drivers most relevant to their operating context. Historical performance data from 2020 through 2025 establishes a reliable baseline for validating internal forecasts, while the 2026 through 2032 projection window offers forward estimates calibrated to current specification trends, renovation cycles, and procurement conditions.
Competitive analysis within the report examines company positioning across product capability, end-use alignment, certification status, and market concentration dynamics. It also evaluates how recent developments, including environmental product declaration continuity and new profile introductions, are shaping supplier selection criteria. Beyond competitive mapping, the report addresses the regulatory and materials environment that frames purchasing behavior, including specification benchmarks, patient safety expectations, and raw material cost influences on production economics. Procurement strategy, channel dynamics, installation service requirements, and total cost of ownership considerations are assessed to help organizations identify where specification leadership, supply resilience, or value engineering can create measurable advantage.
For strategy, product, and procurement teams, the study is designed to answer questions that generic market summaries cannot. Which application environments are expanding most rapidly as a function of compliance-driven renovation rather than new construction? Where are material specifications trending toward monolithic impact-resistant systems versus modular replaceable components? Which certification and environmental documentation requirements are most likely to influence bid eligibility over the forecast window? How should organizations balance portfolio breadth against specialized performance credibility when positioning for healthcare, education, hospitality, or industrial buyers? These are the kinds of operational questions the full analysis is built to address.
Strategic Implications for 2026 Decision-Making
As organizations move into the 2026 planning cycle, the wall protection market presents a clear set of strategic priorities. First, specification alignment is becoming a prerequisite for volume capture. Vendors and buyers alike must treat compliance documentation, impact testing, fire ratings, and environmental product declarations as core commercial assets rather than supplementary credentials. Second, total cost of ownership frameworks should replace narrow unit-price comparisons. In high-traffic healthcare and educational environments, replacement labor, downtime, cleaning protocols, and expected service life can materially alter the economic case for different product systems. Third, supply chain resilience deserves elevated attention given ongoing raw material price sensitivity and the concentration of leading manufacturers. Diversifying qualified suppliers, understanding regional installation capabilities, and building flexibility into procurement terms can protect project timelines and margin expectations.
Finally, the competitive environment rewards clarity of positioning. With a concentrated market structure dominated by a small group of broad-line providers and complemented by specialized players serving heavy-duty, aesthetic, or hygiene-critical applications, buyers benefit from mapping supplier capabilities directly to their facility risk profiles. Suppliers, in turn, are increasingly differentiating through documented environmental performance, modular design efficiency, and application-specific specification support.
Wall Protection Market
The complete market intelligence package expands every dimension discussed here into a directly actionable research framework, with granular segmentation, forward forecasts, competitive profiling, and regulatory and materials context mapped for immediate integration into capital planning, sourcing strategy, and product portfolio decisions. For teams seeking a precise, evidence-based foundation for 2026 and beyond, the full report provides the detailed breakdowns, scenario-ready projections, and competitive intelligence necessary to move from awareness to execution.
For detailed analysis of this topic, please visit the official page: Wall Protection Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


