



PW Consulting: Synthetic Fibre Rope Market to Hit $2,610M by 2032, Driven by 6.5% CAGR

Strategic Navigation in a High-Growth Synthetic Fibre Rope Market: A 2026 Decision-Maker's Brief
The synthetic fibre rope sector stands at a critical inflection point. As global industrial operations demand higher performance, greater durability, and increasingly sustainable load-bearing solutions, the market has evolved from a commodity-adjacent category into a technology-driven ecosystem. Our recently published market research on the Synthetic Fibre Rope Market delivers a comprehensive, forward-looking intelligence framework designed specifically for executive teams planning capital allocation, supply chain restructuring, and competitive positioning across the 2026–2032 horizon.
This article serves as a strategic preview of the full study. It outlines the macroeconomic trajectory, highlights the operational and competitive dimensions covered in depth, and explains why the report's analytical architecture is calibrated to support high-stakes decision-making in the current year. The objective is not to replicate existing trade summaries, but to equip strategists, procurement leaders, and corporate planners with the conceptual scaffolding required to assess where the market is heading, who will shape its contours, and which structural variables will define profitability in the next cycle.
The Trajectory: Why 2026 Matters for Capital Allocation
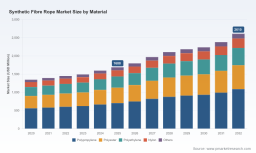
The global synthetic fibre rope market has demonstrated consistent expansion over the past half-decade, with total revenue growing from approximately 1,347 million USD in 2020 to an estimated 1,688 million USD in 2025. The forecast period extends through 2032, with projected revenue reaching roughly 2,610 million USD by the final forecast year. This trajectory reflects a compound annual growth rate of 6.5 percent, a figure that may appear moderate on its own but carries substantial structural implications when viewed through the lens of industrial demand intensity, raw material volatility, and regional capacity reconfiguration.
Synthetic Fibre Rope Market
For executives evaluating 2026 investment priorities, the key insight is not simply that the market is expanding, but that the composition of that expansion is shifting. High-performance synthetic variants are capturing incremental share in applications where failure risk, weight sensitivity, or corrosion resistance justify premium pricing. Meanwhile, conventional grades continue to anchor high-volume, cost-sensitive segments. Understanding which end-use categories are driving volume versus value, which materials are experiencing input-cost pressure, and how regional manufacturing footprints are adapting to logistics and sustainability mandates requires a granular view that only a structured market study can provide. The report dissects these layers systematically, enabling leadership teams to separate cyclical noise from durable demand shifts.
Inside the Research: Analytical Architecture and Operational Utility
The study is organized around a multi-dimensional analytical framework designed to translate complex market signals into actionable intelligence. Rather than presenting static snapshots, the research maps the interplay between material technology, application requirements, regional dynamics, and competitive behavior across the forecast window. The structure is deliberately built for cross-functional use: procurement teams can benchmark input exposure, R&D groups can evaluate material substitution pathways, sales leadership can align territory strategies with regional demand intensities, and corporate development teams can assess partnership, acquisition, or capacity-expansion opportunities.
Core analytical components include:
- Material-level performance and cost dynamics. The report examines how different synthetic families are positioned across performance tiers, weight-to-strength profiles, chemical resistance characteristics, and price sensitivity thresholds. It tracks how premium-grade materials compete against established conventional options, particularly in segments where total cost of ownership, not unit price, determines adoption.
- Application-driven demand mapping. End-use requirements vary dramatically across marine, industrial, energy, construction, and specialized technical sectors. The study evaluates the distinct performance criteria, procurement cycles, and regulatory environments shaping demand in each application cluster, helping readers anticipate where volume growth will be most concentrated and where specification upgrades will drive mix improvement.
- Regional market structure and supply chain considerations. Demand intensity, manufacturing presence, logistics constraints, and local regulatory frameworks differ meaningfully across geographies. The report contextualizes these differences to support localization decisions, import/export strategy, and regional partnership selection without reducing the analysis to oversimplified share rankings.
- Competitive positioning and strategic group analysis. The study profiles the operational focus, technological orientation, and market footprint of leading participants, enabling readers to understand where differentiation is being created, how certification and compliance capabilities affect purchasing decisions, and which collaborative or consortium-based initiatives are reshaping industry standards.
- Pricing context and input-cost exposure. Given the substantial cost differentials between synthetic and natural alternatives, as well as between conventional and high-performance synthetics, the research provides pricing context that helps procurement and finance teams model inventory exposure, capital expenditure sensitivity, and supplier negotiation leverage.
The full report goes further by integrating these dimensions into a coherent forecast model, allowing decision-makers to test assumptions around volume growth, material substitution, and regional expansion under varying macroeconomic and regulatory scenarios.
Competitive Landscape: incumbents, Specialists, and Standards Bodies
The synthetic fibre rope market is characterized by a blend of established manufacturers, technology-focused specialists, and regional producers with deep application expertise. Industry concentration is meaningful: the three largest participants account for approximately 62.5 percent of market revenue, while the top five collectively represent around 75.0 percent. This concentration shape has strategic implications. It suggests that pricing power, specification influence, and relationship-driven procurement remain significant in many end-use segments, while simultaneously leaving room for agile specialists to capture niche positioning through performance innovation, certification strength, or application-specific engineering support.
Several companies exemplify the competitive diversity shaping the sector today. Samson Rope Technologies, based in the United States, has built a reputation around high-performance synthetic ropes spanning polyester, nylon, and high-modulus polyethylene, with emphasis on lifting, rigging, marine, and safety applications. Teufelberger Holding AG, headquartered in Austria, supplies fiber ropes and high-performance synthetic rope solutions across marine, forestry, arborist, and industrial contexts. Lanex, operating from the Czech Republic, maintains a traditional manufacturing base serving marine, yachting, rescue, military, and industrial applications. Yale Cordage, also U.S.-based, focuses on advanced braiding techniques and high-tech synthetic rope systems for energy, marine, medical, and research environments. Unirope, based in Canada, emphasizes certified lifting and rigging synthetic rope products aligned with ISO 9001 and LEEA standards. Cortland Limited serves energy, subsea, marine, medical, and research sectors with high-tech ropes, slings, and strength members. In Europe, Oliveira has combined fiber rope and steel wire rope production since the early nineteenth century and remains active in EUROCORD, while COTESI and BADINOTTI, both Italian producers, participate in the same European association and serve industrial and marine applications.
These profiles matter because competitive advantage in this market is rarely determined by volume alone. Procurement teams in marine, energy, construction, and industrial settings often weigh certification credibility, technical support capacity, material consistency, and supply reliability alongside price. The report examines how such differentiators are translating into market positions and where consolidation, collaboration, or technology licensing may alter the landscape over the forecast period.
Recent Developments Shaping Strategic Assumptions
Several recent industry movements reinforce the need for updated decision frameworks in 2026. Price-environment observations from early 2026 indicate that synthetic ropes typically command substantial premiums over natural fiber alternatives, with cost ranges per meter varying widely by material class. Polypropylene and polyester remain positioned at lower price points relative to high-performance options, while ultra-high-molecular-weight polyethylene and similar advanced fibers occupy a significantly higher cost band. For large-scale operators managing substantial rope inventories across utility, marine fleet, or construction operations, these differentials have direct implications for working capital intensity and inventory strategy.
On the innovation and sustainability front, a notable product partnership announced in April 2026 brought together a high-tech rope producer and a protective materials specialist to develop a green synthetic rope manufactured in the United States. This type of collaboration signals growing investor and customer interest in reducing the environmental footprint of synthetic load-bearing products without sacrificing performance, and it underscores how regional manufacturing claims can become part of the value proposition in certain procurement contexts.
At the industry-organizational level, EUROCORD continues to serve as a focal point for synthetic rope producers in Europe and beyond. Recent annual meetings and newsletter activity have drawn participation from multiple established manufacturers, with emphasis on standards, industry updates, and collective positioning on material availability and sustainability. This institutional activity matters because standards alignment, quality expectations, and regulatory awareness increasingly influence specification decisions in marine, industrial, and energy applications. The study incorporates these dynamics to help readers understand how advocacy, standardization, and consortia participation can affect both competitive behavior and procurement requirements over time.
In parallel, broader material-market context indicates that fossil-based synthetic feedstocks have seen volume increases, alongside heightened attention to the availability and sustainability trajectory of biobased alternatives. For rope manufacturers and downstream buyers alike, this signals that input sourcing strategies, supplier diversification, and material substitution roadmaps will remain central to cost management and reputational positioning.
What the Full Study Enables
The complete research publication is designed to convert the themes outlined above into a practical decision-support toolkit. Readers can expect detailed baseline estimates, forward projections, and structured segmentation analysis that illuminate where growth is accumulating and how value is migrating across materials, applications, and regions. The study also provides competitive profiles, recent strategic developments, and industry-institution activity that help map the evolving rules of competition. Importantly, it frames pricing and input-cost dynamics in a way that supports scenario planning rather than static assumptions, recognizing that synthetic rope procurement is frequently a balance between performance assurance, total cost of ownership, and supply resilience.
For organizations making 2026 decisions on capacity, supplier selection, product development, regional entry, or market expansion, the report offers a consolidated reference point that reduces reliance on fragmented sources and ad hoc estimates. It is structured to be referenced by multiple functions simultaneously, with enough depth to support board-level narrative building and enough operational specificity to inform procurement, sales, and engineering planning.
Conclusion: Positioning for the Next Cycle
The synthetic fibre rope market is growing, but more importantly, it is re-composing. Growth is not uniformly distributed across materials, applications, or regions, and the premium-versus-value dynamic is reshaping both supplier strategy and buyer evaluation criteria. In this environment, the strategic question is no longer simply whether to participate, but how to position for the segments, specifications, and supply-chain configurations that will generate the most durable returns through 2032.
Synthetic Concrete Fibers Market
The full market research provides the depth, structure, and forward framing required to answer that question with confidence. For executives seeking to align capital, procurement, and competitive strategy with the next phase of market development, the study offers a rigorous starting point for 2026 planning and beyond.
For detailed analysis of this topic, please visit the official page: Synthetic Fibre Rope Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


