



PW Consulting: Agritourism Market Hits USD 9.01 Billion in 2025, Forecasts 11.9% CAGR to 2032

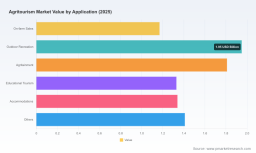
Agritourism Market Outlook 2026: Capitalizing on the Experience Economy via Strategic Intelligence
The convergence of agricultural production and experiential travel has evolved from a niche diversification tactic into a structural growth engine for rural economies. As hospitality consumers increasingly seek authenticity, provenance, and direct connection to land-based operations, agritourism has matured into a standalone commercial discipline. Our latest market research synthesizes historical trajectories, forward-looking demand signals, and competitive positioning to equip executive teams with the institutional intelligence required to navigate this rapidly shifting landscape. With the global market expanding from 5.8 billion USD in 2020 to a projected 10.43 billion USD in 2026, and an anticipated compound annual growth rate of 11.9 percent through 2032, the sector presents both remarkable expansion potential and complex operational trade-offs. Leaders who base capital allocation, partnership strategies, and market entry decisions on fragmented or retrospective data risk misjudging regional regulatory friction, consumer preference volatility, and the pace of infrastructure development. This analysis outlines how a disciplined, data-driven framework transforms uncertainty into executable strategy.
Executive Snapshot: Macro Trajectory and Structural Shifts
The agritourism sector has demonstrated consistent upward momentum over the past half-decade, reflecting a broader consumer migration toward localized, immersive, and mission-aligned travel. Revenue streams have expanded across direct-to-consumer farm interfaces, curated educational programming, and recreational event models, creating a diversified commercial ecosystem that rewards operators capable of balancing agricultural functionality with hospitality-grade service standards. The baseline forecast indicates continued acceleration, yet the pace and profitability of growth will vary significantly depending on regional tourism infrastructure, municipal zoning frameworks, seasonal capacity utilization, and the degree to which operators can integrate value-added processing into their visitor experience. Market concentration metrics further signal an industry in consolidation, where established players hold disproportionate share while emergent regional operators compete by specializing in high-touch experiences, targeted demographic segments, or hybrid agricultural-servitization models. Understanding where scale advantages concentrate, and where agile niche execution can outpace incumbents, is essential for portfolio planning and competitive benchmarking.
Report Architecture: How This Study Maps to Operational Decision-Making
A market intelligence briefing only delivers strategic value when it translates high-level trends into operational levers. This study is designed around that translation layer, moving systematically from macro sizing to actionable execution pathways. The research framework encompasses historical performance baselines, multi-year forecast modeling across primary commercial vectors, and a granular assessment of the competitive landscape. It evaluates how distinct experiential formats are monetized, how hospitality expectations are reshaping traditional farm operations, and how regulatory environments influence site development, liability exposure, and partnership viability. Readers will find structured sections covering demand drivers, consumer segmentation behaviors, capital deployment considerations, and the operational requirements of scaling agritourism from seasonal add-on activity to a year-round revenue architecture. The report deliberately avoids superficial market commentary and instead focuses on the mechanics of growth: visitor acquisition channels, experience design optimization, service capacity constraints, and the financial modeling required to sustain occupancy and repeat visitation. By anchoring analysis in measurable market signals rather than aspirational narratives, the study provides a repeatable methodology for stress-testing strategic options across different risk profiles and capital environments.
Agritourism Market
Competitive Landscape: Benchmarking Established Operators and Sector Archetypes
Agritourism is not a homogenous market. It operates as a layered ecosystem where luxury hospitality brands, specialized tour operators, educational programming providers, and regional farm consortia compete on different value propositions. Leading operators illustrate the strategic diversity available within the sector. High-end integrated resorts demonstrate how agricultural land can be positioned as a premium hospitality asset, combining working farm operations with curated culinary journeys, outdoor programming, and multi-day accommodation models that command elevated per-guest valuations. By contrast, escorted agricultural tour providers focus on connective infrastructure, linking international and domestic visitors to producer networks, rural tourism operations, and behind-the-scenes farming experiences that emphasize authenticity and direct producer engagement. Specialist tour firms extend this model further by offering inspection-oriented and bespoke itineraries designed for associations, professional audiences, and organizations seeking structured exposure to agricultural systems. Custom group travel providers layer programming around rural site visits for professionals, students, and sector enthusiasts, while dedicated agri-technical and educational tour operators build repeatable B2B and institutional channels through association partnerships and organizational programming.
These archetypes reveal distinct strategic postures. Luxury and integrated hospitality models compete on exclusivity, service depth, and land-based brand narrative. Tour and facilitation operators compete on access, logistics reliability, and curated producer relationships. Educational and institutional operators differentiate through content authority, program design, and repeatable group frameworks. Each model carries its own growth requirements, staffing demands, risk profile, and margin structure. Executive teams evaluating entry or expansion must assess where their organizational capabilities align within these competitive clusters, which consumer segments justify premium pricing, and which operational components can be sourced through partnerships rather than built in-house. The competitive analysis in this report maps these dynamics in detail, outlining positioning strategies, brand differentiation paths, and the implications of operating at different points along the experience spectrum.
Regulatory Friction and Structural Dynamics Shaping Deployment Timelines
Growth in agritourism is increasingly mediated by policy environments, land-use frameworks, and liability architectures. Regulatory signals are no longer peripheral; they directly affect site development schedules, operational scope, insurance cost structures, and the feasibility of scaling visitor-facing activities on agricultural land. Recent guidance published by regional agricultural authorities has begun to establish clearer baselines for value-added processing and agritourism operations, signaling a move toward more formalized compliance expectations. At the same time, local planning proposals addressing gatherings on farmland demonstrate how municipal priorities can reshape allowable visitor experiences, parking logistics, event frequency, and nighttime operations. Executive teams planning capital deployment must treat regulatory analysis as a core planning variable rather than a post-investment compliance task. Strategic advantage increasingly belongs to organizations that map jurisdictional variance early, incorporate permitting lead times into rollout roadmaps, and design flexible experience modules that can adapt to changing land-use parameters without sacrificing core revenue logic. On the policy side, broader legislative frameworks influencing program eligibility and income classification have begun altering the economics of farm-based diversification, particularly for operators heavily reliant on direct marketing and visitor revenue. These developments highlight the importance of scenario planning, where growth strategies account not only for demand-side opportunity but also for the administrative cadence and compliance cost embedded in different jurisdictions.
Operations Momentum and the Institutionalization of Agritourism
The sector is also maturing through organized industry activity that is accelerating knowledge transfer, peer benchmarking, and professionalization. Anniversary conventions, regional tourism workshops, and inaugural global conferences are creating venues where operators exchange practical insights on product development, seasonal planning, partnership formation, and experience economy integration. These gatherings reflect a broader shift from ad hoc farm diversification to coordinated industry building, where operators invest in staff training, guest journey design, and repeatable program structures rather than relying solely on informal rural charm. Alongside event-based momentum, select operators are launching dedicated retreat-style offerings that emphasize working-farm immersion, animal engagement, heritage storytelling, and natural setting experiences. Such launches underline the growing commercial appeal of multi-day stays and curated agricultural immersion, reinforcing the need for operators to think beyond day-visit revenue models.
Federal and regional economic data further support the migration toward experience-led farm revenue. Agritourism and recreational service income have expanded materially over the past decade, with meaningful participation spread across counties and median outcomes indicating broad-based, not merely outlier-driven, adoption. This trajectory suggests durable structural demand rather than a temporary travel cycle effect. Yet scale remains uneven. Margin quality, seasonality management, and the ability to convert first-time visitors into repeat guests continue to differentiate high-performing operators from those that merely capture transient foot traffic. The strategic question is therefore not whether demand exists, but how organizations build the operational discipline required to monetize it consistently across weather cycles, staffing constraints, and shifting consumer expectations.
Translating Market Intelligence into 2026 Decision-Making
For executives entering 2026, the practical challenge is prioritization under uncertainty. Capital can be allocated toward destination development, experience packaging, marketing acquisition, partnership expansion, or regulatory navigation, but each path carries different payback horizons and risk exposures. The strategic value of a comprehensive market study lies in its ability to compress that decision space by clarifying where growth is most defensible, which formats align with target demographics, and where competitive white space remains under-monetized. Organizations that build strategy on partial information often overinvest in visible but saturated demand channels while underweighting the operational complexity of service delivery, permitting, and year-round occupancy. Conversely, leaders who ground their planning in sector-specific sizing, segmentation dynamics, and competitive benchmarking can sequence investments more effectively, aligning capability building with the customer segments and experience formats most likely to sustain revenue resilience.
The report accompanying this article is designed to support that disciplined approach. It consolidates historical performance signals, forecast trajectories, competitive archetypes, and structural dynamics into a unified reference framework. By focusing on the mechanics of growth rather than isolated statistics, it enables leadership teams to evaluate entry timing, partnership strategy, experience portfolio design, and regional expansion with greater confidence. Agritourism is increasingly a strategic business discipline rather than a secondary farm activity, and the organizations that treat it accordingly will be better positioned to convert experiential demand into durable commercial advantage.
Strategic Conclusion and Next Steps
The agritourism market is moving into a phase where differentiation, operational precision, and regulatory fluency determine competitive outcomes more than raw destination appeal alone. The projected expansion curve through 2032 underscores the magnitude of the opportunity, while the competitive and regulatory context underscores the need for careful execution. Executive teams seeking to convert this opportunity into measurable performance should treat market intelligence as an active planning instrument, integrating sizing context, segmentation logic, competitor positioning, and policy dynamics into a coherent investment thesis. The full study provides the depth required to pressure-test those decisions across multiple growth scenarios and operational assumptions. We invite leadership teams, investors, and strategy functions to engage with the complete research package to align their 2026 planning with the market realities shaping this sector.
Worldwide Culinary Tourism Market
For detailed analysis of this topic, please visit the official page: Agritourism Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


