



Smart Office Market to Hit $99.87M by 2032 with 7.98% CAGR - PW Consulting Insights

Unlocking the Next Wave: Strategic Intelligence in the Smart Office Market (2026-2032)
As organizations navigate the post-pandemic normalization of hybrid work, the definition of the modern workplace is undergoing a fundamental reconstruction. The smart office is no longer a futuristic concept; it has become a critical determinant of operational resilience, cost efficiency, and employee retention. At PW Consulting, we recognize that capital allocation decisions made in 2026 will define competitive positioning for the remainder of the decade. Our latest market research release, Smart Office Market 2026-2032, is designed not merely as a statistical compendium but as a strategic compass for executives, investors, and technology leaders.
This article serves as a strategic preview, outlining the macro-economic trajectory, competitive structures, and dynamic forces shaping the ecosystem. By understanding the broader contours, decision-makers can better appreciate the depth of intelligence available in the full report, where granular segmentation and actionable forecasts reside.
The Macro-Economic Trajectory: Growth Anchored in Digital Transformation
The smart office market is experiencing a robust expansion phase driven by the convergence of IoT, AI, and sustainability mandates. Our analysis, anchored in historical data from 2020 through 2025 and projecting forward to 2032, reveals a consistent upward trajectory that defies broader economic volatility. The market valuation has demonstrated steady acceleration, moving from approximately 40.1 million USD in 2020 to an estimated 58.65 million USD in 2025. This historical performance sets the stage for a significant growth phase in the forecast period.
Looking ahead to 2026 and beyond, the momentum is expected to intensify. The market is projected to reach 62.88 million USD by 2026, with continued expansion toward the 99.87 million USD range by 2032. This growth path reflects a compound annual growth rate of 7.98 percent over the forecast period. Such a rate indicates that smart office technologies are transitioning from discretionary upgrades to essential infrastructure. For enterprise leaders, this trajectory suggests that delaying investment carries an opportunity cost, not only in terms of operational inefficiency but also in missing the window of early-adopter advantage.
It is crucial to note that these figures represent the broader market aggregate. The full report at PW Consulting decomposes this growth into nuanced segments that reveal where capital is flowing most aggressively. Early indicators suggest that certain categories are outpacing the average CAGR, driven by specific technological breakthroughs and regulatory pressures. However, identifying the precise winners and losers within vertical and geographic splits requires the detailed breakdowns provided in our paid intelligence suite. The aggregate numbers provide the confidence to invest; the segmentation provides the roadmap for allocation.
Competitive Dynamics: A Consolidated Battlefield
The market structure is characterized by a high degree of concentration, signaling maturity and the need for scale. Our analysis indicates that the top three competitors hold a combined market share of approximately 55.0 percent, while the top five entities control 62.0 percent. This concentration suggests that while the market is growing, the battleground for share is intense among established giants and specialized disruptors alike. Understanding the strategic positioning of these key players is vital for companies seeking partnerships or assessing competitive threats.
The landscape is dominated by large industrial and technology conglomerates that leverage diverse portfolios. Johnson Controls, headquartered in Milwaukee, Wisconsin, focuses heavily on IoT-enabled building management platforms that integrate occupancy sensing with HVAC and lighting automation. Similarly, Honeywell International, based in Charlotte, North Carolina, provides AI-powered occupancy sensors and integrated platforms designed for energy optimization in hybrid environments. Siemens AG, from Munich, Germany, offers IoT-enabled suites tailored for human-centric spaces, emphasizing adaptive systems for enterprise retrofits. Schneider Electric, located in Rueil-Malmaison, France, delivers building automation platforms that focus on multi-parameter environmental monitoring and energy management.
Beyond the heavy industrial players, the ecosystem includes specialized technology providers. Signify N.V., based in Eindhoven, Netherlands, manufactures the Interact Office occupancy intelligence platform, utilizing dense sensor networks for utilization optimization. Cisco Systems, from San Jose, California, integrates networking and security with IoT solutions to create connected hybrid workspaces. IBM, headquartered in Armonk, New York, develops Intelligent Workplace Management System platforms focused on space utilization analytics and cost reduction. Crestron Electronics, in Rockleigh, New Jersey, provides next-generation control systems with touchless interfaces and automation.
Smart Building Market
A second layer of innovation comes from niche players and software-focused firms. Framery, based in Helsinki, Finland, supplies smart seating and workspace solutions with real-time Space Overview software for booking management. Envoy, from Austin, Texas, offers workplace management software platforms addressing hybrid-work dynamics and visitor experience. Density, located in San Francisco, California, specializes in plug-and-play occupancy sensors for real-time people counting. viaim, also in San Francisco, develops AI-powered hardware including earbuds and tools for voice recording and transcription. Butlr, based in New York, New York, provides thermal occupancy sensors for anonymous people counting. XY Sense, also in San Francisco, manufactures enterprise occupancy sensors for utilization and sustainability integration.
Our full report provides a detailed comparative analysis of these entities, including their strategic moves, product roadmap alignment, and vulnerability assessments. For instance, recent developments such as viaim's launch of AI voice recorder earbuds and NoteKit tools in June 2025, or Framery's software launch for real-time free-space booking in January 2025, signal shifting priorities toward seamless collaboration and flexibility. Furthermore, industry bodies like AVIXA published guidelines in August 2025 regarding IoT security solutions, highlighting the critical intersection of connectivity and risk. These events are markers of the rapidly evolving competitive terrain that our analysis tracks in real-time.
Market Dynamics and Critical Friction Points
Growth is not without its complexities. The expansion of smart office infrastructure introduces significant dynamics around security, privacy, and regulatory compliance that can impact deployment strategies. As organizations deploy sensors and connected devices, the data generated can reveal patterns about employee behavior, workspace usage, and company operations. This sensitivity necessitates robust cybersecurity measures. The NIST Cybersecurity Framework provides flexible guidelines for identifying, protecting, detecting, responding to, and recovering from cyber incidents in these environments. Ignoring these protocols can expose firms to reputational and financial risk.
Data privacy remains another pivotal concern. GDPR requires transparent handling of personal data and empowers individuals with rights over their information in smart office IoT deployments. Compliance is not optional; it is a foundational requirement for scaling smart office solutions, particularly in regions with stringent data protection laws. Our report delves into the specific compliance landscapes that vary by jurisdiction, offering guidance on how to structure deployments that satisfy regulatory bodies without stifling innovation.
On the structural side, material costs and implementation strategies play a crucial role. Retrofit implementations of smart office solutions enable organizations to improve existing systems without the significant expenses tied to new construction. This factor is accelerating adoption rates among companies with legacy buildings. Additionally, regulatory frameworks are acting as demand pullers. The European Commission Directive 2024/1275 on the Energy Performance of Buildings imposes binding renovation quotas that pull forward demand for building automation in smart offices. These regulatory tailwinds are reshaping the investment thesis, making energy-efficient smart office technologies a compliance necessity as well as an operational choice. Determining the exact impact of these directives on regional demand requires the granular analysis found in the complete market study.
Smart Office Market
Operational Utility and Content Depth of the Report
PW Consulting's Smart Office Market report is engineered for immediate application. It moves beyond high-level trends to provide the specific intelligence required for budgeting, vendor selection, and market entry strategies. The report covers a forecast period from 2026 to 2032, building on a historical baseline from 2020. This long-view perspective allows strategists to model multiple scenarios and stress-test their plans against market volatility.
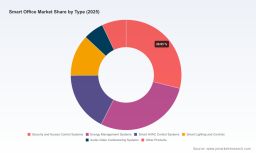
Inside the full document, readers will find detailed segmentation analysis that dissects the market by region, type, and application. While the aggregate market size provides the macro view, the segmentation reveals the specific drivers behind the numbers. For example, the report examines the relative performance of categories such as Security and Access Control Systems, Energy Management Systems, Smart HVAC Control Systems, Smart Lighting and Controls, Audio-Video Conferencing Systems, and Other Products. Understanding the revenue contribution and growth momentum of each category helps technology leaders prioritize R&D and procurement. Similarly, the application segmentation covers Corporate Offices, SMEs, Educational Institutions, Government Offices, and Healthcare Facilities. Identifying which application sector is driving the highest value capture is essential for solution providers targeting their sales efforts.
Furthermore, the report includes a rigorous analysis of regional dynamics. Global expansion patterns are influenced by local infrastructure readiness, funding availability, and regulatory environments. The full intelligence brief breaks down the market presence across key geographies, allowing multinational corporations to tailor their rollout strategies. We also provide a comprehensive competitor benchmarking matrix that evaluates market share, product portfolio strength, and strategic alliances. This tool is indispensable for M&A due diligence and partnership evaluation.
The report also integrates qualitative insights from industry experts and recent development tracking. We analyze product launches, software updates, and guideline publications that alter the competitive balance. For instance, the recent focus on cybersecurity standards by AVIXA and the continuous innovation from companies like Density and XY Sense in sensor technology are tracked to help clients anticipate market shifts. These insights are synthesized into actionable recommendations for navigating the complexities of project implementation, vendor negotiation, and risk management.
Why This Intelligence Matters for 2026 Decision-Making
In the current economic climate, precision is paramount. General market knowledge is insufficient for securing budget approval or defining a technology roadmap. Stakeholders require evidence-based forecasts that account for regulatory changes, technological disruptions, and competitive responses. The 7.98 percent CAGR and the projected growth toward 99.87 million USD by 2032 provide a strong narrative for growth, but the strategic value lies in knowing exactly where that growth is concentrated.
For investors, the market concentration metrics and competitor profiles offer a lens into market stability and potential consolidation opportunities. For technology vendors, the segmentation data highlights underserved niches and high-growth applications. For end-user organizations, the analysis of retrofit feasibility and energy mandates informs capital expenditure planning. The full report at PW Consulting consolidates these disparate data points into a coherent strategy document.
We invite you to explore the complete Smart Office Market 2026-2032 research. The preview above outlines the scope and strategic relevance, but the proprietary data, detailed segmentation splits, and actionable recommendations are available exclusively through our source page. Access the full report to gain the competitive edge needed to navigate the evolving landscape of the smart workplace.
For detailed analysis of this topic, please visit the official page: Smart Office Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


