



PW Consulting: Real Estate Software Market Hits $10.6B in 2025, Poised for 8.95% CAGR Growth to 2032

Navigating the Next Wave: Strategic Intelligence for the Real Estate Software Market in 2026 and Beyond
The real estate technology landscape is undergoing a structural transformation. As property operations grow more complex and capital allocation becomes more scrutinized, software is no longer a back-office utility; it is the operational nervous system of modern real estate portfolios. At PW Consulting, we have published a comprehensive research study on the Real Estate Software Market, designed to equip executive teams, investors, and technology strategists with the decision-grade intelligence required to navigate 2026 and the subsequent forecast horizon through 2032.
This article previews the strategic architecture of that study. It outlines the market's directional momentum, the competitive forces reshaping vendor ecosystems, the regulatory and operational dynamics that will define procurement decisions, and the practical analytical frameworks contained in the full report. Per the preview methodology, we present the structural insights needed to evaluate opportunity and risk, while reserving the granular segmentation data and detailed quantitative breakdowns for the complete publication. To access the full intelligence suite, including region-level sizing, application-specific revenue splits, and company-level scenario modeling, readers are directed to the source publication page.
Market Trajectory and the Strategic Case for 2026
The macroeconomic backbone of this study rests on a clear, sustained growth arc. Historical revenue data from 2020 through the 2025 base year demonstrates consistent expansion, validating the sector's resilience through shifting interest-rate environments and evolving asset management priorities. Building on that historical foundation, the forecast period projects continued upward momentum, anchored by a compound annual growth rate of 8.95 percent across the 2026–2032 window.
What does this trajectory mean for enterprise decision-making? First, it signals that demand for real estate software is not cyclical in the traditional sense; it is being structurally reinforced by automation, data centralization, and the operational complexity of managing fragmented portfolios. Second, the forecast's forward curve implies that market consolidation and capability differentiation will accelerate in parallel with top-line growth. Organizations that delay technology evaluation or treat software selection as a purely tactical procurement exercise will face compounding integration costs and capability gaps as the market matures.
The full research quantifies this trajectory across the forecast horizon, mapping year-by-year revenue progression and contextualizing the inflection points where adoption accelerates. Rather than presenting a single headline figure, the study decomposes momentum into the drivers that matter for planning: deployment velocity, workflow automation penetration, and the shifting balance between property-level and enterprise-grade system adoption. These are precisely the variables that determine whether a technology investment compounds value or becomes a stranded asset.
Competitive Landscape: Nine Leaders Defining the Modern Stack
Market growth is always mediated by competitive dynamics, and this sector is no exception. Our analysis centers on a core group of established and rapidly evolving vendors whose product roadmaps, Go-to-market strategies, and recent corporate moves collectively define the shape of the market. The study profiles nine companies whose positioning spans property management automation, enterprise resource planning, customer relationship management, commercial real estate data and analytics, brokerage and transaction workflows, and marketplace-driven search and valuation tools.
Each profile is structured to answer the questions that procurement and strategy teams actually ask. What workflow layer does the vendor own today? Where is the product extending next? How does the company's historical capability translate into near-term differentiation in an environment where AI-assisted operations are becoming table stakes? The study evaluates each organization's operational emphasis, from AI-powered automation and mobile-first workflows to tenant screening, lease tracking, maintenance request orchestration, leasing marketing tools, resident engagement, multifamily workforce automation, portfolio-level commercial operations, marketplace search and agent tools, and transaction management with property valuation capabilities.
Beyond static profiles, the report integrates recent corporate and product developments that signal strategic intent. In May 2026, MRI Software advanced its thought leadership around building versus energy management systems and the operational distinctions between lease and license frameworks, reinforcing its focus on nuanced property operations. The same month, the company appointed Dermot Briody as Chief Revenue Officer, a move aligned with scaling global growth and intensifying client-success execution. These developments illustrate a broader pattern: leading vendors are simultaneously deepening domain expertise and expanding commercial capability to convert technical differentiation into market share.
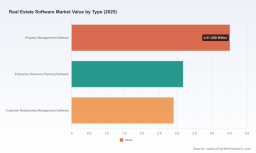
Property Management Software Market
The competitive timeline continues with notable product and corporate actions in the first half of 2026. In April, RealPage introduced an AI-powered workforce management tool designed to automate leasing, finance, and resident engagement tasks, reinforcing the operational automation trend at the multifamily layer. In January, CoStar Group announced a comprehensive AI deployment across its marketplace platforms to enhance user experience and sharpen competitive positioning, while also authorizing a new $1.5 billion share repurchase program as part of an accelerating AI-driven growth strategy. These moves are not isolated product announcements; they are indicators of how incumbents are reallocating capital and engineering focus in response to intensifying platform competition and elevated user expectations.
The full study goes further by mapping these companies against concentration signals in the market. With the top three firms commanding a substantial share of total revenue and the top five extending that footprint even further, the environment rewards both deliberate vendor selection and an understanding of where platform extensibility will create switching-cost dynamics. Enterprise buyers must assess not only current functionality but also the probability that a given vendor will become a long-term portfolio anchor versus a specialized component in a multi-vendor architecture.
What the Competitive Analysis Enables
- A structured comparison of vendor emphasis across property management, enterprise resource planning, customer relationship management, commercial real estate analytics, and brokerage and marketplace tools, so teams can align software selection with operational priorities rather than feature checklists.
- Product roadmap signaling derived from recent launches and thought leadership, helping organizations anticipate where automation, compliance support, and data integration will mature fastest.
- Capital-allocation context from corporate actions, including leadership changes and platform investment decisions, which provide leading indicators of where vendors intend to compete most aggressively.
- Concentration-aware procurement strategy, enabling buyers to weigh platform breadth, integration risk, and long-term negotiation leverage when structuring technology stacks.
Segment-level revenue distribution, regional breakdowns, and application-specific sizing are included in the full publication to support precise budgeting and market-entry planning. They are intentionally held back from this preview because their strategic value is best realized when paired with the complete analytical framework, scenario assumptions, and methodology notes available in the source report.
Market Dynamics Shaping Procurement and Adoption
Revenue growth alone does not determine outcomes. The sector's trajectory is being remolded by regulatory mandates, operational constraints, and data-governance pressures that alter both demand and implementation risk. The study treats these dynamics as first-order variables in forecasting, not as footnotes.
On the regulatory front, compliance expectations are increasingly encoded into software requirements. The implementation of the EU Corporate Sustainability Reporting Directive is compelling real estate companies to build comprehensive ESG data collection and reporting capabilities into their operations, making sustainability-focused data architecture a procurement consideration rather than an optional add-on. In parallel, the General Data Protection Regulation continues to drive investment in compliance-oriented software across real estate workflows, particularly where tenant, owner, and transaction data intersect with cross-border operations and sensitive personal information.
Data privacy and security concerns are also shaping growth patterns by demanding specialized compliance and cybersecurity measures within real estate software environments. As platforms consolidate more operational, financial, and resident data into unified systems, the attack surface expands, and the cost of inadequate controls rises. The study addresses how these requirements affect vendor evaluation, implementation timelines, and the relative attractiveness of platforms with mature governance frameworks versus those still maturing their security posture.
A second dynamic constraint is talent. The shortage of skilled practitioners in data analytics and AI deployment is cited as a primary brake on adoption and implementation quality. Even when software capabilities are available, organizations can struggle to extract value if internal teams lack the analytical fluency to configure, interpret, and continuously optimize platforms. This has two strategic implications. First, it elevates the importance of vendor-provided enablement, onboarding rigor, and ongoing support models. Second, it raises the premium on solutions that reduce the analytical burden through intuitive workflows, guided configuration, and automation that delivers outcomes without requiring deep in-house data science capacity.
These dynamics do not cancel growth; they channel it. Markets expand fastest where technology providers and enterprise buyers can jointly reduce implementation friction, satisfy compliance obligations by design, and convert operational data into actionable insight. The full research assesses how these dynamics interact with segmentation, regional maturity, and application-level demand to explain where adoption is most likely to accelerate and where execution risk remains elevated.
What the Full Study Delivers
The report is built for executives who need to move from directional awareness to actionable planning. It combines market sizing, forecast architecture, competitive profiling, and dynamics analysis into a single decision framework, with enough operational specificity to inform budgeting, vendor selection, product strategy, and market-entry evaluation.
Operational content in the study includes:
- Historical and forecast revenue architecture spanning the base year through 2032, with year-by-year progression that supports multi-horizon planning rather than single-point estimation.
- Structural segmentation analysis that explains how the market divides across regional environments, software types, and application settings, providing the context needed to evaluate where demand concentrates and where whitespace may exist.
- Company-level profiles and recent-event integration for the core competitive set, allowing teams to benchmark vendors against workflow coverage, automation orientation, and strategic intent.
- Market concentration analysis that clarifies the balance between incumbent strength and competitive openness, helping buyers and investors gauge platform leverage, substitution risk, and consolidation potential.
- Regulatory and operational dynamics assessment, including ESG reporting requirements, data protection obligations, privacy and security expectations, and workforce capability constraints, all linked to their practical impact on adoption and implementation.
The study is intended to support a range of decisions: whether to consolidate around a unified platform or maintain a modular stack; how to sequence implementation to manage compliance, security, and change-management risk; which vendor capabilities represent durable advantages versus transient feature leadership; and how to align software strategy with portfolio composition and growth targets. By integrating quantitative direction with qualitative competitive and regulatory context, the report is designed to reduce the gap between market awareness and execution planning.
Why This Report Matters for 2026 Decision-Making
2026 is a pivotal year because the market's growth rate, competitive intensity, and regulatory expectations are converging at the same moment. Organizations that treat real estate software as a static procurement category will underestimate the pace at which automation, data governance, and platform consolidation are reshaping operating models. Organizations that wait for perfect clarity will find themselves competing against peers who made earlier, better-informed technology commitments.
The strategic value of this study lies in its ability to convert a high-level growth narrative into structured decision support. The 8.95 percent compound annual growth trajectory signals that the opportunity is large and durable, while the concentration patterns and competitive developments indicate that not all platforms will capture that opportunity equally. The regulatory and operational dynamics explain why some implementations accelerate and others stall, and why software selection has become closer to portfolio strategy than to IT procurement.
For investors, the report provides a basis for assessing where platform economics, product extensibility, and regulatory tailwinds align. For enterprise buyers, it offers a framework for evaluating vendor durability, integration risk, and implementation readiness. For technology strategists, it maps the capability gradients that separate short-term feature play from long-term operational advantage.
Accessing the Complete Intelligence
This preview has outlined the strategic logic, competitive structure, and dynamic pressures that define the real estate software market as it moves through 2026 and toward 2032. It has presented the macro growth arc, the vendor behaviors that signal where competition is intensifying, and the regulatory and talent dynamics that will shape adoption outcomes. What it has not done is unlock the full quantitative segmentation, regional and application-level revenue distribution, or the detailed scenario analysis that supports precise planning.
Those elements are contained in the complete study. To access the full set of market sizes, forecast breakdowns, segmentation insights, company profiles, concentration metrics, and dynamics analysis, please visit the source publication page. There, the complete intelligence is available in a form designed for executive review, strategy workshops, procurement evaluation, and investment analysis.
The real estate software market will continue to reward organizations that combine operational discipline with clear-eyed technology strategy. PW Consulting's research is intended to provide exactly that clarity: enough depth to trust the direction, enough structure to act on it, and enough detail to make 2026 decisions with confidence.
Real Estate Software Market
For detailed analysis of this topic, please visit the official page: Real Estate Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


