



PW Consulting: Backer Board Market to Hit $3.23B by 2032, Growing at 5.85% CAGR

Decoding the Backer Board Market: Strategic Intelligence for 2026 and Beyond
The construction and renovation landscape is undergoing a period of intense recalibration, driven by shifting material costs, evolving regulatory frameworks, and a persistent demand for durable building envelopes. At the heart of this transformation lies the backer board market, a critical component in tile installations, wall cladding, and moisture-prone structural applications. For executives, procurement leaders, and strategic planners, navigating this space requires more than surface-level trends. It demands a rigorous, data-backed understanding of where the market has been, where it is accelerating, and how competitive forces will reshape value chains through 2032.
Backer Board Market
Our newly released Backer Board Market research report is designed precisely for that purpose. It distills years of historical tracking, forward-looking modeling, and on-the-ground industry intelligence into a single, actionable intelligence platform. Rather than offering generic market commentary, the study maps the structural drivers, material substitution patterns, and regional demand intensities that will dictate capital allocation, sourcing strategy, and product positioning in the coming cycle.
The Macro Trajectory: A Market in Structural Expansion
Over the past half-decade, the backer board sector has demonstrated consistent volume growth, underpinned by steady residential remodeling activity, commercial retrofit cycles, and the broader push toward moisture-resistant building standards. Historical tracking from 2020 through 2025 reveals a clear upward arc, with total market revenue climbing from approximately 1.5 billion USD to 2.09 billion USD. This progression was not linear; it reflected periods of supply chain normalization, fluctuating raw material pricing, and varying regional construction activity. Yet the overarching pattern is unambiguous: demand has solidified, and adoption curves have steepened as contractors and developers prioritize long-term durability over short-term cost avoidance.
Looking ahead, our forecasting model projects the market to reach 2.25 billion USD in 2026, with continued expansion through the end of the decade. By 2032, the sector is anticipated to approach the 3.2-billion-USD threshold, sustained by a compound annual growth rate of 5.85 percent. This trajectory is not merely a function of population growth or housing starts; it reflects deeper shifts in specification practices, code enforcement intensity, and the gradual migration toward engineered substrate solutions that outperform legacy alternatives. For strategic decision-makers, the implication is clear: the backer board category is transitioning from a commoditized auxiliary material to a differentiated, specification-driven product segment where early positioning yields measurable competitive advantage.
What the Report Delivers: Operational Intelligence, Not Just Headlines
Market research at its best should function as a decision-support system, not a static snapshot. Our study is structured to provide granular, actionable clarity across every dimension that influences sourcing, pricing, and go-to-market strategy. The report examines the full spectrum of product architectures, mapping the performance profiles, installation characteristics, and end-use suitability of the dominant material families that define the category. It evaluates how each type performs under varying moisture conditions, load-bearing requirements, and finish compatibility standards, enabling procurement teams to align material selection with project-specific risk profiles and lifecycle cost expectations.
The application layer receives equal scrutiny. We dissect how substrate demand bifurcates across tile installation environments, wet-area specifications, floor underlayment requirements, and countertop support systems. By tracing volume distribution across these use cases, the report highlights where adoption is accelerating, where substitution threats are emerging, and where specification lock-in is creating durable demand pools. This application-level breakdown is particularly valuable for manufacturers seeking to optimize product mix, distributors aiming to align inventory with regional project pipelines, and contractors evaluating material trade-offs against labor efficiency and warranty exposure.
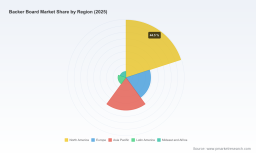
Regional demand intensity is analyzed through a lens of economic activity, building code enforcement, and import dependency dynamics. Rather than presenting static share percentages, the study prioritizes directional movement, identifying which geographies are experiencing structural demand expansion, which are plateauing due to market saturation or regulatory headwinds, and which are emerging as high-growth corridors fueled by infrastructure modernization and renovation cycles. This geographic intelligence is cross-referenced with supply chain logistics, freight cost sensitivity, and localized raw material availability, providing a practical foundation for regional capacity planning and distribution network optimization.
Beyond segmentation, the report embeds a comprehensive competitive landscape assessment. We profile the market’s leading participants, evaluating their product portfolio breadth, manufacturing footprint, innovation cadence, and strategic positioning. The analysis captures how incumbents are leveraging brand recognition, technical support networks, and specification relationships to defend core share, while also tracking how newer entrants and niche players are exploiting gaps in lightweight alternatives, moisture-specific formulations, and sustainability-aligned material profiles. The result is a clear view of where competitive pressure is concentrating, where margin pools are most defensible, and where partnership or acquisition logic may emerge as the market matures.
Competitive Architecture: Incumbents, Differentiators, and the Innovation Frontier
The backer board market’s competitive structure is defined by a mix of established building material conglomerates, specialized substrate manufacturers, and regional brands with strong distribution ties. Leading the field are companies that have built long-standing relationships with contractors, distributors, and specification channels, leveraging decades of product iteration and technical support infrastructure. United States Gypsum Company, for instance, anchors its position through dedicated cement and fiber cement backer board offerings that emphasize structural compatibility and widespread specification acceptance. James Hardie, with its dual headquarters structure and deep North American operational presence, has cultivated a similarly entrenched footprint, reinforced by product lines that align closely with exterior and interior moisture-management standards.
Back Glue Market
Parallel to these incumbents, specialized players are carving out distinct positioning through material innovation and niche application focus. Grip-Rite has advanced its portfolio with magnesium oxysulfate-based substrate solutions designed to offer lightweight handling, improved durability, and reduced reliance on traditional cement formulations. PermaBASE Building Products has concentrated on cement backer board variants that balance installation efficiency with performance consistency, while Gold Bond Building Products has pushed into gypsum-based tile backer alternatives that address mold resistance and interior finish compatibility. National Gypsum Company operates at a critical junction in this ecosystem, functioning as an exclusive service provider for key product lines and reinforcing the interconnected nature of manufacturing, distribution, and specification support.
Recent product and platform developments underscore how quickly the innovation frontier is moving. In mid-2025, Grip-Rite introduced a mineral-based, eco-conscious backer board and underlayment line, emphasizing reduced chemical complexity, improved weight characteristics, and durability aligned with modern installation expectations. Later that year, James Hardie expanded its contractor and homeowner engagement toolkit through an AI-driven exterior design customization platform, reflecting a broader industry shift toward digital specification support and end-user visualization. These moves are not isolated product launches; they signal a strategic reorientation toward sustainability messaging, installation efficiency, and specification-friendly digital tools, all of which are reshaping how buyers evaluate substrate options.
Market Dynamics: Cost Pressures, Regulatory Flux, and Material Economics
No strategic assessment of the backer board market is complete without confronting the macroeconomic and regulatory currents that influence material pricing, project feasibility, and procurement behavior. Cement and mineral-based substrates sit at the intersection of building material supply chains that are highly sensitive to trade policy, energy costs, and industrial capacity utilization. Recent trade actions have introduced tariff structures that affect cement imported from neighboring trading partners, with industry advocates cautioning that such measures could elevate project costs, delay infrastructure timelines, and complicate energy and security-related construction planning. These dynamics do not merely influence headline pricing; they alter contractor margin calculations, developer budgeting assumptions, and the relative attractiveness of alternative substrate formulations.
At the project level, builder associations have estimated that recent tariff-driven cost effects can add substantial per-home expenses, pressuring affordability thresholds and nudging specification decisions toward materials that balance performance with total installed cost. Simultaneously, higher input prices and intermittent availability constraints for certain raw materials are eroding purchasing power and tempering discretionary spending in segments where cost sensitivity is acute. Yet the broader production environment has shown resilience, with recent index movements indicating sustained industrial activity and capacity utilization that support ongoing material availability, albeit within a volatile pricing landscape.
These intersecting forces create a highly contextual demand environment. In high-end residential and commercial specification segments, performance and durability often justify premium substrate choices, insulating demand from short-term cost fluctuations. In more price-sensitive remodeling and volume development contexts, however, buyers are increasingly scrutinizing the trade-offs between traditional cement-based boards, lightweight alternatives, and gypsum-composite variants. The result is a market where material economics, installation labor considerations, and warranty expectations are being re-evaluated simultaneously, and where suppliers that can articulate clear total-cost-of-ownership advantages will capture disproportionate specification share.
Strategic Implications for 2026 Decision-Making
For executives operating in or adjacent to the backer board sector, the current environment demands a disciplined, data-informed approach to portfolio planning, sourcing strategy, and competitive positioning. The growth trajectory through 2032 is robust, but the path is uneven, shaped by regional construction cycles, regulatory adjustments, and material substitution dynamics that will vary significantly across application types and customer segments. Companies that treat the market as a monolithic commodity space risk misreading where margin pools are forming, where innovation premiums are sustainable, and where distribution leverage is most critical.
Our research is designed to convert that complexity into clarity. It provides the structural framework needed to evaluate product mix decisions, anticipate specification shifts, and align go-to-market investments with the segments where demand is most durable. By integrating historical performance tracking with forward-looking modeling, competitive profiling, and real-time industry developments, the report equips decision-makers with the context required to navigate pricing volatility, evaluate substitution threats, and identify partnership or expansion opportunities before the market fully prices them in.
The full study goes deeper, offering detailed segmentation analysis, company-level benchmarking, application-specific demand mapping, and scenario-based forecasting that unpacks the variables most likely to influence the next several years of market evolution. For procurement leaders, product strategists, and investment planners, that depth is not optional; it is the difference between reactive adjustment and proactive positioning.
To explore the complete dataset, competitive profiles, and forward-looking scenario analysis, access the full Backer Board Market research report. The detailed intelligence contained within is structured to support immediate strategic application, from sourcing renegotiation and product portfolio optimization to regional expansion planning and specification strategy refinement.
For detailed analysis of this topic, please visit the official page: Backer Board Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


