



PW Consulting: IED Market Hits $171.5M in 2025, 7.53% CAGR to 2032

Strategic Intelligence in the Intelligent Electronic Devices Market: Navigating Growth Through 2032
Executive Overview
The global landscape for Intelligent Electronic Devices is undergoing a structural transformation, driven by the accelerating digitalization of electrical infrastructure and the urgent need for reliable, secure, and interoperable control systems. As utilities, industrial operators, and transportation networks modernize their legacy architectures, the demand for next-generation protection, monitoring, and automation hardware continues to reshape competitive positioning across the sector. Our latest market research publication provides a comprehensive, data-driven examination of this evolving landscape, offering executives and strategy teams a clear line of sight into the commercial trajectories, regulatory pressures, and technology adoption curves that will define strategic decision-making in 2026 and beyond.
Built on an extensive baseline of historical performance spanning 2020 through 2025, the study projects market evolution across a seven-year forecast horizon extending to 2032. The analysis captures the compounding effect of infrastructure modernization programs, the integration of advanced sensing and control electronics into substation and distribution environments, and the broader shift toward intelligent, software-defined operational frameworks. For organizations seeking to align capital allocation, product development roadmaps, and market-entry strategies with empirical evidence rather than speculation, this report delivers the rigor required to navigate an increasingly complex ecosystem.
Macro Market Trajectory: Compounding Growth and Structural Inflection Points
Over the past half-decade, the Intelligent Electronic Devices market has demonstrated consistent expansion, with total global revenue climbing steadily from 2020 through 2025. That historical momentum establishes a robust foundation for the forecast period, during which the market is expected to maintain a compound annual growth rate of 7.53 percent. This growth trajectory reflects more than incremental adoption; it signals a structural inflection as critical infrastructure operators prioritize grid resilience, automation depth, and cybersecurity readiness in equal measure.
By 2026, the market is projected to surpass the 186-million-dollar threshold, marking a decisive step up from the preceding year's baseline. The subsequent years of the forecast period reveal an accelerating cadence of expansion, with revenue scaling toward higher plateaus as capital projects mature and deployment cycles compound across multiple end-use sectors. The midpoint and latter years of the outlook period show sustained upward movement, culminating in a market valuation that underscores the entrenched role these devices now play in modern electrical and industrial ecosystems.
This macro trajectory is not merely a function of unit volume growth. Pricing dynamics, technology premiumization, and the shift toward integrated hardware-software bundles all contribute to the revenue expansion captured in our modeling. Organizations that understand how these value drivers intersect with regional deployment timelines and application-specific procurement cycles will be better positioned to anticipate demand fluctuations and tailor their commercial strategies accordingly.
Intelligent Control Market
Segmentation Landscape: Product Typologies and Application Vectors
The Intelligent Electronic Devices market is inherently multidimensional, with demand distributed across a diverse set of hardware categories and operational use cases. Our research dissects this landscape through multiple analytical lenses, enabling decision-makers to identify which product families and application segments are generating the strongest pull, where substitution dynamics are intensifying, and how technological convergence is reshaping traditional category boundaries.
Intelligent Electronic Devices Market
On the product side, the market encompasses a broad spectrum of intelligent control and protection hardware. Digital relay platforms continue to anchor a significant share of demand, reflecting their centrality to substation automation and fault management architectures. Voltage regulation devices represent another major pillar, serving applications where precise electrical parameter control is essential for system stability. Protection relay solutions maintain a strong presence, particularly as operators upgrade legacy electromechanical installations with microprocessor-based alternatives that offer enhanced diagnostic capabilities and communication integration.
Beyond these core categories, the market includes a range of specialized control and switching devices that support increasingly granular grid management requirements. Circuit breaker control platforms, load tap changer controllers, recloser controllers, and capacitor bank switching equipment each address distinct operational needs within distribution and transmission networks. The presence of additional niche product categories further illustrates the breadth of the ecosystem, with innovation increasingly concentrated at the intersection of hardware reliability and digital communication readiness.
Application-side demand is equally varied. Automation remains the dominant deployment vector, as operators seek to reduce manual intervention, improve response times, and integrate device-level intelligence into centralized control environments. Condition monitoring applications represent a substantial and growing demand stream, driven by the industry's shift toward predictive maintenance methodologies and real-time asset health assessment. Traction signaling and control systems constitute another critical application domain, particularly as rail and transit electrification programs expand and require highly reliable signaling electronics. Water supply and management systems also represent a meaningful application segment, where intelligent control devices support distribution efficiency, leakage detection, and operational resilience.
The challenge for commercial leaders is that these segmentation dynamics do not operate in isolation. Product adoption is increasingly influenced by application-specific performance requirements, regional regulatory mandates, and the pace at which interoperability standards are enforced across procurement specifications. Our report maps these cross-currents in detail, allowing organizations to calibrate their product positioning and sales focus without relying on oversimplified category assumptions.
Competitive Dynamics: Enterprise Positioning and Strategic Differentation
The competitive environment in the Intelligent Electronic Devices market is characterized by a carefully balanced concentration structure. The three largest firms collectively account for approximately thirty-five percent of total market revenue, while the top five players extend their combined share to roughly forty-two percent. This structure indicates a market where scale, technological maturity, and global distribution capabilities confer meaningful advantages, yet sufficient fragmentation remains to enable specialized players to compete on engineering depth, regional responsiveness, and application-specific expertise.
Among the leading enterprises, several global technology and industrial groups hold prominent positions, each leveraging distinct strategic assets to reinforce their market presence. ABB Ltd., headquartered in Zurich, maintains a strong footprint in intelligent device portfolios designed for substation automation and protection applications, with an emphasis on integrating device-level intelligence into broader grid-edge ecosystems. Schneider Electric SE, based in France, continues to advance its offering through architectures that align intelligent electronic hardware with energy management platforms and digital service layers, appealing to operators seeking unified operational visibility. Siemens AG, operating from Munich, draws on its established industrial automation and electrification heritage to deliver device solutions that emphasize interoperability, engineering integration, and lifecycle support across complex infrastructure projects.
GE Vernova, headquartered in the United Kingdom, contributes a focused presence in intelligent device solutions tied to power generation, transmission, and distribution modernization initiatives, with product strategies that reflect the operational priorities of utilities managing large-scale asset fleets. Eaton Corporation plc, based in Ireland, advances its position through offerings that combine protection, control, and power management functionalities, often emphasizing compact form factors and integration with broader electrical distribution architectures. Honeywell International Inc., headquartered in the United States, brings relevant expertise from adjacent industrial control and automation domains, supporting demand in environments where intelligent electronics must operate under stringent reliability and safety conditions.
Schweitzer Engineering Laboratories, Inc., also based in the United States, is widely recognized for its specialized focus on protection and control engineering, with product portfolios that resonate strongly in markets where technical differentiation, engineering support, and substation-level customization are valued by procurement teams. Hitachi Energy, headquartered in Zurich, rounds out this competitive field with offerings that connect intelligent device capabilities to broader power system transformation initiatives, including high-voltage applications and grid-scale digitalization programs.
What distinguishes leading players in this market is not merely product breadth, but the ability to align hardware offerings with cybersecurity expectations, interoperability requirements, and lifecycle service models. Procurement teams increasingly evaluate vendors based on support for standardized communication frameworks, firmware update pathways, and documentation that facilitates compliance with critical infrastructure protection mandates. Organizations that can demonstrate consistent conformance, transparent engineering credentials, and reliable deployment support are more likely to secure long-term contract relationships in an environment where operational downtime carries substantial financial and reputational consequences.
Regulatory and Standards-Driven Dynamics
The Intelligent Electronic Devices market is increasingly shaped by standards and regulatory expectations that influence both product design and procurement eligibility. A significant recent development is the publication of the IEEE Standard for Intelligent Electronic Devices Cybersecurity Capabilities, including Corrigendum 1, released in December 2025. This update reinforces the cybersecurity capabilities expected of devices deployed in critical infrastructure environments, reflecting a broader industry consensus that intelligent electronics must be evaluated not only for electrical performance, but also for their resilience against digital threats. For vendors, this means that security features, configurable access controls, and documented vulnerability management practices are becoming integral components of product competitiveness rather than optional enhancements.
In parallel, conformance with IEC 61850-6 remains a fundamental expectation for devices intended for substation automation environments. Interoperability is no longer a desirable feature; it is a prerequisite for integration into modern communication-centric substation architectures. As operators standardize on communication protocols and data modeling approaches, devices that cannot demonstrate reliable conformance risk exclusion from tenders and system integration programs. These standards dynamics create both a compliance burden and a strategic opportunity: organizations that invest early in rigorous testing, transparent conformance documentation, and integration-ready product design can differentiate themselves in markets where system architects are under pressure to reduce integration risk.
Beyond formal standards, the broader regulatory environment is reinforcing the importance of operational reliability, secure update pathways, and long-term support commitments. Infrastructure operators managing critical networks are increasingly attentive to supply chain continuity, firmware lifecycle management, and the ability to maintain device performance over extended deployment horizons. These concerns are reshaping vendor evaluations and encouraging a shift from transactional purchasing toward relationship-based procurement models centered on lifecycle assurance.
Operational Contents and Decision-Support Architecture
This market research publication is designed to serve as a practical strategic tool rather than a static reference document. The analysis is structured to support a range of enterprise decisions, from portfolio planning and market prioritization to competitive benchmarking and risk assessment. The report integrates historical performance data, forecast modeling, segmentation analysis, and competitive profiling into a coherent framework that can be applied across multiple functional teams.
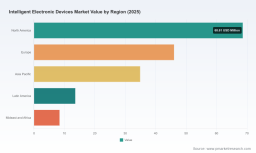
Readers will find detailed demand analysis across product categories and application segments, with emphasis on the factors that are accelerating adoption in certain environments while restraining growth in others. The competitive assessment goes beyond aggregate positioning to examine how leading firms structure their offerings, where they appear to be investing in capability development, and how their strategic footprints align with the macro trends shaping the market. Regional demand patterns are also examined, with attention to the differences in deployment pacing, procurement behavior, and infrastructure modernization priorities that influence where growth opportunities are most concentrated.
The report further incorporates an assessment of the strategic implications of evolving standards and cybersecurity expectations, helping organizations anticipate how compliance requirements may affect product design priorities, sales cycles, and long-term support obligations. By connecting regulatory developments to commercial consequences, the analysis provides a clearer basis for investment decisions, partnership strategies, and go-to-market planning.
For product leaders, the study offers insight into where category growth is most durable and which performance attributes are becoming non-negotiable in competitive bids. For commercial and sales teams, it provides context on the procurement drivers shaping demand across major application domains. For executive planners, it delivers a consolidated view of market size trajectories, concentration dynamics, and the structural forces that will influence profitability and share movement over the forecast period.
Strategic Imperatives for 2026 Decision-Making
Entering 2026, organizations operating in or adjacent to the Intelligent Electronic Devices market face a landscape defined by simultaneous opportunities and constraints. Demand is expanding at a steady compound rate, but the composition of that demand is shifting as automation priorities deepen, monitoring capabilities become more sophisticated, and cybersecurity expectations move from advisory guidance toward procurement requirements. In this environment, the ability to interpret market signals accurately is a decisive advantage.
One clear imperative is to align product and service strategies with the integration expectations of modern infrastructure projects. Devices that support standard communication frameworks, documented cybersecurity capabilities, and reliable lifecycle management are better positioned to meet the evaluation criteria of system integrators and utility procurement teams. A second imperative is to monitor segmentation dynamics with sufficient granularity to avoid overreliance on broad category assumptions. Demand strength varies meaningfully across product families and application domains, and commercial strategies that account for these differences are more likely to capture high-value opportunities.
A third imperative involves competitive positioning. In a market where the largest firms hold a substantial but not dominant share, differentiation can be achieved through engineering depth, regional execution quality, and the ability to reduce integration and compliance risk for customers. Organizations that understand where incumbents are strong and where customer unmet needs persist can identify viable entry points and partnership opportunities. Finally, leadership teams should treat standards evolution as a strategic input rather than a compliance afterthought. Anticipating how cybersecurity specifications and interoperability requirements will shape future procurement criteria can help organizations avoid reactive redesign cycles and position their offerings ahead of tender clarifications.
Conclusion
The Intelligent Electronic Devices market is entering a phase in which growth is supported by durable infrastructure modernization needs, yet competitive outcomes will increasingly depend on how well firms navigate integration standards, cybersecurity expectations, and application-specific demand shifts. Our comprehensive market research publication provides the analytical foundation required to make those strategic judgments with confidence. By combining historical context, forecast projections, segmentation intelligence, and a detailed competitive assessment, the report equips decision-makers with the insights needed to prioritize investments, refine market strategies, and respond effectively to the operational realities of 2026 and the years that follow.
For executives and strategy professionals seeking a complete picture of market size trajectories, segmentation dynamics, regional demand patterns, and vendor positioning, the full study offers the depth and specificity necessary to translate high-level trends into actionable business decisions. Detailed figures, segment-level breakdowns, and extended competitive profiles are available in the complete report, which can be accessed through our official research portal for teams requiring comprehensive intelligence to support planning, procurement strategy, and long-range investment decisions.
For detailed analysis of this topic, please visit the official page: Intelligent Electronic Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


