



PW Consulting: Functional Sugar Market Hits $2.47B in 2025, Projected 6.2% CAGR to $3.81B by 2032

The Functional Sugar Market: Navigating the 2026 Growth Curve
The global landscape for functional sugars is undergoing a structural transformation. As consumer demand shifts steadily toward clean-label, low-calorie, and gut-health-supporting ingredients, manufacturers are recalibrating their portfolios to capture value in a high-growth segment. Our latest market research positions stakeholders to make informed decisions with a clear view of the macroeconomic trajectory and the competitive forces shaping the industry. Between 2020 and 2032, the market is projected to expand from 1.85 billion USD to 3.81 billion USD, reflecting a compound annual growth rate of 6.2 percent over the forecast period. This sustained expansion signals a durable shift rather than a transient trend, driven by regulatory approvals, supply chain maturation, and a broadening base of applications across food, beverage, and dietary supplement formats.
For executives evaluating capital allocation, product development pipelines, or market entry strategies in 2026, the window to act is narrowing. The pace of innovation among leading ingredient suppliers has accelerated, and the regulatory environment continues to evolve in ways that reward early movers with validated health claims and scalable production capabilities. This report distills those dynamics into a decision-ready framework, giving you the context needed to prioritize investments where demand signals are strongest and competitive pressure is most acute.
A Market on the Rise: Key Trajectory Signals for 2026
The historical record demonstrates a consistent upward climb. From 2020 through 2025, revenue grew each year, reaching 2.47 billion USD by 2025. Looking ahead, the forecast extends through 2032 and outlines a path that carries the total toward 3.81 billion USD. The progression is not uniform; it reflects a combination of volume growth, value-added formulations, and expanding geographic reach. By 2026, the market is expected to cross the 2.69 billion USD mark, establishing a new baseline for the decade ahead.
Several underlying drivers support this trajectory. First, the post-pandemic consumer emphasis on preventive health has elevated the role of gut microbiome support and metabolic stability as key purchase drivers. Functional sugars that deliver prebiotic benefits or moderate glycemic responses are increasingly embedded in everyday products, from breakfast cereals and snack bars to ready-to-drink beverages and capsule-based supplements. Second, manufacturing innovation has reduced the cost premium historically associated with specialized sweeteners, allowing brands to integrate functional sugars without sacrificing price competitiveness. Third, ingredient sourcing strategies are adapting to supply side realities; for example, EU sugar beet prices navigated a period of increase in the early 2020s before stabilizing in 2024 and softening during the first half of 2025, while USDA forecasts projected U.S. sugar production at a record 9.42 million short tons in the 2025/26 season. These supply factors influence cost structures and regional sourcing decisions, and they are examined in detail within the report to help procurement teams anticipate volatility.
Within this context, the buildup in capacity by major players is particularly noteworthy. Tate & Lyle expanded allulose production capacity by 35 percent in March 2025 to improve supply availability for low-calorie sweeteners, and Cargill has advanced fermentation-based functional sugar solutions that improve production efficiency for dietary supplement and food manufacturers. These moves signal confidence in sustained demand, but they also raise the bar for competitors and purchasers alike: access to premium functional sugars will increasingly depend on long-term partnerships and secured supply chains.
Rising from 1.85 Billion to 3.81 Billion: What the Growth Curve Means for Strategy
A market moving from 1.85 billion USD in 2020 to a projected 3.81 billion USD in 2032, at a CAGR of 6.2 percent, invites a straightforward question: where is the greatest value-creation potential concentrated, and how should organizations align their capabilities to capture it? The growth curve is not just a number; it is a signal of demand elasticity, category readiness, and regional maturity. As the base expands, differentiation becomes essential. The strongest performers are likely to be those that combine science-backed ingredient claims with consistent supply, regulatory compliance, and formulation flexibility.
Our analysis confirms that market leadership is fragmented rather than consolidated, a structural feature that creates room for niche positioning and targeted partnerships. The top three players collectively account for 34.5 percent of revenue, while the top five hold 49.2 percent. No single entity dominates, and the spacing between leading firms allows specialized suppliers to build durable presence in distinct applications or geographies. This dynamic is reinforced by the entry of regional and specialty manufacturers that bring formulation depth, localized sourcing, and proprietary processing methods. For brands evaluating suppliers, the implication is clear: supplier selection should weigh technical capability, claim substantiation, and capacity reliability alongside price.
The report frames these market-level signals in a way that supports scenario planning. Executives can use the trajectory data to model revenue ranges under different adoption timelines, assess the timing of product launches relative to regulatory milestones, and identify segments where the margin opportunity is widening fastest. Because the forecast spans multiple years, it also exposes inflection points where capacity additions or regulatory changes could alter competitive positioning, making now an ideal moment to review your roadmap against the data.
Competitive Landscape: How Tier-1 Innovators Are Defining the Next Wave
A resilient competitive field has emerged around functional sugars, with incumbents leveraging scale and specialists competing on formulation intelligence and claim support. The companies featured in this research represent a cross-section of strategies: some focus on core sweeteners with documented metabolic benefits, others emphasize fiber-based ingredients for digestive health, and several invest in sustainability as a differentiator. The report profiles each and compares their capabilities, recent moves, and positioning.
Tate & Lyle, headquartered in London, offers functional sugars including allulose and isomaltulose for blood sugar management and prebiotic benefits in dietary supplements and beverages. Its capacity expansion in allulose underscores a bet on consumer appetite for low-calorie, glycemic-friendly sweeteners. C.argill, based in Wayzata, provides fermentation-based functional sugar solutions with improved production efficiency for dietary supplement and food manufacturers, a route that can reduce cost and improve consistency. Ingredion, located in Westchester, launched a next-generation prebiotic sugar ingredient in January 2026 that improved digestive health performance by 24 percent for premium supplement formulations, an example of how formulation advances can accelerate adoption in higher-margin categories. ADM, in Chicago, supplies natural functional sugar ingredients to global beverage and food companies for North American operations, emphasizing broad reach and operational reliability. BENEO, in Karlsruhe, specializes in chicory root-derived functional carbohydrates and fibers for blood sugar management and sugar reduction, with regulatory recognition such as the FDA GRAS Notice 1242 for short-chain fructooligosaccharides issued in June 2025, which exempted specified uses from premarket approval.
On the plant-based and fiber side, Roquette Frères, in Lestrem, develops plant-based functional sugar and fiber ingredients for food, beverage, and supplement applications, and released its 2026 sustainable actions report in June 2026 highlighting biodiversity and nature initiatives in functional ingredient production. Tereos Group, in Origny-Sainte-Benoite, produces functional sugar solutions from beet and cane sources for sweetening and health-focused food products. Cosucra Groupe Warcoing, in Warcoing, extracts chicory root fibers such as PISANE™ as functional ingredients for sustainable nutrition and sugar alternatives. Nexira, in Rouen, supplies natural acacia and botanical extracts as functional ingredients for blood sugar control in supplements. In the low-calorie sweetener space, Samyang Corporation, in Seoul, manufactures allulose as a next-generation low-calorie functional sugar sweetener for beverages and snacks, while Matsutani Chemical Industry, in Itami, develops FIBERSOL® soluble dietary fiber and allulose for prebiotic and sugar-reduction applications.
Functional Chewing Gum Market
Across these players, three themes recur: diversification of sweetness and fiber platforms, investment in processing and capacity, and a sharper focus on validated health outcomes. The report maps these strategies to the segments and applications where they are most relevant, giving buyers a comparative lens to evaluate partnerships and procurement options with greater precision.
Functional Sugar Market
Segmentation Drivers: Ingredient Types, Application Breadth, and Regional Dispersion
The functional sugar market is not monolithic; it spans multiple ingredient types, application areas, and regional ecosystems, each with its own growth logic and competitive dynamics. The analysis segment the market by type, application, and region to surface where momentum is building and which combinations are likely to outperform.
By type, the market includes oligogaccharide, inulin, sugar alcohols, and other specialty categories. Oligosaccharides and inulin anchor the prebiotic narrative, while sugar alcohols and next-generation low-calorie sweeteners address glycemic management and calorie reduction. The "others" category captures emerging botanicals and fiber blends that continue to gain traction in premium formulations. The report examines each category substantively, without disclosing segment-level revenue shares, to help formulation teams match ingredient properties to functional goals and cost constraints.
By application, the breadth is broad and expanding. Food and beverage remain the largest usage base, where functional sugars are embedded in everyday products to deliver taste, texture, and health positioning. Dietary supplements constitute a significant and growing channel, where claims around digestive health and metabolic support are increasingly central to product identity. Pharmaceuticals and other applications contribute additional demand, often governed by stricter specifications and quality standards. The research outlines the differentiators across these applications, including regulatory requirements, formulation compatibility, and the strength of consumer demand signals, to guide category strategy and packaging decisions.
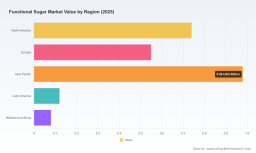
By region, the dispersion reflects differences in consumer preferences, regulatory frameworks, and supply infrastructure. North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa each present distinct opportunities and constraints. The report provides qualitative context on regional momentum drivers and sourcing patterns, again withholding exact split percentages, so that readers can calibrate their geographic focus to the most relevant growth engines without pre-judging local execution challenges.
Two regulatory developments frame part of this regional picture. EFSA extended the use of isomalto-oligosaccharide as a novel food under Regulation (EU) 2015/2283, a step that broadens the application canvas for certain prebiotic ingredients in Europe. In parallel, FDA granted GRAS notice 1242 for short-chain fructooligosaccharides from BENEO for use in certain foods, exempting those specified uses from premarket approval and simplifying formulation pathways. Together, these moves illustrate how regulatory milestones can unlock new product possibilities and influence regional prioritization.
Formulation and Sourcing Realities: What Operational Teams Need to Know
Turning market opportunity into commercial reality requires attention to the mechanics of formulation and sourcing. Functional sugars must perform not only as health-forward ingredients but also as contributors to taste, mouthfeel, stability, and shelf life. Each category presents trade-offs. Oreosaccharide and inulin can deliver prebiotic functionality and fiber content, but their behavior in different matrices varies; sugar alcohols offer sweetness profiles and glycemic moderation, yet their inclusion levels must be managed carefully; allulose and related low-calorie sweeteners can replicate sugar-like taste with lower caloric impact, but supply availability and cost remain important considerations for high-volume programs.
From a sourcing standpoint, the ability to secure consistent quality and volume is increasingly tied to supplier investment in processing efficiency and capacity. Cargill's fermentation-based solutions, for instance, reflect a broader industry shift toward more efficient production routes that can support scale without sacrificing quality. Meanwhile, sustainability is moving from a narrative element to an operational one: Roquette's 2026 sustainable actions report underscores biodiversity and nature initiatives as part of functional ingredient production, a signal that procurement teams may increasingly evaluate suppliers on environmental performance alongside cost and reliability. The report details the operational considerations relevant to each major ingredient route and supplier type, helping teams weigh formulation goals against supply continuity and total cost of ownership.
Regulatory alignment is another operational thread. The EU sugar beet price trajectory, the record U.S. sugar production forecast, and the evolving status of novel food approvals all influence cost structures and formulation options. By synthesizing these variables, the research equips teams to anticipate changes and adjust sourcing strategies before they become reactive.
Turn Insights into 2026 Decisions: The Full Intelligence Awaits
The functional sugar market is positioned for a sustained run of growth, with a clear upward trajectory, an active competitive field, and a regulatory environment that continues to open new possibilities. The report translates these macro trends into actionable intelligence, covering market sizing across historical and forecast years, segmentation by type, application, and region, competitive profiling of leading and emerging players, and the latest industry developments that could affect sourcing, formulation, and go-to-market timing in 2026 and beyond. It is designed to support multiple use cases: portfolio planning, supplier selection, market entry evaluation, pricing strategy, and long-range scenario modeling.
Because the decision space is competitive and time-sensitive, partial visibility carries risk. The report delivers the full segmentation detail, including regional breakdowns, application splits, and type-level analysis, alongside company comparisons and regulatory context, so that your team can act with precision. The complete intelligence is available on the source page; accessing it will give you the granular data needed to benchmark opportunities, validate assumptions, and set priorities for the year ahead.
Now is the moment to align your strategy with the data. As the market moves toward the 2026 baseline and beyond, organizations that combine strong formulation insight with reliable supply and clear health claims will be best placed to capture value. The research provides the foundation; your next step is to secure the full intelligence and translate it into concrete actions.
For detailed analysis of this topic, please visit the official page: Functional Sugar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


