



PW Consulting: Vehicle Telematics Market Hits $93.61B in 2025, Driven by 8.7% CAGR to $167.85B by 2032

Unlocking the Road Ahead: Strategic Intelligence for the 2026 Vehicle Telematics Landscape
The global automotive ecosystem is undergoing a profound transformation, driven by connectivity, data ubiquity, and an escalating demand for operational efficiency. At the center of this shift lies vehicle telematics, a technology once relegated to simple tracking but now serving as the central nervous system of modern mobility, fleet management, and insurance underwriting. As enterprises navigate the complexities of 2026, understanding the trajectory of this market is not merely an advantage; it is a strategic imperative.
Our latest comprehensive market research delves into the multifaceted dynamics of the vehicle telematics industry, offering a granular view of where value is being created, how competitive forces are aligning, and what regulatory headwinds lie on the horizon. This article serves as a strategic preview of the full report, highlighting the macroscopic trends and qualitative shifts that will define decision-making for the remainder of the decade. For senior leadership teams, the insights contained within this study provide the necessary framework to allocate capital, mitigate risk, and identify high-growth vectors in a rapidly consolidating landscape.
The Trajectory of Growth: A Macro View
The momentum behind vehicle telematics is undeniable. Following a robust historical performance from 2020 through 2025, the market has demonstrated resilience against supply chain disruptions and economic volatility. The total revenue generated across the sector has climbed steadily, reflecting an increasing integration of telematics hardware and software into both legacy and next-generation vehicle platforms. This growth is not accidental; it is the result of a structural shift where connectivity is no longer a premium feature but a baseline expectation for commercial and consumer vehicles alike.
Vehicle Telematics Market
Looking forward, the forecast period from 2026 to 2032 suggests a continued expansion trajectory. Market projections indicate that the industry is expected to advance toward a valuation exceeding 167 billion USD by the end of the forecast window. This expansion is underpinned by a Compound Annual Growth Rate (CAGR) of 8.7 percent, signaling a healthy, sustained demand curve. Such growth rates are characteristic of an industry moving past its early adopter phase and entering a period of broad-scale integration and maturation.
This macroscopic growth narrative is supported by consistent year-over-year revenue increases. The baseline established in 2025 at approximately 93.61 billion USD serves as the springboard for the estimated 101.46 billion USD mark expected in 2026. As organizations plan their strategic roadmaps, aligning internal targets with these external market signals is crucial. The data suggests that the window for capturing market share remains open, but it is narrowing as technology standards converge and barriers to entry evolve.
Navigating Segmentation and Technological Shifts
While the overall numbers tell a story of growth, the composition of that growth reveals where the strategic opportunities lie. The market is characterized by a diverse array of solution types, ranging from embedded systems directly integrated into vehicle manufacturing to tethered and integrated aftermarket solutions. The prevalence of embedded technologies suggests a transition toward seamless, factory-installed connectivity that leverages OEM partnerships. This shift reduces installation friction and enhances data reliability, aligning with the broader industry move toward software-defined vehicles.
OBD Telematics Market
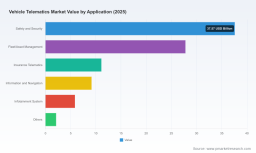
Application-wise, the demand drivers are multifaceted. Safety and security remain paramount, reflecting the industry's commitment to reducing accidents and enhancing asset protection. Meanwhile, fleet and asset management applications continue to drive significant volume, as logistics and transportation companies seek to optimize routes, monitor driver behavior, and reduce total cost of ownership. Beyond these core verticals, insurance telematics is reshaping risk assessment models, allowing for more granular pricing based on actual driving data rather than demographic proxies. Information, navigation, and infotainment systems further round out the ecosystem, enhancing the user experience and creating additional touchpoints for data monetization.
It is within these segments that the real strategic nuance exists. Organizations must understand not just the size of each segment, but the velocity of adoption and the specific pain points each application addresses. Our full report dissects these areas to identify which sub-sectors are poised for acceleration and which may face saturation earlier than anticipated.
Competitive Dynamics and the Path to Consolidation
The competitive landscape of the vehicle telematics market is both crowded and intensely competitive. A select group of key players commands a significant portion of the market share, indicating a trend toward concentration among established vendors with robust technology stacks and global reach. The top three players alone account for over half of the market share, while the top five extend their influence to cover approximately seventy percent of the total market. This level of concentration suggests that scale, technological differentiation, and ecosystem partnerships are becoming increasingly critical differentiators.
Leading the charge are companies that have expanded beyond simple tracking to offer holistic platforms. Geotab, headquartered in Mississauga, Canada, continues to set the pace with its comprehensive vehicle telematics platform, integrating GO devices, OEM-embedded solutions, and AI analytics capabilities through its Geotab Ace initiative. Their focus on supporting mixed fleets and electric vehicle data positions them well for the transition to electrification. Similarly, Samsara in San Francisco has built a formidable connected telematics platform that unifies GPS, driver safety tools, and diagnostics into a cohesive workflow for fleet visibility and risk management.
The competition is further heated by innovative entrants and established players pivoting strategies. Motive, also based in San Francisco, differentiates itself by integrating video signals with vehicle data, enabling more effective driver coaching and asset monitoring. Verizon Connect and Teletrac Navman provide robust equivalents with a focus on real-time GPS, maintenance alerts, and OEM integration strategies that bridge the gap between factory-fitted hardware and cloud analytics. Meanwhile, companies like Trimble and Omnitracs emphasize diagnostics, predictive maintenance, and route optimization, catering to the operational efficiency needs of heavy and commercial fleets.
Recent developments underscore the pace of innovation. In early 2026, LG Electronics unveiled a next-generation smart telematics solution that integrates the Telematics Control Unit and antenna into a single module, marking their first participation at MWC Barcelona and signaling a push toward design efficiency and enhanced connectivity. Earlier in 2025, Teletrac Navman launched an OEM Telematics integration for their TN360 platform, allowing seamless data access from factory-fitted hardware without aftermarket installation. These moves highlight the industry's focus on hardware integration and reducing installation complexity. Furthermore, strategic alliances are reshaping the value chain; for instance, Cambridge Mobile Telematics announced a partnership with TransUnion to leverage portable consumer driving scores, reinforcing the growing synergy between telematics data and broader financial and insurance ecosystems.
Regulatory Tailwinds and Headwinds
No discussion of vehicle telematics strategy in 2026 would be complete without addressing the regulatory environment. The industry is operating within a complex web of compliance requirements that vary significantly by geography. In the United States, federal rules now require affirmative certification for information and communications technology supply chain security in connected vehicles and telematics systems. This mandate aims to enhance resilience but imposes additional due diligence requirements on manufacturers and integrators. Additionally, the US International Trade Commission has extended its investigation into certain vehicle telematics and video-based safety systems, creating a period of regulatory uncertainty that organizations must monitor closely.
Across the Atlantic, the European Union has implemented stringent mandates affecting heavy vehicles. The second-generation smart tachograph V2 became mandatory for vehicles over 3.5 tonnes, with strict timelines for adoption and migration of first-generation units. The EU General Safety Regulation further mandates commercial vehicle telematics requirements, and the Data Act, effective from 2025, grants users access to raw vehicle data. This shift empowers end-users but challenges traditional data monopolies held by OEMs and platform providers. In North America, state-level legislation is also evolving; for example, North Carolina now requires insurer notice and consent before using vehicle telematics data, signaling a broader trend toward consumer privacy and data sovereignty.
For enterprises, these regulations are not just compliance hurdles but strategic variables. They influence product design, data handling protocols, and international expansion strategies. Our report provides a detailed mapping of these regulatory landscapes to help organizations anticipate compliance costs and leverage regulatory standards as competitive moats.
Strategic Imperatives for 2026 and Beyond
As the market moves toward 2032, the organizations that will thrive are those that can synthesize these various threads into a coherent strategy. The convergence of AI, video analytics, and embedded connectivity is creating new value propositions that go beyond basic tracking. Companies like Powerfleet and Geosavi are pushing the boundaries of video-based telematics and AIoT platforms, integrating SaaS solutions that offer deeper operational insights. Teltonika and Linxup are focusing on hardware durability and AI-enabled safety features, such as dash cameras for distracted driving detection.
For strategic planners and investors, the key questions revolve around where to place bets in this ecosystem. Should the focus be on the hardware layer, the software analytics layer, or the data marketplace? How will OEM integration strategies evolve as manufacturers gain more control over vehicle data? What is the impact of insurance telematics on consumer behavior and fleet procurement? Our full market research addresses these questions with detailed segmentation analysis, competitive benchmarking, and scenario planning.
The vehicle telematics market is at an inflection point. The growth rates forecast suggest a maturing industry with significant room for innovation, while the competitive and regulatory dynamics indicate that passive participation is no longer viable. Organizations need access to precise, actionable intelligence to navigate this terrain effectively. The full report provides the depth, data, and strategic context required to turn market complexity into competitive advantage. We invite you to explore the complete study to gain the insights necessary for informed decision-making in this critical sector.
For detailed analysis of this topic, please visit the official page: Vehicle Telematics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


