



PW Consulting: Hazardous Location Lighting Market Hits $531.56M in 2025, Booms 4.88% CAGR to 2032

Strategic Lighting in Hostile Environments: A 2026 Decision-Making Framework
The global infrastructure landscape is undergoing a period of intense recalibration. As industries expand into more remote and hazardous operational theaters, the demand for reliable, compliant, and energy-efficient illumination has become a critical boardroom priority. Our latest research release, the Hazardous Location Lighting Market report, provides a comprehensive roadmap for navigating this complex sector between 2026 and 2032. This analysis is not merely a collection of statistics; it is a strategic instrument designed to help stakeholders align capital allocation with safety mandates and technological shifts.
Hazardous Location Lighting Market
For decision-makers operating in heavy industry, energy, or infrastructure development, understanding the trajectory of hazardous location lighting is essential. The market has demonstrated resilience and steady growth over the past five years, recovering from global supply chain disruptions to establish a robust upward trend. In 2020, the market valuation stood at approximately $418.88 million, growing to $531.56 million by 2025. This historical performance underscores the inelastic demand for specialized lighting solutions that ensure operational continuity in high-risk zones. The forecast period projects this momentum to continue, with revenue expected to reach $558.27 million in 2026 and climb toward $741.3 million by 2032. This growth trajectory, reflecting a compound annual growth rate of 4.88 percent, signals a mature yet expanding market where strategic positioning can yield significant long-term returns. However, these aggregate figures only tell part of the story. The real value lies in understanding the drivers behind these numbers and how they intersect with regulatory changes and technological advancements.
Market Dynamics and Regulatory Pressures
The hazardous location lighting sector is defined by its stringent compliance requirements. Unlike general industrial lighting, products designed for explosive atmospheres must meet rigorous safety standards to prevent ignition sources. The regulatory environment is tightening, creating both barriers to entry and opportunities for compliant innovators. A significant development shaping the 2026 landscape is the introduction of new product model certification requirements under NEC 2026. This update mandates specific model-level IIC gas group approvals for explosion-proof LED lights, moving beyond broader family ratings. For procurement managers and engineering teams, this means that legacy approvals may no longer suffice, necessitating a review of current inventory and future procurement strategies to ensure full compliance.
Furthermore, the technical benchmarks for safety and efficiency are being raised. The DesignLights Consortium finalized SSL V6.0 technical requirements for hazardous location lighting in November 2025, mandating safety testing by OSHA NRTL or equivalent bodies. This standard emphasizes the importance of verified safety testing alongside performance metrics. Companies that have already aligned their product lines with these emerging standards are better positioned to capture market share, while those lagging risk exclusion from major supply contracts. These regulatory shifts are not just compliance hurdles; they are market segmentation tools that favor established players with robust certification portfolios. Our report dives deep into how these regulations impact different regions and product categories, helping you anticipate compliance costs and timelines.
On the material side, the construction of explosion-proof lighting fixtures relies on heavy-duty materials such as stainless steel, aluminum, or glass-reinforced polyester for enclosures and components. The availability and pricing of these raw materials can influence manufacturing costs and final product pricing. As supply chains stabilize, manufacturers are optimizing material usage to balance durability with cost efficiency. Understanding the interplay between material costs and regulatory requirements is crucial for forecasting margin pressures and pricing strategies in the coming years.
Technological Shifts and Application Diversity
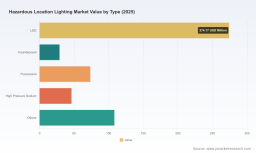
The transition from traditional lighting technologies to advanced LED solutions is a dominant theme in this market. While legacy technologies such as incandescent, fluorescent, and high pressure sodium fixtures still hold presence in specific niches, LED has become the primary driver of growth and innovation. LED luminaires offer superior energy efficiency, reduced maintenance requirements, and longer lifespans, which are critical advantages in hazardous environments where access for maintenance can be dangerous and costly. The shift is evident across various applications, including oil and gas, mining and steel, railway, power and energy, and military and public safety sectors.
Each application segment presents unique challenges and lighting requirements. For instance, the oil and gas sector demands robust solutions capable of withstanding explosive gases and harsh environmental conditions, often requiring Zone 1/2 or Division 1/2 certifications. Mining and steel industries require lighting that can endure dust, heat, and physical impact. Railway and power sectors have specific visibility and reliability standards. Military and public safety applications often require portability and extreme durability. Our analysis explores how different lighting types are suiting these diverse needs, highlighting where LED adoption is accelerating and where traditional technologies remain relevant due to specific operational constraints. We examine the nuances of these applications without oversimplifying, providing a clear view of where demand is concentrated and how it is evolving.
Recent industry exhibitions highlight the pace of innovation. For example, Dialight Corporation exhibited ATEX and IECEx-certified LED lighting solutions, including ProSite LED Floodlights and SafeSite high bay luminaires, at Hazardex Live 2026 in February. Such events demonstrate the industry's focus on showcasing certified, high-performance products that meet the latest safety standards. The presence of major manufacturers at these venues underscores the competitiveness of the market and the importance of continuous product development to maintain technological leadership. By analyzing these trends, our report helps you identify which technologies are gaining traction and which vendors are leading the innovation curve.
Competitive Landscape and Key Players
The market is characterized by a competitive landscape where consolidation and specialization are key strategies. The top three companies hold a combined market concentration of 45.0 percent, while the top five control 55.0 percent. This indicates a moderately concentrated market with room for niche players but dominated by large conglomerates with extensive resources and global reach. Several key companies define the current competitive dynamics, each bringing distinct strengths to the hazardous location lighting sector.
- Eaton Corporation plc , headquartered in Dublin, Ireland, is recognized as a leader in the Crouse-Hinds series LED luminaires. Their HPL and HPLN series are specifically engineered for Zone 1/2 and Zone 21/22 hazardous environments, featuring global certifications and energy-efficient designs. Eaton's strength lies in its comprehensive portfolio and global distribution network, making it a go-to partner for multinational projects requiring standardized compliance.
- Hubbell Incorporated , based in Stamford, Connecticut, USA, produces the Killark VML-X series of high and low bay LED fixtures. These products are certified for Class 1 Div 2 and Zone 2 hazardous locations, catering to industrial settings where safety and performance are paramount. Hubbell's focus on durable, high-bay solutions makes it a strong contender in heavy industrial applications.
- Dialight Corporation , located in New Jersey, USA, provides ProSite LED floodlights and SafeSite high bay luminaires with ATEX and IECEx certifications. Their recent participation in Hazardex Live 2026 highlights their commitment to showcasing advanced solutions for industrial hazardous areas. Dialight's specialization in LED technology for harsh environments positions them as an innovator in the space.
- Emerson Electric Co. , through its Appleton Group in St. Louis, Missouri, offers Areamaster Connect LED luminaires and Linmaster series for Class I Division 2 hazardous locations. Emerson emphasizes energy savings of up to 80 percent with their solutions, appealing to operators focused on reducing total cost of ownership while maintaining safety standards. Their connected lighting options also align with Industry 4.0 trends.
- Signify Holding N.V. , headquartered in Eindhoven, Netherlands, manufactures industrial and hazardous area LED lighting solutions, including long-life fixtures designed for harsh environments. Signify's strong brand presence in lighting and focus on sustainability and longevity make it a significant player, particularly in regions with strict energy efficiency mandates.
These players are not just competing on product features; they are competing on certification breadth, global service support, and technological integration. Recent developments, such as Dialight's exhibition of certified solutions, reflect the ongoing race to meet evolving standards and customer expectations. Our report provides a detailed competitive analysis, examining market share dynamics, product strategies, and the strategic moves these companies are making to solidify their positions. We analyze how their offerings map to different regulatory zones and application needs, giving you a clear picture of the competitive field.
Worldwide Helideck Explosion Proof Light Market
Strategic Implications for 2026 and Beyond
For stakeholders planning their 2026 strategies, the hazardous location lighting market presents several actionable insights. First, the tightening regulatory environment means that compliance is no longer optional; it is a competitive differentiator. Procurement teams must verify that suppliers meet the latest NEC 2026 and DesignLights Consortium requirements to avoid project delays or safety liabilities. Second, the shift toward LED technology is accelerating, driven by energy savings and operational reliability. Investment in LED infrastructure in hazardous zones can yield significant long-term savings and reduce maintenance risks. Third, the competitive landscape favors vendors with global certifications and robust service networks. Partnerships with established players like Eaton, Hubbell, Dialight, Emerson, or Signify can provide access to proven technologies and localized support.
Our full report goes beyond these high-level observations to provide granular data on regional demand patterns, type-specific growth rates, and application-level analysis. We break down the market forces driving growth in different areas and identify which segments are poised for expansion. The detailed segmentation analysis allows you to pinpoint opportunities aligned with your specific business interests, whether you are looking at regional markets, product types, or end-use applications. You will gain insights into pricing trends, technology adoption curves, and the impact of raw material costs on the supply chain. We also explore the implications of market concentration, helping you understand the balance of power among key suppliers and the potential for new entrants.
The data spans the historical period from 2020 to 2025 and provides a detailed forecast through 2032. This longitudinal view enables trend analysis and scenario planning. You can see how the market evolved from the pandemic era through recovery and into the current growth phase, and how it is projected to mature. Such context is invaluable for long-term capital planning and risk assessment. By accessing the complete intelligence, you can move from reactive compliance to proactive strategic positioning.
In conclusion, the Hazardous Location Lighting Market research report serves as an essential resource for navigating the complexities of this vital industry. With rigorous data, expert analysis, and a focus on strategic decision-making, it empowers you to make informed choices that drive safety, efficiency, and growth. To access the full depth of our analysis and secure the intelligence needed for your 2026 planning, we invite you to explore the complete report. The details that will shape your strategy are waiting to be uncovered.
For detailed analysis of this topic, please visit the official page: Hazardous Location Lighting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


