



PW Consulting: Fullerene Market to Reach $600M by 2032 Amid 7.8% CAGR Growth

Strategic Intelligence for the Fullerene Market: Navigating Growth, Supply Constraints, and Competitive Shifts Through 2032
The global fullerene market stands at a pivotal inflection point. What began as a niche materials segment has matured into a cross-industry enabler spanning high-purity electronics, advanced cosmetics, pharmaceutical formulations, and next-generation energy systems. For executives and strategy teams operating in 2026, the decisions made today around feedstock security, purity validation, and application diversification will define competitive positioning over the next half-decade. This market research report delivers a structured, data-grounded blueprint for navigating that complexity.
Our analysis traces the market trajectory from its historical baseline through a forward-looking forecast window. The sector reached an estimated valuation of 358.91 million USD in the 2025 base year, building on consistent growth momentum since 2020 when the market was evaluated at 250.0 million USD. The compound annual growth rate of 7.8 percent projects the market toward approximately 600.0 million USD by 2032. This trajectory is not merely a numerical forecast; it reflects structural shifts in manufacturing capability, regulatory evolution, and the migration of fullerene materials into higher-value applications. Understanding where growth concentrates, which purity thresholds are becoming commercially non-negotiable, and how supply-side constraints are reshaping cost structures is essential for capital allocation, partnership strategy, and product roadmapping.
Market Trajectory and Structural Drivers
The historical series from 2020 to 2025 demonstrates a compounding expansion pattern. Revenue scaled from 250.0 million USD in 2020 to 275.27 million USD in 2021, continued to 298.41 million USD in 2022, advanced to 316.88 million USD in 2023, reached 342.75 million USD in 2024, and closed at 358.91 million USD in 2025. This steady progression signals a market that has moved beyond early-stage volatility into a more predictable growth rhythm. The forecast horizon extends that momentum through 2032, with projected annual valuations climbing from 386.43 million USD in 2026 to 406.58 million USD in 2027, 446.49 million USD in 2028, 473.23 million USD in 2029, 506.52 million USD in 2030, 568.88 million USD in 2031, and 600.0 million USD in 2032.
Several interlocking forces underpin this expansion. First, the migration of fullerene-based materials from laboratory-scale research into validated commercial processes is broadening the addressable market. High-purity grades are increasingly specified in optical and electronic formulations where performance thresholds demand consistent molecular quality. Second, regulatory scrutiny around nanomaterials has intensified, reshaping validation requirements and elevating the commercial premium for materials that meet stringent purity benchmarks. Third, feedstock dynamics are introducing new cost and availability considerations that reward manufacturers and buyers who secure resilient supply chains. These drivers do not operate in isolation; they interact to create both margin pressure and differentiation opportunities for organizations that align procurement, R&D, and compliance strategies early.
Supply-Side Realities and Regulatory Headwinds
Graphite remains the foundational feedstock for fullerene production, anchoring the entire value chain to upstream carbon material economics. Recent years have seen tighter export controls on natural graphite, particularly from China, which has constrained global feedstock availability and contributed to elevated supply-chain costs. For procurement and operations leaders, this is not a transient disruption. It represents a structural recalibration that favors diversified sourcing strategies, long-term offtake agreements, and manufacturers with integrated purification capabilities. Companies that rely on single-source feedstock exposure face heightened vulnerability to price volatility and lead-time variability, while those that hedge across geographies and grades can stabilize input costs and protect margin profiles.
On the regulatory front, the FDA has ramped up risk assessments and validation requirements for nanomaterials, a shift that directly influences fullerene procurement specifications. The practical outcome is rising demand for ultra-high-purity fullerene materials at thresholds of 99.5 percent and 99.9 percent or higher, alongside validated purification techniques that can withstand scrutiny in regulated end markets. This trend is especially relevant for pharmaceutical and cosmetic applications, where traceability, batch consistency, and documented purification pathways increasingly determine whether a material qualifies for advanced formulation pipelines. Organizations that treat purity validation as a strategic capability rather than a compliance checkbox will be better positioned to capture premium segments and reduce time-to-market for next-generation products.
The Competitive Landscape and Strategic Positioning
The fullerene market exhibits meaningful concentration, with the top three players accounting for approximately 57.0 percent of market share and the top five expanding that footprint to roughly 63.0 percent. This concentration underscores the importance of understanding not just who the incumbents are, but how their technological capabilities, certification milestones, and application focus shape competitive dynamics. The following companies anchor the current landscape and illustrate the strategic diversity within the sector.
Nano-C, Inc.
Headquartered in Westwood, Massachusetts, United States, Nano-C operates as the leading US manufacturer of high-purity C60, C70 fullerenes, and functionalized derivatives via combustion synthesis. Its product and process orientation is tightly aligned with organic photovoltaics, electronics, and nanotechnology applications. In May 2026, the company achieved ISO 9001:2015 certification for advanced electronic materials including fullerenes, a milestone that reinforces its credibility in quality-sensitive electronic supply chains and signals a deliberate focus on manufacturing consistency and customer qualification requirements.
SES Research Inc.
Based in Houston, Texas, United States, SES Research functions as a manufacturer and distributor of premium C60 fullerenes and derivatives, with a commercial emphasis on wellness, supplements, and research-grade applications. Its positioning highlights the divergence within the market between high-specification industrial materials and consumer-facing or research-oriented product lines, where branding, purity communication, and application-specific testing play outsized roles in commercial success.
Frontier Carbon Corporation
Located in Tokyo, Japan, Frontier Carbon specializes in high-volume combustion-synthesis fullerenes and derivatives designed for cosmetics, pharmaceuticals, and electronics. The company's application breadth reflects a strategic emphasis on scale and multi-segment relevance, aligning volume production with the purity and consistency requirements that regulated and performance-driven end markets demand.
MER Corporation
Operating from Tucson, Arizona, United States, MER Corporation supplies mixed fullerenes including C60 and C70, along with higher-order fullerenes, for research and materials applications. Its portfolio orientation illustrates the continuing importance of research-grade supply and specialty material variants that support R&D pipelines, prototype development, and materials science discovery.
BuckyUSA, Inc.
Also based in the United States, BuckyUSA operates as a market-driven producer of fullerene materials for science and industrial uses. Its commercial model highlights the role of flexible, application-responsive production in serving diverse buyer requirements across academic, industrial, and specialized materials contexts.
Solenne BV
Headquartered in Groningen, the Netherlands, Solenne produces high-quality fullerene derivatives including PCBM grades at scales up to the kilogram level. This capability is particularly relevant for customers that require derivative-grade materials with controlled specifications and scalable batch production, bridging the gap between laboratory research and pilot-scale or early commercial deployment.
Together, these players demonstrate that the competitive landscape is not monolithic. Differentiation emerges through purity thresholds, certification status, production scale, application specialization, and geographic positioning. For buyers and investors alike, understanding which capabilities align with specific end-use requirements is critical to selecting partners, structuring supply agreements, and identifying white-space opportunities where incumbent coverage remains incomplete.
Report Scope and Practical Value for Decision-Makers
This market research report is designed to translate macro trends into actionable intelligence. It provides a comprehensive analytical framework that covers market sizing, growth decomposition, segmentation dynamics, competitive profiling, and forward-looking scenario considerations. Rather than presenting numbers in isolation, the report embeds them within the operational and regulatory contexts that determine how those numbers translate into real-world strategy.
Readers will gain clarity on how the market evolved from 2020 through 2025, why the projected 7.8 percent CAGR is grounded in observable demand and supply dynamics, and which structural factors are likely to accelerate or moderate growth through 2032. The analysis examines how purity requirements, feedstock availability, and application migration interact to shape margin structures and procurement strategies. It also maps the competitive landscape in a way that highlights not just market share, but the strategic implications of certification milestones, geographic footprints, and application-specific capabilities.
For corporate strategy, R&D leadership, procurement, and investment teams, the report serves as a decision-support tool. It helps identify where to prioritize supplier qualification, how to assess the commercial implications of tightening nanomaterial regulations, and which application pathways offer the most credible growth potential. It also provides a structured basis for evaluating partnership opportunities, capacity investments, and market-entry timing.
Cucurbituril Market
What the Full Analysis Delivers
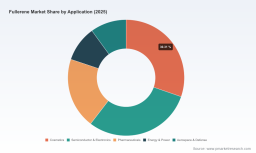
To support robust strategic planning, the complete report goes beyond headline figures and offers granular, segment-level intelligence. The full analysis includes detailed regional performance trends, type-specific valuation and growth patterns across C60, C70, C76, and other fullerene variants, and application-level demand trajectories spanning cosmetics, semiconductor and electronics, pharmaceuticals, energy and power, and aerospace and defense. These breakdowns are essential for understanding where value creation is concentrated and how growth diverges across end markets with different purity, scale, and regulatory profiles.
The report also incorporates competitive benchmarking, recent corporate developments such as Nano-C's ISO 9001:2015 certification achievement in May 2026, and a forward-looking assessment of supply-chain risk factors tied to graphite availability and export-control dynamics. By connecting these operational developments to broader market outcomes, the analysis equips decision-makers with a more durable basis for scenario planning and investment prioritization.
Why This Research Matters for 2026 Strategy
2026 is a year in which intuition alone will not suffice. Feedstock constraints, regulatory validation demands, and the migration of fullerene materials into higher-value applications are reshaping the commercial terrain at a pace that rewards organizations with disciplined market intelligence. The projected expansion toward 600.0 million USD by 2032 is significant, but the strategic question is not simply how large the market will become. It is who will capture disproportionate value within it, under what purity and supply conditions, and through which application pathways.
Accessing the full market research report provides the depth required to answer those questions with confidence. It delivers the segment-level breakdowns, competitive context, and supply-and-regulation dynamics that executives need to align product roadmaps, procurement strategies, and partnership decisions with where the market is actually headed. For teams evaluating capital allocation, supplier qualification, or market-entry timing, this research offers a structured, evidence-based foundation for the decisions that will shape performance through 2032 and beyond.
Fullerene Market
For detailed analysis of this topic, please visit the official page: Fullerene Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


