



PW Consulting: Ursodeoxycholic Acid Market to Reach $1.1B by 2032 with 10.2% CAGR

Navigating the Ursodeoxycholic Acid Drug Product Market: Strategic Intelligence for 2026 and Beyond
The global landscape for hepatology therapeutics is undergoing a period of significant recalibration, driven by evolving regulatory frameworks, patent expirations, and a growing prevalence of chronic liver conditions. At the center of this shift stands Ursodeoxycholic Acid (UDCA), a compound that has long maintained its position as a foundational therapy. For pharmaceutical executives, investors, and strategic planners, understanding the trajectory of this market is no longer optional; it is a critical component of portfolio optimization and competitive positioning. Our latest comprehensive market research report offers a granular examination of the UDCA drug product landscape, designed specifically to equip decision-makers with the actionable intelligence required to navigate the complexities of 2026 and the subsequent forecast period through 2032.
A Market on a Defined Growth Trajectory
The macroeconomic signals for the UDCA drug product market are unmistakable. Drawing on historical data spanning from 2020 through 2025, our analysis tracks a consistent upward arc in global revenue, measured in millions of US dollars. The baseline established in recent years reflects a compound annual growth rate that underscores sustained demand across multiple therapeutic areas. As we pivot into the forecast window of 2026 to 2032, the projection indicates a robust expansion that will reshape revenue pools and alter the calculus for market entry, capacity planning, and partnership strategies.
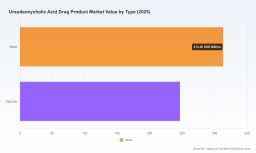
This growth is not merely a function of population expansion or generic substitution. It is being propelled by a confluence of factors: the chronic nature of primary biliary cholangitis, which demands long-term patient adherence and stable reimbursement pathways, and the ongoing utilization of UDCA as a first-line intervention under established FDA guidelines. Furthermore, the anticipated dominance of the generics segment, expected to command a substantial share of the market in 2026 following a wave of patent expirations, introduces a new dynamic of price pressure and volume-driven economics. Understanding how these forces interact requires more than top-line figures; it demands a dissection of the underlying structural drivers that our report meticulously maps out.
What Is Inside: A Blueprint for Operational and Strategic Execution
Our market research is structured to move beyond abstract trends and deliver concrete, operational utility. The report provides a multi-dimensional view of the UDCA drug product ecosystem, encompassing historical performance, forward-looking projections, and a detailed breakdown of the competitive and regulatory environment. Below is a preview of the core components that will enable your organization to translate market intelligence into decisive action.
- Historical and Forecast Revenue Analysis: A year-by-year examination of global revenue performance from 2020 through 2032, highlighting inflection points, growth acceleration, and the projected scale of the market as it approaches the end of the decade. Readers will gain clarity on the magnitude of the opportunity and the temporal windows most relevant to investment and capacity decisions.
- Segmentation Dynamics: A deep dive into the primary axes that define the market: dosage form, therapeutic application, and geographic distribution. The report evaluates how tablets and capsules compete for share, how indications such as gallstones and primary biliary cholangitis drive distinct demand profiles, and how regional markets are evolving in response to local regulatory, reimbursement, and supply chain conditions.
- Competitive Landscape and Corporate Profiles: An in-depth assessment of the leading integrated producers, generic suppliers, and specialized manufacturers shaping the market. Each profile includes geographic footprint, product positioning, and strategic implications for partnership, acquisition, or competitive defense.
- Recent Developments and Regulatory Intelligence: A curated timeline of pivotal events, including accelerated approvals for combination therapies targeting primary biliary cholangitis, new generic product launches, and updates to reimbursement and standard-of-care guidance. These developments are analyzed for their near-term and medium-term impact on market dynamics.
- Industry Context and Structural Forces: An examination of the reconcentration metrics that reveal the degree of market consolidation, alongside an assessment of supply chain considerations, raw material dynamics, and the reimbursement environment that underpins long-term patient access.
The Competitive Arena: Key Players and Strategic Positioning
The UDCA drug product market is characterized by a mix of established integrated manufacturers, global generic giants, and regional specialists. Our report provides detailed profiles of the companies that are actively shaping supply, pricing, and innovation within this space, offering a framework for evaluating competitive threats and partnership opportunities.
Among the most prominent participants is ICE Pharma, an Italy-based integrated producer that has built a significant presence in UDCA bile acid derivatives. With manufacturing capabilities spanning Europe, Latin America, Asia, and Oceania, and a distribution network that reaches over fifty countries, ICE Pharma exemplifies the globalized, vertically integrated model that can command respect in both branded and generic segments. For organizations evaluating supply chain resilience or seeking regional market access, ICE Pharma's footprint offers a case study in scale and geographic diversification.
Teva Pharmaceuticals, headquartered in Israel, represents a major force in the generic UDCA space, with an active supply of USP tablets and capsules. As one of the world's largest generic pharmaceutical companies, Teva's involvement signals both the maturity of the UDCA market and the ongoing relevance of high-volume, cost-competitive manufacturing. Similarly, Sun Pharmaceutical Industries Ltd, a leading Indian generic supplier, has reinforced its commitment to the market through recent product launches, underscoring the strategic importance of India as a production hub and the intensifying competition among generic manufacturers.
Daewoong Pharmaceutical, based in South Korea, adds another dimension to the competitive landscape as a supplier of UDCA drug products, including once-daily formulations. Formulation innovation and patient-centric dosing regimens are increasingly important differentiators, and Daewoong's presence highlights the potential for regional manufacturers to compete on convenience and adherence. In India, Mankind Pharma and Octavius Pharma Pvt. Ltd continue to be active manufacturers and suppliers of UDCA tablets, capsules, and API, reflecting the dense and competitive Indian manufacturing ecosystem that plays a critical role in global supply. Meanwhile, in the United States, Willow Birch Pharma and Lannett Company serve as active suppliers and manufacturers of generic UDCA products, catering to domestic demand and navigating the nuances of the US regulatory and reimbursement environment.
Ursodeoxycholic Acid Drug Product Market
Our report goes beyond company descriptions to analyze how these players interact within a market that, based on our concentration metrics, exhibits a moderate level of consolidation. With a focused analysis of market share distribution and the strategic implications of competitive density, decision-makers can better assess barriers to entry, the feasibility of niche positioning, and the potential for consolidation or partnership-driven growth.
Market Dynamics: Regulation, Reimbursement, and Supply Chain Forces
The structural underpinnings of the UDCA market are defined by a set of regulatory and reimbursement realities that create both stability and pressure. UDCA remains the standard first-line therapy for primary biliary cholangitis under FDA guidance, with no substantive changes reported through 2025. This continuity reinforces the compound's central role in treatment protocols and supports predictable demand over the long term. At the same time, the chronic nature of the disease drives sustained patient adherence, which in turn bolsters the case for consistent reimbursement coverage. For market participants, this dynamic translates into a durable revenue base, but also into heightened scrutiny of pricing, access, and the value proposition relative to emerging adjunct therapies.
On the supply side, the generics segment is anticipated to hold a significant majority share of the market in 2026, a shift driven by patent expirations on branded products and the resulting price pressure. This transition has profound implications for manufacturing strategy, margin expectations, and competitive differentiation. Companies that can optimize production efficiency, secure reliable API sourcing, and navigate regulatory compliance with agility will be best positioned to capture volume in a increasingly price-sensitive environment. Our report explores these supply chain and raw material dynamics in detail, offering insights into the operational levers that can determine success as the market tilts further toward generics.
Recent regulatory and commercial developments add further texture to the landscape. In 2024, the FDA granted accelerated approval for elafibranor for primary biliary cholangitis in combination with ursodeoxycholic acid, and shortly thereafter, accelerated approval for seladelpar in combination with ursodeoxycholic acid. These milestones, achieved by major pharmaceutical companies, signal a growing emphasis on combination and adjunct treatment paradigms for primary biliary cholangitis. While UDCA remains the foundational therapy, the emergence of combination approaches could reshape treatment pathways, create new co-marketing opportunities, and influence the competitive positioning of standalone UDCA products over time. Additionally, the recent launch of generic UDCA drug products by Sun Pharmaceutical Industries Ltd in late 2024 illustrates the ongoing pace of generic entry and the need for continuous monitoring of product availability, pricing shifts, and geographic rollout strategies.
Strategic Implications for 2026 Decision-Making
As organizations prepare for 2026, the UDCA drug product market presents a blend of opportunity and complexity that demands a disciplined strategic approach. The forecast period through 2032 suggests a market that will continue to expand materially, but the distribution of that growth across dosage forms, indications, and regions will not be uniform. Companies that rely on aggregate market figures alone risk missing the granular shifts that determine whether a product, a market entry, or a partnership will succeed or underperform.
Ursodeoxycholic Acid Market
For manufacturers, the anticipated dominance of the generics segment in 2026 underscores the importance of cost leadership, supply chain robustness, and regulatory agility. For branded and specialized players, the opportunity may lie in formulation differentiation, patient support programs, combination strategies, or targeted regional expansion where competitive density is lower. For investors and strategic advisors, the concentration metrics and competitive profiles provide a lens through which to evaluate market access, barriers to entry, and the potential for consolidation or vertical integration.
Reimbursement dynamics and the chronic disease context further emphasize the need for a long-term perspective. Patient adherence and sustained coverage create a relatively stable demand floor, but they also heighten the importance of demonstrating value, managing pricing expectations, and aligning with payer and provider priorities. The introduction of combination therapies and the evolving treatment landscape for primary biliary cholangitis add another layer of strategic consideration, as organizations must anticipate how new regimens may complement, compete with, or redefine the role of UDCA in standard care.
Why Comprehensive Intelligence Matters
The decisions that will shape your organization's position in the UDCA drug product market over the next several years depend on a clear, evidence-based understanding of the forces at play. Aggregate trends provide direction, but they do not replace the need for detailed segmentation, competitive profiling, regulatory tracking, and scenario analysis. Our full market research report delivers that depth, equipping stakeholders with the data and context required to make informed choices about capacity, product strategy, geographic focus, partnership structures, and competitive responses.
We invite you to access the complete report to explore the full scope of our analysis, including the specific regional and application-level insights, detailed company assessments, and forward-looking projections that will support your strategic planning for 2026 and beyond. In a market defined by both continuity and change, the organizations that thrive will be those that invest in the intelligence needed to act with precision, anticipate shifts before they become disruptive, and align their capabilities with the most promising avenues for growth.
For detailed analysis of this topic, please visit the official page: Ursodeoxycholic Acid Drug Product Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


