



PW Consulting: English Language Learning Market to Hit $344.8M by 2032, 6.98% CAGR from $215M in 2025

Strategic Intelligence for the ELT Sector: Why the 2026 Language Learning Market Report Is Essential for Executive Decision-Making
The English Language Learning market is undergoing a structural transformation that few organizations are equipped to navigate with confidence. Between historical fluctuations and compound growth trajectories, the sector has moved from fragmented experimentation to consolidated demand patterns. For corporate leaders, investors, and institutional strategists operating in 2026, surface-level market headlines are no longer sufficient. What matters is a disciplined reading of how technology adoption, regulatory shifts, learner behavior, and competitive positioning intersect to shape revenue pipelines, product roadmaps, and regional expansion strategies.
PW Consulting has prepared a comprehensive research study designed specifically for decision-makers who require actionable intelligence rather than generic market summaries. This article outlines the strategic architecture of that research, demonstrates how macro-level market dynamics inform 2026 planning cycles, and explains why the granular segmentation, competitive profiling, and scenario-based analysis contained in the full report are critical for organizations seeking durable advantage in a rapidly evolving sector.
The 2026 Market Context: Growth With Complexity
Over the past half-decade, the English Language Learning sector has progressed from a post-pandemic recovery phase into a more mature expansion cycle. The market reached an estimated 205.57 million USD in 2024, advanced to 215.0 million USD in 2025, and is projected to continue its upward path through the 2026-2032 forecast window. This trajectory reflects sustained demand across professional upskilling, academic preparation, migration-driven language acquisition, and enterprise training programs. Yet the headline trajectory alone masks the strategic tensions that matter most to executives.
A compound annual growth rate of 6.98 percent during the forecast period signals healthy expansion, but growth at this pace rarely distributes evenly across products, geographies, or buyer segments. The real strategic question for 2026 is not whether the market is growing, but where value is concentrating, which distribution channels are capturing disproportionate share, and how the mix between institutional procurement and individual self-directed spending is reshaping customer acquisition economics. Organizations that treat the market as monolithic risk misallocating capital toward channels or product formats that may be structurally disadvantaged in the next cycle.
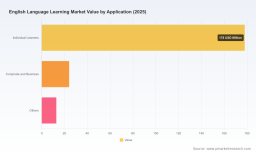
The full research study breaks down these dynamics with a level of segmentation precision that allows leadership teams to distinguish between broad sector tailwinds and specific commercial opportunities. Rather than relying on generalized growth narratives, the report maps how structural demand drivers interact with format preferences, regional purchasing environments, and application-type adoption patterns, giving strategists a practical framework for prioritizing investments and adjusting go-to-market assumptions.
What the Research Delivers: Operational Content for Decision-Makers
This study is constructed as a decision-support instrument, not an academic survey. Its architecture is designed to help executives, product leaders, and market-entry teams answer concrete questions about positioning, resource allocation, and competitive exposure. The report integrates both historical reconstruction and forward-looking scenario analysis so that readers can test strategic assumptions against a range of plausible market outcomes.
The core content areas include:
- A detailed market sizing and trajectory analysis that reconstructs past performance and extends the outlook across the full forecast horizon, enabling leaders to benchmark internal expectations against sector-wide momentum.
- A multi-dimensional segmentation framework that separates the market by region, product type, and end-user application, allowing teams to evaluate where demand is most structurally supported and where growth may be more volatile or contingent on external factors.
- A competitive landscape assessment that profiles major participants, examines their strategic orientations, and identifies how differing business models—digital-first platforms, blended academy models, assessment-driven offerings, and enterprise-focused programs—compete for the same learner pools.
- An analysis of market concentration and consolidation signals, helping stakeholders assess whether the sector is fragmenting toward niche specialization or consolidating around platforms that can combine content, technology, and distribution at scale.
- A regulatory and policy environment review that places recent institutional changes within the broader context of language education governance, student support frameworks, and multilingual service guidance, all of which can influence procurement behavior, compliance requirements, and program design assumptions.
In addition to these structural analyses, the report incorporates recent industry developments that directly affect planning assumptions. Signals ranging from federal administrative adjustments to regional program guidance are evaluated for their potential impact on institutional funding flows, learner demand patterns, and the operating environment for service providers. This contextual layer is essential for organizations that need to anticipate how policy recalibration may alter demand concentration or shift purchasing authority within education and enterprise channels.
The full document is organized to support rapid executive consumption as well as deeper cross-functional alignment. Strategists can use it to pressure-test market-entry theses, product leaders can use it to assess whether existing feature sets align with emerging buyer expectations, and finance teams can use the segmentation structure to refine revenue forecasts with more defensible assumptions about where growth is most likely to materialize.
Competitive Landscape: How Strategic Positioning Is Evolving
The English Language Learning market is contested by a diverse set of players whose strategic postures differ not only in scale but in underlying value propositions. The research evaluates the competitive environment through the lens of commercial model, distribution reach, learner engagement strategy, and institutional vs. individual orientation. This approach matters because competition in the sector is increasingly defined by how effectively companies integrate content quality, technology-enabled personalization, assessment infrastructure, and brand trust across distinct buyer segments.
Several large, established organizations anchor the market with multi-layered offerings that span curriculum, assessment, and proficiency certification. Pearson, based in London, competes through a broad suite of English Language Teaching courseware, assessment services, and proficiency testing solutions that address institutions, governments, and individual learners. Its positioning reflects an orientation toward structured institutional procurement and credibility-driven evaluation tools, making it a relevant benchmark for organizations assessing how assessment and credentialing capabilities influence purchasing decisions.
English Language Learning Market
International immersion and cultural-exchange-focused operators occupy a different strategic space. EF Education First, headquartered in Baar, Switzerland, has built its identity around immersive English programs and cross-cultural learning experiences. Berlitz, operating from the United States, emphasizes immersive instruction built around its signature teaching method, serving individuals, businesses, and government clients. These companies illustrate how experiential and instructor-mediated models continue to compete against purely digital approaches, particularly in segments where outcomes depend heavily on speaking confidence, cultural familiarity, or enterprise credibility.
The digital learning frontier is represented by a cluster of platform-driven companies with distinct user acquisition and engagement strategies. Duolingo, based in Pittsburgh, has popularized mobile and web-based bite-sized lessons that lower the barrier to habitual practice for English and other languages. Rosetta Stone, headquartered in Harrisonburg, Virginia, focuses on immersive computer-assisted learning with speech recognition capabilities that aim to strengthen pronunciation and listening proficiency. Babbel, based in Germany, pursues online subscription-based lessons structured around scientific learning methods for English. Wall Street English, with its base in Italy, differentiates through guaranteed-results course models supported by coaches and teachers, blending digital convenience with human accountability.
In parallel, network-based and infrastructure-oriented providers shape the operational environment for institutions and training centers. inlingua International, headquartered in Switzerland, operates through blended and online language training centers, while Sanako Corporation, based in Finland, focuses on language lab software and hardware that support classroom pronunciation and speaking-skill development. These offerings matter because they influence the technical backbone available to institutions seeking to standardize instruction, track learner progress, and scale language practice in structured settings.
Taken together, these competitive profiles reveal a market in which advantage is increasingly tied to the ability to combine scalable technology with credible outcomes signaling. The research explores how different players are attempting to capture value across the Learner journey—acquisition, practice, assessment, certification, and institutional adoption—and where overlaps in target segments create pressure on pricing, retention, and differentiation. The complete report provides deeper comparisons of business-model resilience, channel dependencies, and the strategic implications of recent product and market developments, without reducing the analysis to simple market-share statements.
Why This Report Matters for 2026 Strategy
Strategic decisions made in 2026 will be judged not by whether they aligned with last year’s assumptions, but by whether they anticipated how the market is reorganizing itself around format preferences, buyer motivation, and regulatory reality. A growth environment of this nature rewards organizations that can distinguish durable demand from temporary hype, and that can identify which customer segments are expanding their willingness to pay for structured learning, assessment, or enterprise-language solutions.
The report is designed to support that kind of judgment. It enables leadership teams to evaluate whether current expansion plans reflect genuine segment traction or simply broad sector optimism. It helps product and operations leaders assess whether their offerings are aligned with the channels and application types that are capturing the most sustainable demand. It also provides investors and corporate strategy teams with a structured way to think about concentration risk, competitive response patterns, and the likelihood that certain subsegments may consolidate faster than others.
Equally important, the research places recent policy and institutional developments in context so that executives can incorporate regulatory uncertainty into scenario planning rather than treating it as an external distraction. Shifts in federal administrative structures, changes in language-access guidance, and state-level adjustments to English learner program frameworks can all influence demand visibility, procurement timelines, and program-design constraints. Organizations that integrate these variables into strategic planning are better positioned to manage risk and identify emerging opportunities before competitors do.
Online Language Learning Market
The full study goes further than the overview presented here. It supplies the segmentation detail, company-level profiling, and forward-looking analysis needed to convert market awareness into concrete action. For teams that require defensible assumptions about where growth is concentrated, which business models are most exposed, and how the competitive field is likely to evolve, the complete research package provides the depth necessary to support board-level discussion, investment committee review, and cross-functional planning cycles.
Conclusion: Moving From Market Awareness to Strategic Precision
The English Language Learning market in 2026 is not simply expanding; it is reconfiguring. Demand continues to grow, but the strategic value of that growth depends on how precisely organizations can interpret segmentation signals, competitive behavior, and policy-driven changes in the operating environment. PW Consulting’s English Language Learning Market research is built to help executives make that interpretation with confidence, offering a structured, evidence-based foundation for decisions that will shape growth, positioning, and resilience over the coming years.
Organizations that want to move beyond high-level market narratives and into the detail that supports concrete strategy should review the complete report. The full analysis provides the segmentation clarity, competitor context, and forward-looking assessment needed to turn market movement into informed strategic action.
For detailed analysis of this topic, please visit the official page: English Language Learning Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


