



PW Consulting: Vacuum Pump Brake Market to Hit $344.8M by 2032, 5.8% CAGR

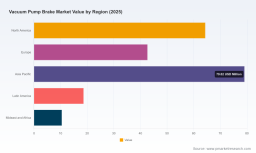
Navigating the 2026 Vacuum Pump Brake Market: Strategic Intelligence for OEMs and Tier 1 Suppliers
The global automotive braking ecosystem is undergoing a structural reconfiguration. With hydraulic and pneumatic architectures giving way to electrified brake boosters, vacuum pump brake technologies are entering a decisive growth phase. For procurement directors, R&D leads, and competitive intelligence teams, understanding this trajectory is no longer optional. It is a prerequisite for capital allocation, supply chain resilience, and product roadmap alignment. The 2026 editions of our Vacuum Pump Brake Market study are designed to translate macroeconomic momentum into actionable operational guidance.
Over the historical window from 2020 through 2025, the sector has demonstrated consistent upward traction, reflecting both fleet modernization and the incremental electrification of brake assistance systems. That momentum carries directly into the forecast horizon, establishing a multi-year growth corridor that will shape sourcing strategies, capacity planning, and partnership models. The strategic question facing executives today is not whether to engage with this shift, but how to position portfolios, negotiate with manufacturers, and mitigate regulatory exposure while the market re-rates itself around electrification, consolidation, and compliance.
This article serves as an advance briefing on the scope, analytical framework, and competitive intelligence embedded in our latest Vacuum Pump Brake Market report. It outlines the structural forces reshaping demand, introduces the competitive landscape and recent industry developments, and clarifies the practical decision-support tools available to subscribers. Core valuation splits, detailed matrix breakdowns, and granular regional matrices are intentionally reserved for the full dataset to preserve the analytical integrity of the deliverable.
Structure and Scope of the Research Deliverable
A high-quality industry assessment must bridge the gap between high-level market indicators and the granular, operation-ready intelligence that engineering and procurement teams actually use. Our Vacuum Pump Brake Market study is built on that premise. Rather than delivering a single macro figure, the report distributes context across a structured architecture designed to support segmentation, scenario planning, source evaluation, and risk mapping.
The analytical backbone rests on a rigorously tracked historical series paired with a forward-looking projection window. Trailing data captures the maturation curve of vacuum-assisted braking installations, while the forecast horizon extends through the next several model lifecycle cycles, allowing strategists to test capacity decisions, sourcing flexibility, and portfolio pivots against realistic adoption pathways. The revenue framing is standardized in USD millions, ensuring comparability across geographies and product categories while maintaining a consistent valuation baseline for executive review.
Beyond the headline growth trajectory, the report dissects the market through engineered segmentation lenses that reflect how vehicle manufacturers and suppliers actually think about product design, sourcing, and performance differentiation. The type dimension distinguishes between mechanical and electric architectures, capturing the functional divergence that increasingly drives specification decisions. The application lens separates passenger vehicles from commercial vehicles, a split that matters because demand elasticity, duty cycles, warranty exposure, and procurement cycles differ substantially across those segments. Regional breakdowns further contextualize where demand is concentrating and where nearshoring, tariff exposure, or local content requirements may alter sourcing logic.
Each segment view is integrated with cross-referencing modules so that readers can trace how architectural preference, vehicle class, and geographic rollout interact. This is essential for teams evaluating supplier fit, component compatibility, and aftermarket service footprints. Rather than presenting isolated slices, the study constructs a connective analytical grid that supports multi-variable decision-making.
Competitive Landscape: Who Shapes the Vacuum Pump Brake Ecosystem
Market positioning in this space is defined less by aggregate size than by specialization, certification readiness, OEM relationships, and speed of adaptation to electrification mandates. Several manufacturers have differentiated themselves through targeted product lines, volume reliability, and long-term integration with vehicle platforms. Understanding that competitive fabric is central to evaluating both threat and opportunity.
In South Korea, a cluster of specialist manufacturers has built durable positions around electric and mechanical vacuum pump production for brake systems. One player, headquartered in Incheon, focuses on electric motor-driven vacuum pumps designed for brake booster assistance in electric vehicles. Its production cadence for one-ton class models and multi-decade track record supplying Korean EV OEMs signal a mature, volume-oriented manufacturing base. Another Korean manufacturer, based in Gyeongju, produces parallel-electric and mechanical vacuum pump series tailored for passenger cars and hybrid applications. Its emphasis on BLDC and DC motor variants underscores the ongoing tension between efficiency optimization and cost discipline in mainstream vehicle architectures. A third South Korean manufacturer has become a notable supplier within the domestic electric vehicle ecosystem, producing variants scaled for sedans, SUVs, RVs, and light commercial bodies. Its integration into major OEM brake system assemblies and established quality certifications illustrate how regional specialization can translate into embedded platform placement.
Beyond East Asia, North American and European names maintain relevance through different value propositions. A United States-based supplier with original equipment manufacturing capability focuses on plug-and-play vacuum pump replacements for premium and performance brands, positioning around compatibility, warranty assurance, and service-channel reliability. Meanwhile, European innovation activity points toward electrification-driven brake system upgrades that align with emissions reduction objectives, highlighting how traditional suppliers are adapting product lines to meet shifting regulatory and performance expectations.
Vacuum Pump Brake Market
On the broader manufacturing side, Chinese producers continue to expand their vacuum pump and booster system capabilities. Several facilities concentrate on commercial vehicle brake power boosters and vacuum pump assemblies, reflecting the commercial fleet segment’s ongoing need for robust, cost-efficient braking support hardware. At the product level, CE-certified brake booster units and vacuum booster series for Japanese vehicle platforms indicate that export-oriented production is increasingly structured around compliance, interchangeability, and model-specific fitment.
What unites these competitors is not uniform scale, but differentiated positioning. Some compete on volume reliability and OEM integration. Others compete on certification readiness, part interchangeability, or electrification-specific motor architectures. A few compete primarily on commercial vehicle durability and cost. For buyers and strategists, the competitive map is less about identifying a single dominant leader and more about recognizing where switching costs, technical lock-in, and supply continuity may shape sourcing choices.
Recent Industry Developments Redefining the Curve
The vacuum pump brake market does not evolve in a vacuum. Supply chains, safety exposure, and product launches are intersecting in ways that alter both near-term procurement and long-term engineering priorities. Several events in the recent cycle illustrate why this sector deserves heightened strategic attention.
Product launch activity continues to reflect the dual pressure of electrification and cost efficiency. Recent introductions of electric vacuum pump series for passenger vehicles emphasize consistent vacuum delivery and manufacturing efficiency, signaling that suppliers are trying to reconcile performance stability with margin discipline. At the same time, European language around new electric vacuum pump introductions has explicitly connected brake system electrification with emissions reduction, reinforcing the regulatory tailwind behind electric booster technology.
Exhibition and trade activity also indicate that the supply base remains active and increasingly export-oriented. Recent automotive maintenance and parts exhibitions in China featured multiple brake vacuum pump exhibitors showcasing electric fuel and brake pump systems. For sourcing teams, these events are not merely marketing showcases; they are practical indicators of supplier readiness, product breadth, and regional manufacturing momentum.
At the same time, the market is not immune to quality and liability exposure. A class-action filing in U.S. federal court has alleged that a major automaker failed to fully warn owners about a brake vacuum pump defect capable of causing sudden loss of power assist in certain models. Whether or not a given company is directly involved, events of this nature matter to the broader market because they reshape warranty assumptions, recall management practices, parts traceability expectations, and the reputational calculus that OEMs apply when qualifying suppliers. They also elevate the value of supplier quality systems, documentation consistency, and testing rigor as strategic differentiators rather than administrative checkboxes.
Strategic Lens: What This Means for 2026 Decision-Making
For automotive executives, the practical takeaway is that vacuum pump brake technology is moving from a mature accessory category into a more strategically sensitive component of the vehicle safety and electrification architecture. The implications span sourcing, product planning, and risk management.
Vacuum Pumps Market
First, the pace of electrification is reshaping specification logic. Mechanical and electric vacuum pump architectures serve different vehicle strategies, and the choice between them increasingly affects energy efficiency, system integration complexity, and long-term service expectations. Teams evaluating supplier portfolios need to weigh not only current part fitment, but also how rapidly each manufacturer can pivot its motor architecture, certification readiness, and production line flexibility as platform requirements evolve.
Second, geographic demand distribution creates sourcing trade-offs. Where demand is building, local content considerations, logistics resilience, and tariff exposure may influence whether buyers prioritize regional suppliers, export-oriented manufacturers, or multi-sourced arrangements. The competitive landscape includes both entrenched OEM-integrated players and broader manufacturing ecosystems capable of serving multiple vehicle classes and export markets. Choosing among them requires clarity on volume stability, part interchangeability, and compliance posture.
Third, quality and liability dynamics are now part of supplier evaluation rather than downstream incident management. Recent litigation language around brake vacuum pump defects underscores how quickly perceived reliability gaps can translate into consumer risk exposure and regulatory attention. For procurement and quality teams, that means the value of robust process control, documented testing, and recall readiness is rising in the hierarchy of supplier selection criteria.
The full report translates these themes into a structured set of decision frameworks. It provides a consistent historical baseline and forecast series so readers can test growth assumptions, align capacity planning, and map demand concentration. It organizes the segmentation views that matter for engineering and sourcing teams without forcing them into simplified averages. It profiles competitors with enough operational context to support like-for-like evaluation. And it embeds recent developments within the broader demand, regulation, and quality narrative so that strategic teams can anticipate disruption rather than react to it.
Why This Study Matters for 2026
As the market expands through the forecast horizon, the difference between reactive sourcing and proactive portfolio strategy will increasingly come down to information quality and analytical discipline. Vacuum pump brake demand will not grow uniformly across vehicle classes, architectures, or regions. The companies that gain advantage will be those that understand where concentration is forming, which suppliers have credible scale or specialization, and how regulatory and safety developments may alter both specification and sourcing behavior.
The full Vacuum Pump Brake Market report is built for that environment. It equips teams with a coherent narrative, a structured segmentation architecture, competitive profiles, and forward-looking scenario context. Readers who engage with the complete dataset will be better positioned to evaluate supplier resilience, time product transitions, and allocate resources with confidence in a market that is simultaneously maturing and electrifying.
For detailed analysis of this topic, please visit the official page: Vacuum Pump Brake Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


