



PW Consulting: FPGA Market Hits $11.73B in 2025, Projected 10.5% CAGR to $23.6B by 2032

Navigating the FPGA Inflection Point: Strategic Intelligence for Enterprise Decision-Making in 2026 and Beyond
The global semiconductor landscape is undergoing a profound structural transformation, and within it, the Field-Programmable Gate Array (FPGA) market stands at a critical inflection point. For enterprise technology leaders, procurement strategists, and innovation officers, FPGAs have evolved from niche reconfigurable components into foundational enablers of adaptive compute across artificial intelligence, edge processing, telecommunications infrastructure, and high-reliability defense systems. Yet the sheer velocity of technological advancement, coupled with shifting regulatory frameworks and supply chain realignments, has rendered legacy forecasting models insufficient. This gap between market volatility and the demand for actionable intelligence is precisely why our newly published FPGA Market Research Report has been commissioned and structured. Designed as a strategic decision-support instrument rather than a static data repository, this study maps the trajectory of the FPGA ecosystem from 2026 through 2032, equipping organizations with the contextual depth and analytical rigor required to allocate capital, manage supply exposure, and position product portfolios ahead of competitive cycles.
The Strategic Imperative: Why 2026 Demands a New Analytical Lens
Market history provides the necessary baseline for forward-looking strategy, but 2026 introduces variables that fundamentally alter the planning horizon. The sector’s measured compound annual growth rate of 10.5 percent reflects more than aggregate expansion; it signals a reallocation of investment toward architectures that prioritize flexibility, power efficiency, and cryptographic resilience. Over the past five years, the industry has consistently scaled its value creation, with revenue climbing steadily to an estimated 11.73 billion United States dollars in the 2025 base year and projected to cross the 12.73 billion mark as 2026 takes shape. Looking further downstream, the forecast horizon extends to 23.6 billion dollars by 2032, indicating that the coming years will not merely continue historical momentum but rather accelerate it as system architects embed hardware programmability deeper into AI inference pipelines, advanced communication stacks, and mission-critical platforms.
However, macroeconomic growth curves alone do not dictate enterprise strategy. The strategic value of this research lies in its refusal to treat the market as a monolith. Regional dynamics, product architecture selection, and application-specific adoption curves diverge significantly, and companies that apply uniform assumptions across their operations risk misallocating engineering resources or underestimating procurement constraints. By deliberately synthesizing historical performance data with forward-looking scenario modeling, our report enables decision-makers to anticipate inflection zones where supply constraints, design complexity, or competitive repositioning will create asymmetric advantages. The objective is not to overwhelm stakeholders with fragmented metrics but to distill complex market behaviors into strategic action pathways that can be operationalized within existing product roadmaps, procurement frameworks, and partnership strategies.
Field-Programmable Gate Array (FPGA) Market
Market Architecture and Forward Trajectory: Decoding the Growth Curve
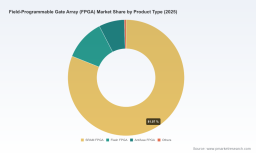
The structural composition of the FPGA market reveals how demand segments are evolving and where enterprise exposure is most concentrated. Product architecture remains a defining variable in both procurement strategy and engineering roadmapping. The market environment continues to be anchored by established platforms that dominate deployment volume, while alternative architecture families serve specialized reliability, security, or power-efficiency niches. Each architecture type carries distinct implications for design lifecycle management, software ecosystem compatibility, and geopolitical supply exposure. Organizations evaluating vendor portfolios must therefore assess not only performance benchmarks but also the long-term viability of toolchains, legacy migration pathways, and the strategic alignment of each architecture with their projected deployment environments.
Application segmentation further underscores the broadening scope of FPGA utilization. Telecommunications, data center infrastructure, consumer electronics, automotive systems, industrial automation, and military or aerospace programs each impose unique performance, certification, and lifecycle requirements. As processing workloads migrate toward disaggregated architectures and domain-specific acceleration, the programmable fabric has become a strategic layer for bridging fixed silicon limitations with evolving algorithmic demands. The interplay between these verticals is increasingly bidirectional: breakthroughs in data center acceleration architectures frequently inform edge deployment optimizations, while stringent environmental and reliability standards in industrial or aerospace sectors drive innovations that eventually cascade into broader commercial applications.
Concentration dynamics add a critical dimension to competitive and procurement strategy. The market remains highly consolidated, with the top three players collectively commanding three-quarters of total industry revenue and the top five reaching approximately eighty-five percent. High concentration implies that partnership negotiations, licensing terms, roadmap alignment, and supply allocation privileges are disproportionately influenced by interactions with a small cohort of dominant suppliers. For enterprises without direct leverage over these ecosystems, the strategic response involves diversified sourcing architectures, co-development arrangements, and early engagement with emerging platform providers that may offer alternative value propositions in targeted application domains. Long-term planning therefore requires a nuanced understanding of which suppliers will dominate next-generation architectural transitions and which will retreat into niche segments as consolidation accelerates.
Competitive Dynamics and Recent Strategic Moves
The competitive landscape is defined by both established scale players and specialized innovators pursuing differentiated architecture strategies. AMD, operating through its Xilinx lineage, continues to anchor high-performance adaptive compute with its Versal architecture and UltraScale+ platforms, targeting AI-adjacent workloads, data center acceleration, and embedded compute scenarios. Intel’s Altera division has reinforced its commitment to the edge and communications segments through Agilex series platforms optimized for high-speed throughput and compact embedded deployments. These two ecosystem behemoths exert structural influence on toolchain standardization, strategic pricing expectations, and downstream design migration pathways, making their product announcements highly consequential for enterprise planning.
Smaller but increasingly influential players are carving out defensible positions by focusing on power efficiency, security hardening, and domain-specific reliability. Lattice Semiconductor has expanded its footprint in low-power and mid-range applications while embedding cryptographic agility into its FPGA families, a move that directly addresses emerging security guidance from government and industrial regulators. Microchip Technology maintains a strong positioning in radiation-hardened and high-assurance environments, supporting defense and space architectures that demand both electromagnetic compatibility and resistance to side-channel vulnerabilities. Efinix continues to advance compact, low-power architectures targeting edge AI and real-time processing workloads, while QuickLogic emphasizes antifuse and radiation-tolerant platforms alongside embedded FPGA intellectual property for specialized defense and industrial deployments. Each of these companies is actively shaping the market through targeted product launches, strategic contracting, and roadmap commitments that redefine what programmable silicon can deliver in constrained or highly regulated environments.
The speed of recent corporate activity illustrates how rapidly the competitive frontier is moving. Early in 2026, Intel unveiled its Agilex 3 family, emphasizing optimized power-performance-size tradeoffs for embedded and edge deployments, with software support cycles and production timelines already established. Later that year, AMD announced next-generation Kintex UltraScale+ devices with substantially expanded memory bandwidth and extended availability horizons, signaling a deliberate push toward long-lifecycle industrial and embedded applications. These announcements were preceded by a series of strategic milestones throughout 2025, including Lattice’s introduction of its post-quantum cryptography-ready FPGA family and QuickLogic’s award of a significant defense contract to advance radiation-hardened technology under trusted microelectronics programs. Together, these developments demonstrate that competition is no longer limited to raw logic density or clock speed; it increasingly centers on cryptographic readiness, supply assurance, software maturity, and alignment with government or industry assurance frameworks.
Structural Shifts Shaping Industry Dynamics
Market growth does not occur in a vacuum. The FPGA sector is simultaneously navigating regulatory evolution, material supply volatility, and assurance-driven procurement mandates that will alter sourcing strategies and design methodologies. In early 2025, government defense authorities released updated security guidance specifically directed at FPGA deployments, emphasizing cryptographic key management, hardware security module compliance, and integrated cryptographic libraries within design flows. Such guidance transforms security from an optional hardening step into a foundational design requirement, with direct implications for vendor evaluation, architecture selection, and lifecycle maintenance. A subsequent revision of best practice documentation further codifies expectations around authentication, auditability, and reproducible build environments, reinforcing the need for supply chain traceability and design process discipline.
Geopolitical and material constraints are introducing parallel pressures. Semiconductor manufacturing dependencies on concentrated raw material sources have become a strategy-informing reality. A substantial share of global silicon production and the overwhelming majority of certain low-purity gallium requirements originate from a single geographic region, and export control actions implemented during late 2024 and early 2025 triggered significant price escalation for gallium-dependent supply chains. While not every architecture depends equally on constrained inputs, enterprises with diversified component sourcing needs or long-duration program commitments must incorporate material availability risk into supplier qualification criteria and inventory planning. This is particularly relevant for platforms pursuing extended availability windows, where procurement continuity across multiple product generations becomes a strategic differentiator.
Defense and space program dynamics are also accelerating specialized FPGA development. The progression into advanced phases of radiation-hardened research contracts signals sustained institutional commitment to securing domestically assured microelectronics for current and future mission architectures. As these programs mature, the resulting technology transfer pathways will influence commercial-grade reliability expectations, testing methodologies, and architectural feature sets, creating downstream benefits that may eventually diffuse into broader industrial deployments. For enterprises operating in or adjacent to regulated environments, tracking the intersection of assurance mandates, material constraints, and architectural innovation is essential to maintaining procurement resilience and avoiding unexpected compliance bottlenecks.
Inside the Report: What Decision-Makers Will Gain
Our research methodology was designed to convert market complexity into executable strategy. Rather than presenting isolated data tables or retrospective summaries, the report is structured around decision-centric analysis that connects market sizing, segmentation behavior, competitive positioning, and environmental dynamics into a coherent strategic framework. Decision-makers will find detailed profiling of core suppliers, including their architectural emphasis, target application domains, recent product milestones, and strategic posture relative to market concentration. This enables procurement teams, corporate strategists, and engineering leadership to evaluate supplier roadmaps against internal deployment timelines, compliance requirements, and long-term availability objectives.
The segmentation analysis is organized to illuminate growth distribution across regions, product architectures, and end-use applications without obscuring the underlying structural drivers. Regional dynamics are examined through the lens of infrastructure investment cycles, adoption maturity, and supply chain proximity, while application-based analysis focuses on workload intensity, certification requirements, and the rate at which programmable acceleration is displacing or complementing alternative silicon solutions. Combined with historical tracking from 2020 through 2025 and a forecast window extending to 2032, these layers allow organizations to calibrate investment timing, prioritize internal capability development, and model multiple adoption scenarios under differing supply or regulatory conditions.
A substantial portion of the report is devoted to operationalizing intelligence. Readers will encounter practical frameworks for evaluating design-tool compatibility, assessing post-quantum readiness, anticipating material-driven cost volatility, and structuring supplier engagement strategies in a highly concentrated market. Regulatory developments, certification expectations, and government-backed research activities are integrated directly into the analysis of market dynamics rather than treated as peripheral commentary, ensuring that compliance and assurance considerations are addressed as strategic variables rather than administrative afterthoughts. By aligning market data with execution-oriented guidance, the study functions as a planning reference that can be applied across capital allocation, sourcing strategy, engineering roadmapping, and partnership development.
Programmable Logic Controller (PLC) Market
Why Act Now: Aligning Intelligence with 2026 Decision Cycles
The window for proactive positioning is narrowing. As product portfolios evolve, toolchain ecosystems mature, and assurance requirements become more explicitly codified, organizations that defer strategic assessment risk finding themselves locked into architectures or supplier relationships misaligned with the next growth phase. The FPGA market’s trajectory suggests that programmable acceleration will remain embedded in the core infrastructure of emerging computing workloads, making early intelligence-gathering and supplier alignment a durable competitive advantage rather than a temporary tactical exercise.
This report is engineered to support that advantage. It provides the contextual map, the competitive intelligence, and the structural analysis necessary to turn market signals into disciplined decision-making. However, the full depth of segmentation behavior, detailed supplier positioning, regional nuance, and scenario-based growth pathways is preserved within the complete research deliverable, where interactive analysis, extended vendor profiling, and decision frameworks are available for teams seeking to operationalize the findings directly within their planning workflows. For executives evaluating 2026 capital deployment, supply strategy, product roadmap alignment, or partnership engagement, the comprehensive report offers the intelligence foundation required to act with precision in a market that rewards foresight.
For detailed analysis of this topic, please visit the official page: Field-Programmable Gate Array (FPGA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


