



PW Consulting: Blockchain Finance Market to Hit $126.88B by 2032, Growing at 26.94% CAGR

Blockchain Finance Market: Strategic Intelligence for the 2026 Enterprise
The convergence of traditional finance and distributed ledger technology has crossed a critical threshold. What began as experimental pilots and niche cryptocurrency transactions has evolved into a structured financial infrastructure supporting regulated assets, institutional settlements, and enterprise-grade tokenization. For corporate strategists, treasury leaders, and investors navigating the 2026 landscape, understanding the trajectory of the blockchain finance market is no longer optional. It is a prerequisite for capital allocation, risk management, and competitive positioning.
PW Consulting's latest comprehensive market research delivers the analytical rigor required to make informed decisions in this rapidly maturing sector. This report synthesizes historical performance, forward-looking projections, structural segmentation, and competitive intelligence into a single strategic framework. Below, we outline the market's current trajectory, the operational realities shaping deployment, and the regulatory architecture that will define execution over the next several years.
Macro Trajectory and the Investment Horizon
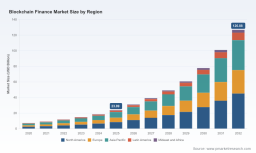
The blockchain finance market has demonstrated sustained expansion across the historical evaluation window, accelerating from foundational levels in the early 2020s to a materially larger operational footprint by 2025. Our tracking of revenue generation across the sector shows a consistent upward curve, with the market surpassing multiple inflection points as institutional participation deepened and tokenized asset infrastructure matured.
Looking ahead through the 2026–2032 forecast horizon, the market is projected to follow a steep growth trajectory, reflecting compounding adoption across payment networks, capital market tokenization, and decentralized financial infrastructure. The compound annual growth rate encoded in our baseline forecast underscores the velocity at which blockchain-native financial services are scaling relative to conventional analogues. This is not a speculative curve. It is a projection anchored in adoption patterns, regulatory clarity, and the structural migration of financial workflows onto distributed platforms.
For enterprise decision-makers, this trajectory carries two immediate implications. First, the window for establishing competitive presence in high-growth segments is narrowing as infrastructure providers consolidate market share. Second, the revenue potential embedded across transaction rails, asset management, and cross-border settlement warrants serious evaluation against internal digital transformation roadmaps and liquidity strategy. Organizations that map their capabilities to the segments experiencing the strongest tailwinds will be better positioned to capture disproportionate share as the market expands toward the decade's end.
Structural Segmentation and Operational Realities
Blockchain finance does not grow as a monolith. Deployment patterns, transaction volumes, and protocol preferences vary significantly across use cases, geographies, and technical architectures. Our report dissects these structural layers to help leaders isolate the opportunities most relevant to their strategic mandate.
Transaction Types and Capital Flows
Payment and settlement activity continues to dominate transaction volume, with peer-to-peer transfers and cross-border payment solutions capturing substantial portions of market activity. Cryptocurrency lending and supply chain finance represent adjacent but structurally distinct categories, each requiring specialized risk frameworks, counterparty diligence, and regulatory compliance postures. The distribution of transaction types reflects where blockchain delivers the clearest operational advantages: speed of settlement, reduced intermediary friction, and programmable financial logic.
Protocol Ecosystems and Infrastructure Choices
The protocol landscape reveals a clear hierarchy of adoption. Bitcoin remains the most extensively utilized network by transaction volume within the broader market, while Ethereum continues to anchor a significant portion of tokenized asset activity and decentralized financial applications. Enterprise-oriented frameworks, including Hyperledger and Ripple, serve specialized institutional use cases where permissioned structures, interoperability requirements, and regulatory alignment take precedence over open public-network deployment. Understanding the protocol mix is essential for technology procurement, risk assessment, and long-term infrastructure planning.
Application Domains and Enterprise Deployment
Digital asset management stands as the largest application category, reflecting the institutional demand for custody, portfolio infrastructure, and asset servicing across both native digital assets and tokenized representations of traditional instruments. Trade finance and digital identity solutions constitute meaningful secondary pillars, each addressing structural inefficiencies in legacy processes. The breadth of application adoption signals that blockchain finance is no longer confined to speculative trading environments. It is being embedded into core financial operations where transparency, auditability, and settlement certainty carry measurable commercial value.
Geographic Distribution and Regional Dynamics
Market activity spans multiple regions, with mature financial centers in North America and Europe maintaining substantial share alongside rapidly expanding activity across Asia Pacific. Emerging regions, including Latin America and the Middle East and Africa, represent smaller but strategically important footholds where blockchain-based financial services address specific gaps in legacy infrastructure, cross-border liquidity, and financial inclusion. Regional divergence in regulatory posture, banking integration, and technology adoption creates distinct entry strategies for organizations evaluating geographic expansion.
Competitive Landscape: Positioning Among Core Players
The competitive environment in blockchain finance is defined by a blend of incumbent financial institutions extending into digital infrastructure, technology-native platforms building capital market utilities, and payment networks scaling institutional settlement capabilities. Our report profiles the dominant participants shaping the market's architecture and outlines the strategic moves that are redefining competitive boundaries.
Societe Generale-FORGE has established a focused presence in regulated digital asset issuance, leveraging public blockchain networks for the deployment of stablecoin instruments backed by institutional custody arrangements. Their approach illustrates how traditional banking entities are bridging balance-sheet credibility with blockchain execution layers, a model that carries relevance for organizations evaluating partnership structures and regulated digital currency infrastructure.
Figure Technology Solutions operates as a blockchain-native capital marketplace designed for the origination, funding, and trading of tokenized assets and real-world assets. By constructing an end-to-end marketplace around asset tokenization, the company addresses a structural need for liquidity, distribution, and secondary market functionality that traditional infrastructure has struggled to deliver at scale. Their trajectory reflects the broader institutional push toward asset digitization as a capital markets modernization strategy.
DeFi Technologies bridges traditional capital markets and decentralized finance through financial technology platforms that integrate exchange-traded product structures and treasury solutions. Their positioning highlights a growing intersection where institutional investors seek regulated exposure to digital asset ecosystems without abandoning familiar investment wrappers. This convergence plays an important role in broadening access and establishing institutional-grade entry points into decentralized financial markets.
Ripple continues to anchor its strategy around cross-border payment networks and institutional banking solutions built on its underlying ledger infrastructure. The company's emphasis on settlement efficiency and institutional interoperability positions it as a key participant in the enterprise payment and liquidity management segment, where transaction speed and counterparty trust remain decisive factors.
Recent developments among these and adjacent market participants reinforce the pace of structural change. The launch of regulated stablecoin instruments on public blockchains with institutional reserve custodians, the authorization of major post-trade infrastructure providers to offer tokenization services, and the emergence of public companies natively issuing equity instruments on blockchain all point toward the normalization of digital asset workflows within regulated financial ecosystems. These milestones are not isolated experimentations. They represent compounding steps toward a reconfigured financial infrastructure.
Regulatory Architecture and Market Dynamics
Regulatory evolution is the single most powerful force shaping blockchain finance deployment in 2026. For years, market participants navigated fragmented guidance and jurisdictional uncertainty. That environment is now being replaced by defined frameworks that establish boundaries for stablecoin issuance, securities classification, and crypto-asset service provision.
In the United States, the establishment of a federal regulatory framework for stablecoins marked a foundational shift, providing clearer operating parameters for issuers and users of regulated digital currency instruments. Subsequent regulatory clarifications addressing the application of federal securities laws to crypto assets and transactions have further reduced ambiguity for institutional participants seeking to structure compliant offerings. These developments do not eliminate risk, but they convert an environment of uncertainty into one where compliance strategy can be designed with greater precision.
Across the Atlantic, the Markets in Crypto-Assets regulation has entered its full application phase, representing the first comprehensive regulatory framework for crypto-assets at scale. Its technical standards and service provider requirements create a structured operating environment that influences not only European market participants but also global organizations seeking to align their product design and compliance infrastructure with internationally recognized standards. The Bank for International Settlements has recognized this framework's significance, reinforcing its role as a reference point for cross-border regulatory coordination.
Blockchain Finance Market
These regulatory developments carry direct operational consequences. Organizations entering blockchain finance markets must now account for licensing pathways, reserve and custody requirements, disclosure obligations, and jurisdictional variance in treatment of digital assets. The market's growth trajectory will increasingly favor participants that integrate regulatory foresight into product design rather than treating compliance as a downstream constraint. Strategic advantage will accrue to those who can align innovation with demonstrable regulatory legitimacy.
Strategic Implications for 2026 Decision-Making
The data and dynamics captured in this research translate into several actionable strategic considerations for enterprise leaders evaluating blockchain finance in 2026.
Worldwide Blockchain Insurance Market
- Asset and liquidity strategy: The scale of digital asset management activity and the expansion of tokenized instrument infrastructure suggest that treasury, custody, and investment operations should reassess exposure to blockchain-based instruments as both an efficiency lever and a diversification tool.
- Capital markets modernization: Tokenization of real-world assets and the emergence of blockchain-native marketplaces indicate that origination, distribution, and secondary trading workflows may be restructured around programmable infrastructure. Early movers in pilot design and partnership formation can influence standards and capture liquidity advantages.
- Payment and settlement optimization: Cross-border payment and peer-to-peer transfer volumes underscore persistent demand for faster settlement and reduced intermediary friction. Organizations with international cash flow requirements should evaluate blockchain-based rails against conventional correspondent banking cost structures and operational risk profiles.
- Regulatory-aligned product design: With clearer frameworks emerging for stablecoins, securities treatment, and crypto-asset services, product roadmaps should incorporate compliance architecture from inception. The cost of retrofitting regulatory alignment is materially higher than designing within an informed regulatory perimeter.
- Competitive positioning: Concentration patterns in the market indicate that a limited set of participants is capturing a disproportionate share of activity. This suggests that late entrants may face increasing barriers to differentiation unless they target underserved segments, specialized use cases, or distinct jurisdictional opportunities.
What the Full Study Delivers
This overview provides the strategic context. The complete PW Consulting Blockchain Finance Market report delivers the operational intelligence required to convert context into decision-ready plans. The study includes detailed segmentation analysis, historical revenue tracking, forward forecasts calibrated across multiple dimensions, protocol-level evaluations, application-domain depth, and regional deployment patterns. It examines competitive positioning with structured company profiles, recent development tracking, and partnership and product-launch timelines that reveal how market leaders are executing. It also integrates the regulatory and infrastructure cost context that shapes deployment economics and risk exposure.
To access the complete dataset, segmentation breakdowns, competitive profiles, and forecast scenarios that support granular strategic planning, we invite you to explore the full report at the source page. The complete intelligence package is designed for executive teams, investment committees, and strategy functions that require precise market structure, credible forward projections, and actionable competitive context to guide 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Blockchain Finance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


